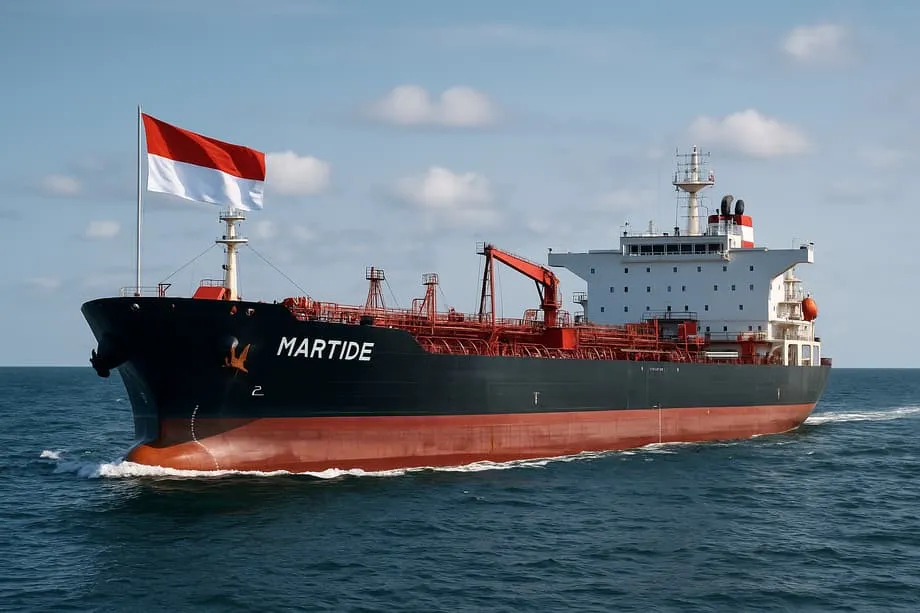
A Large Fuel Appetite, a Small Safety Buffer
Indonesia consumes an average of 1.6 million barrels of fuel a day, imports approximately 60% of its supply and holds reserves covering only about 23 days. As of April 25, 2026, those figures explain why conflict far from the archipelago can quickly affect prices at its petrol stations and put pressure on government finances.
Contents
- A Large Fuel Appetite, a Small Safety Buffer
- Why Singapore Supplies So Much Gasoline
- Why the Reserve Cannot Simply Be Enlarged
- Hormuz Connects a Distant Conflict to Asian Markets
- Higher Prices Reach Drivers and the State Budget
- Changing Suppliers and Building More Storage
- How Indonesia Became an Oil Importer
- Southeast Asia's Growing Import Bill
- Electric Vehicles and Solar Offer Another Route
- The Electricity and Manufacturing Challenge
- Key Points
Energy and Mineral Resources Ministry data put daily consumption at that level through mid-April 2026. Gasoline imports covered 60.18% of domestic requirements during 2025. Indonesia, once an oil exporter and still a major regional energy producer, now relies on international shipping for nearly two thirds of its fuel supply.
Consumer protection advocate Tulus Abadi warned on Sunday that this dependence leaves the country exposed to geopolitical turbulence. He described fuel as a shrinking commodity whose price remains highly sensitive to global developments and urged consumers to use it carefully.
"The public must understand that this is an imported commodity, so its use should be approached carefully," he stated.
Instability in the Middle East earlier this year brought that vulnerability into everyday life. International market shocks reached Indonesian fuel markets, prompting price adjustments affecting millions of drivers.
Why Singapore Supplies So Much Gasoline
Singapore supplies 63% of Indonesia's gasoline imports despite having virtually no domestic crude oil reserves. Malaysia accounts for another 33.14%, followed by China at 1.32% and Oman at 1.05%.
Singapore's position reflects the importance of refining capacity and transport infrastructure. A country can import crude oil, turn it into gasoline and other fuels, and sell those products abroad without owning the oilfields that produced the crude.
Energy and Mineral Resources Minister Bahlil Lahadalia has questioned the cost of this arrangement. He described Singapore's pricing as "shameful", saying that supplies from Indonesia's close neighbour compare unfavourably with those sourced from the Middle East.
Diesel presents a different picture: imports covered only 12.17% of Indonesian demand in 2025, compared with 60.18% for gasoline. Gasoline dominates the consumer market, particularly for private vehicles, making dependence on Singapore especially relevant to household budgets.
A supplier accounting for nearly two thirds of gasoline imports also concentrates risk. Corruption investigations involving state energy company Pertamina have added urgency to diversification efforts. Investigators have alleged irregularities in oil import practices between 2018 and 2023 that resulted in substantial state losses, prompting a reassessment of reliance on trading intermediaries based in Singapore.
Why the Reserve Cannot Simply Be Enlarged
Indonesia's reserve of approximately 23 days reflects limited storage infrastructure rather than a shortage of fuel at present. Existing facilities can hold roughly 25 days of supply at maximum capacity, leaving little room to build a much larger buffer.
Bahlil addressed demands for a reserve lasting 60 days by explaining that additional fuel would need somewhere to go.
Sometimes people say we should stock fuel for 60 days. But where would we store it? We simply do not have enough storage capacity.
The current reserve sits slightly above the minimum national standard, described as 20 to 23 days. It remains far short of the larger strategic buffer discussed by the minister. Limited investment in strategic petroleum infrastructure has left Indonesia with little spare storage capacity during a prolonged international crisis.
Bahlil previously used an estimate of about 21 days when discussing how long reserves and storage could sustain the country during a conflict. That warning describes an even narrower operating margin than the current figure of 23 days.
"This is a geopolitical issue. If a crisis or conflict occurs, our oil reserves and storage capacity would last only about 21 days," he warned.
A reserve measured in days is a cushion between normal consumption and interrupted deliveries. Indonesia's narrow cushion leaves it exposed to a supply shock that could develop faster than emergency arrangements can take effect. Buying from additional countries helps spread risk, but larger stocks also require tanks, terminals and other storage facilities.
Hormuz Connects a Distant Conflict to Asian Markets
Iranian forces closed the Strait of Hormuz earlier this year, blocking a shipping route handling approximately 20% of global seaborne crude oil. The Islamic Revolutionary Guard Corps warned oil tankers following US and Israeli strikes on Tehran, effectively cutting a major artery of international energy trade.
The disruption affected routes carrying roughly 84% of crude oil and 90% of liquefied natural gas bound for Asian markets. Liquefied natural gas, or LNG, is gas cooled into liquid form for transport by ship. Indonesia sources significant portions of its imports through routes exposed to instability in the region.
The International Energy Agency has documented Southeast Asia's exposure: the region imports approximately 60% of its oil from the Middle East. Japan depends on the region for 95% of its crude supplies, while South Korea depends on it for 70%.
Indonesia's own dependence differs, but its purchases sit within the same international network of producers, refineries, traders and ships. Disruption in one part of that network can raise prices elsewhere, including for fuel bought from a supplier outside the immediate conflict zone.
Refineries across Southeast Asia were designed to process "heavy sour" or "medium sour" crude typical of Middle Eastern oilfields. These terms describe characteristics of the oil, including its density and sulphur content, that matter to the equipment used to refine it.
Switching to alternative supplies, including oil from the United States, would require substantial refinery modifications and investment. That technical constraint helps explain why Indonesia and neighbouring countries cannot quickly replace Middle Eastern supplies simply by choosing another seller.
Higher Prices Reach Drivers and the State Budget
Pertamina raised prices for higher grade fuels by more than 50% as international energy markets reacted to the crisis. These products follow global price indices, which link Indonesian pump prices to movements in international markets.
Tulus described the increases as unavoidable under those market conditions, while calling for limits on what consumers are charged. The consumer protection advocate said adjustments should reflect the actual movement in global crude prices.
"I believe this was unavoidable. What matters is that the government or operators do not set excessive prices, and that adjustments reflect global crude oil prices," he explained.
Tulus also called for prices to move in the other direction when international oil becomes cheaper. Prompt reductions would help preserve public trust and make price adjustment a two way process.
Indonesia's 2026 State Budget assumed an oil price of $70 a barrel. Crude traded above $100 a barrel during peak periods of the Middle East crisis, more than $30 above that assumption. An extended period of elevated prices could double current oil spending projections, increasing pressure on public finances and potentially widening fiscal deficits.
International price increases can eventually reach subsidised or regulated domestic prices too. The government must balance the cost of cushioning consumers against its other spending needs, while operators face the expense of purchasing fuel abroad.
The surge has already affected transport costs, manufacturing inputs and agricultural operations in Indonesia. These effects extend beyond motorists because fuel is used to move goods, run machinery and support production.
Elsewhere, jet fuel prices rose by nearly 60% in some markets. Diesel prices in neighbouring Vietnam climbed by similar margins, prompting panic buying and rationing. Indonesia has introduced conservation measures, including directives for civil servants to work from home, and discussed limits on vehicle fuel purchases as part of efforts to reduce consumption by 25%.
Changing Suppliers and Building More Storage
Jakarta has accelerated plans to reorganise its fuel imports. The government announced intentions to redirect up to 60% of imports away from Singapore towards the United States and Middle Eastern countries within six months.
That planned change forms part of a broader initiative to increase purchases of US energy by approximately $10 billion. The purchases would include crude oil, refined fuel and liquefied petroleum gas, or LPG.
The immediate response to the Middle East disruption has involved shifting crude oil and petrol purchases from that region towards the United States and suppliers in Southeast Asia. The broader diversification plan still includes Middle Eastern countries among alternatives to Singapore, reflecting the different tasks of responding to a current disruption and changing the longer term supplier mix.
Indonesia is expanding port facilities to receive larger fuel tankers. Larger ships would improve shipping efficiency and reduce dependence on the smaller vessels typically used for imports from Singapore. Investment in domestic refining capacity also aims to allow a wider range of crude oil to be processed, reducing the need to buy finished fuel abroad.
A proposed storage facility on an island near Singapore could add 30 to 40 days of reserve capacity. No completion date was given for that project. The facility would allow Pertamina to buy larger quantities when prices are favourable and retain more oil domestically.
Greater storage would reduce exposure to volatile spot markets, where purchases are made for near term delivery, and to intermediary fees that currently increase costs. Supplier diversification and storage expansion address different vulnerabilities: the first spreads purchasing risk, while the second gives Indonesia more time when deliveries are disrupted.
How Indonesia Became an Oil Importer
Indonesia's present vulnerability developed as domestic production declined and consumption grew with economic expansion and rising living standards. Research published in Nature records its transition from a net oil exporter to a net importer in 2004.
A net importer buys more oil from abroad than it sells overseas. Indonesia subsequently suspended its membership of the Organization of the Petroleum Exporting Countries, known as OPEC, in 2009.
Vietnam followed a similar course, becoming a net oil importer in 2010 and a net coal importer in 2015. These changes show how growing demand can overtake domestic production even in countries with established energy industries.
The key dates connect that longer shift with the current exposure:
- 2004: Indonesia became a net oil importer.
- 2009: Indonesia suspended its OPEC membership.
- 2010: Vietnam became a net oil importer.
- 2015: Vietnam became a net coal importer.
- 2018 to 2023: The period covered by alleged irregularities in Pertamina's oil import practices.
- 2024: The International Energy Agency published its Southeast Asia Energy Outlook 2024.
- 2025: Imports covered 60.18% of Indonesia's gasoline needs and 12.17% of its diesel demand.
- Mid-April 2026: Ministry data put Indonesian fuel consumption at an average of 1.6 million barrels a day.
Indonesia's history also explains the apparent contradiction between its reputation as an energy heavyweight and its dependence on imported fuel. Its role in regional energy production has continued while its domestic oil supply has fallen behind demand.
Southeast Asia's Growing Import Bill
The International Energy Agency's Southeast Asia Energy Outlook 2024 warns that the region will contribute more than 25% of projected global energy demand growth through 2035. Fossil fuels have met nearly 80% of its rising demand since 2010.
Coal and oil each account for more than a quarter of regional energy consumption. That reliance leaves Southeast Asian economies exposed to the cost and availability of imported fuels as demand continues to expand.
Under current policy trajectories, Southeast Asia's annual oil import bill will exceed $200 billion by the middle of the century, compared with $130 billion today. The projected increase is more than $70 billion a year, money that would go towards oil purchases rather than other domestic needs.
Energy related carbon dioxide emissions are projected to rise by one third by 2050 if current trends continue. Eight of the ten ASEAN member states have set goals for net zero emissions, meaning they aim to balance emissions released with those removed. Current policies remain insufficient to meet those targets.
Indonesia's immediate fuel problem therefore sits alongside a wider regional challenge. Southeast Asia needs to meet growing demand while managing rising import costs, exposure to shipping disruptions and the emissions associated with continued fossil fuel use.
Electric Vehicles and Solar Offer Another Route
Research from Ember Energy suggests that expanding electric vehicles, solar power and battery storage could reduce fossil fuel imports by approximately 70% across the affected sectors. The technologies already exist and have become competitive in cost with traditional systems using fossil fuels.
Indonesia's electric vehicle adoption reached 15% of new car sales in 2025, exceeding the United States at 10% for the first time. Indonesia's share was five percentage points higher. Thailand and Vietnam achieved still higher shares, showing that rapid uptake is possible with suitable policy support.
The new car sales figure describes vehicles entering the market in 2025. As more of those vehicles use electricity rather than gasoline, the energy needed for their journeys shifts from imported liquid fuel towards the electricity system.
Solar generation costs have fallen to approximately $40 per megawatt-hour, compared with more than $100 for generation using gas at current LNG prices. A megawatt-hour measures a quantity of electricity, allowing generation costs from different technologies to be compared.
Battery storage supports this shift by retaining electricity for use later. The combination of electric transport, solar generation and storage offers a way to reduce the volume of fossil fuel that must arrive by ship, rather than simply changing the country supplying it.
The Electricity and Manufacturing Challenge
Academic modelling published through ScienceDirect indicates that Indonesia's oil transition is likely to follow an S-curve involving biofuel conversion and greater electricity use. An S-curve describes change that begins slowly, accelerates as adoption spreads and then slows as it approaches its eventual limit.
The study says successful decarbonisation also depends on reducing emissions from electricity generation. Replacing gasoline with electricity shifts energy demand towards power stations, so the electricity sector must change alongside transport.
That would require an expansion of variable renewable energy, such as solar power whose output changes with available sunlight, and potentially nuclear sources. Indonesia's fuel transition therefore involves both the vehicles people buy and the way the electricity for those vehicles is produced.
The government has acknowledged the need for this change. Plans to develop nickel processing draw on Indonesia's position as the holder of the world's largest nickel reserves and aim to establish domestic battery manufacturing capabilities.
Processing minerals and manufacturing batteries within Indonesia would connect more stages of production inside the country. That strategy could help turn the archipelago from a fuel importer into a centre for manufacturing electrical technologies, retaining money in the domestic economy rather than sending it abroad for fossil fuel purchases.
The immediate priorities remain securing deliveries, keeping prices fair and increasing storage. Electric transport and changes in power generation address the longer term source of exposure: the amount of imported fuel Indonesia needs to keep its economy moving.
Key Points
- Indonesia imports approximately 60% of its fuel supply and consumes an average of 1.6 million barrels a day.
- Imports met 60.18% of gasoline requirements in 2025, compared with 12.17% of diesel demand.
- Singapore supplies 63% of gasoline imports despite having virtually no domestic crude oil reserves.
- Fuel reserves cover about 23 days, while existing storage can hold roughly 25 days of supply.
- Pertamina increased prices for higher grade fuels by more than 50% amid international market disruption.
- The 2026 budget assumed oil at $70 a barrel, while crude exceeded $100 during peak crisis periods.
- The government plans to redirect up to 60% of imports away from Singapore within six months and increase US energy purchases by approximately $10 billion.
- A proposed island storage facility near Singapore could add 30 to 40 days of reserve capacity.
- Electric vehicles accounted for 15% of new Indonesian car sales in 2025, compared with 10% in the United States.
- Reducing fuel dependence through electrification also requires changes in electricity generation.