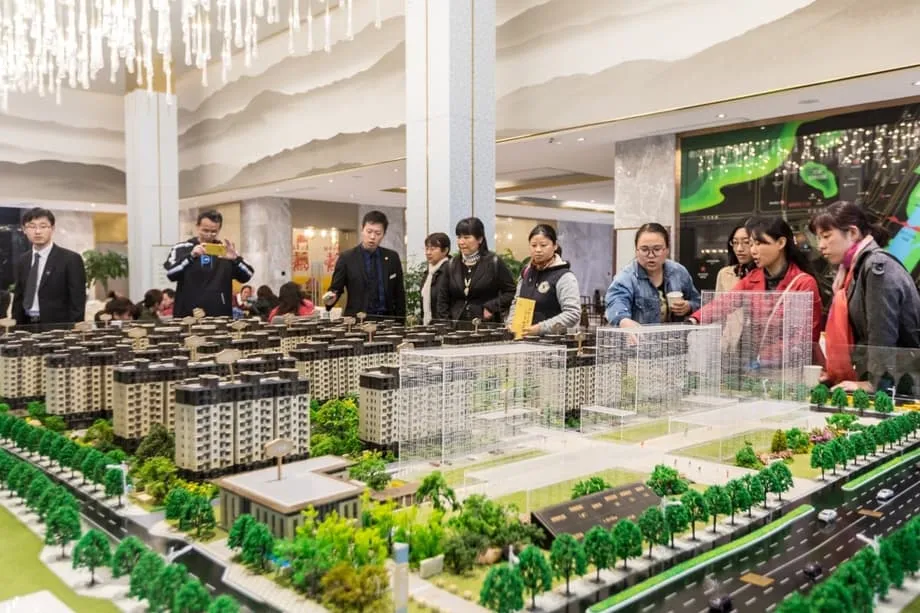
A Home Bought on a Floor That Did Not Exist
Shen paid for a 90 square metre apartment on the 34th floor of a residential building near Xi'an, the capital of Shaanxi province in northwestern China. Four years after buying it in 2013, he learned that the building had only 32 floors. The home he had purchased could never be delivered in the building as constructed.
Contents
- A Home Bought on a Floor That Did Not Exist
- Why the Cheaper Homes Have Fewer Protections
- What Buyers Give Up With the Discount
- How a Phantom Floor Can Escape Scrutiny
- Evergrande Brings the Crisis Into the Boardroom
- The Events Behind the Two Cases
- A Housing Slump Reaches Beyond Construction
- The Cost to Families and Public Trust
- Why Enforcement Is Harder on Rural Land
- Key Points
The price had appeared unusually attractive: 2,646 yuan per square metre, approximately $400 at the time and roughly one third of the average housing price in the area. For Shen, the newly built residential compound seemed to offer an affordable way into a market where conventional homes cost much more.
The discount came with a serious weakness. His apartment belonged to a category commonly called limited property rights housing, built on collectively owned rural land outside the formal system for state land. Such homes lack official government recognition and the legal protections attached to standard commercial housing.
Shen's experience has drawn national attention because it brings those risks into sharp focus. Buyers can face more than uncertain ownership or delayed construction. In this case, a developer sold space on a floor that was never built.
The story also connects a local housing dispute to China's wider property crisis. At one end are village committees and developers selling homes outside the formal registration system. At the other are large companies facing punishment for falsified financial information. In both settings, buyers and investors can commit money on the strength of promises and documents that later collapse.
Why the Cheaper Homes Have Fewer Protections
China's land system separates urban land from rural land. Urban land belongs to the state and is leased through formal arrangements that include title deeds and access to mortgages. Rural land belongs collectively to village communities.
Under the rules described in Shen's case, rural collectives are not supposed to sell or lease their land for commercial residential development. In practice, village committees and developers frequently work together to build housing on rural plots for profit. The resulting homes are commonly described as having limited property rights, also known as small property rights.
Buyers of these units cannot register them with government land bureaus and receive no official title deed. A title deed is the formal document recording ownership. Without one, a buyer lacks the recognised ownership record that accompanies a conventional home purchase. Banks generally refuse to lend against these properties.
Estimates suggest that tens of millions of such units exist across China. Their appeal is straightforward: they offer a cheaper alternative to rapidly rising urban housing prices. Shen's price, about one third of the local average, shows the size of the saving that can draw buyers into this market.
Some purchasers know that the arrangement is unconventional. Even so, buying a home with uncertain legal status is different from discovering that its floor does not exist. Shen's loss went beyond the usual uncertainty surrounding these developments and exposed a deeper level of deception.
What Buyers Give Up With the Discount
Limited property rights housing lacks many of the protections a homeowner would normally expect. Without formal registration, buildings can face demolition by local authorities with little warning. Developers can change plans without the oversight associated with recognised commercial projects.
Buyers can also find themselves behind banks and state entities when compensation is distributed. Paying for an apartment does not necessarily put a household first in line when a project fails and several parties seek repayment from the same pool of money.
Shen's discovery pointed to two possible explanations: the developer falsified the blueprints or collected money for space that was never included in the construction schedule. The precise method is not identified, but the practical result was clear. A purchase agreement and a payment could not produce the promised apartment.
His case shows how the price advantage and the legal risk are connected. A cheaper unit may offer access to housing that would otherwise be unaffordable, while leaving the buyer without the documents, checks and remedies available in the formal market. The saving is immediate; the consequences may emerge years later.
How a Phantom Floor Can Escape Scrutiny
Formal developments on state land pass through several government checks. Bureaus review plans, issue permits and inspect construction progress. Buyers can compare floor counts and unit numbers with publicly filed documents. Limited property rights projects bypass most of these checkpoints.
Local officials sometimes tolerate or encourage construction because it generates fees and supports village economies. In other cases, developers submit one set of plans to authorities while advertising a more ambitious version to buyers. A showroom plan can therefore promise something different from what is being built.
The absence of a centralised registry for rural land sales leaves no mechanism for checking advertising claims against the physical project. Buyers may see polished sales materials and floor plans without having a reliable way to confirm that contractors are building the same homes.
Shen bought in 2013 and discovered the problem four years later. That interval suggests a prolonged period in which units could continue to be sold while construction moved slowly or failed to advance. Extended delays make it harder for buyers to follow what is happening, particularly if they live far from the site.
Many purchasers also lack the technical knowledge to compare approved drawings with the steel and concrete taking shape. By the time a discrepancy becomes obvious, a developer may have moved money elsewhere or dissolved the local company responsible for the project.
Evergrande Brings the Crisis Into the Boardroom
Evergrande, once a symbol of China's construction boom, illustrates the scale of deception alleged at the other end of the property market. The China Securities Regulatory Commission accused the company and its founder, Hui Ka Yan, of inflating revenues by roughly $78 billion during the two years before it defaulted on its debts.
The regulator fined Hengda Real Estate, Evergrande's mainland business, nearly $584 million. Hui received a personal fine of $6.5 million and faces a lifetime ban from financial markets. Inflated revenue means a company's accounts present more income than it actually earned, giving investors and creditors a misleading picture of its business.
In January, a Hong Kong court ordered Evergrande to liquidate. The appointees handling that process are examining assets to repay creditors. Liquidation involves dealing with a failed company's assets and claims so that money can be distributed to those it owes.
Last September, police placed Hui under surveillance amid investigations into suspected crimes. Together, the financial penalties, court order and police action show how the property crisis reaches from individual housing purchases to the leadership of a major conglomerate.
Shen's case and Evergrande's troubles involve different scales and legal settings, yet both centre on the reliability of what developers tell people who provide money. False documents, inflated promises and misleading financial figures can keep cash flowing into businesses while the eventual losses fall on buyers, investors and creditors.
The Events Behind the Two Cases
Shen's purchase and the actions involving Evergrande unfolded across several dates. The sequence matters because buyers can wait years between committing their savings and learning whether a developer can deliver.
- 2013: Shen bought a 90 square metre apartment on the advertised 34th floor of a residential compound near Xi'an.
- Four years later: Shen learned that the building contained only 32 floors.
- The two years before Evergrande's debt default: The period in which the securities regulator accused the company and Hui Ka Yan of inflating revenue by roughly $78 billion.
- Last September: Police placed Hui under surveillance amid investigations into suspected crimes.
- January: A Hong Kong court ordered Evergrande to liquidate, with appointees examining assets to repay creditors.
- January and February: Property investment and new construction starts fell sharply compared with the previous year.
For an individual buyer, those long gaps are central to the risk. Money is paid before the finished home is available to inspect, and problems may remain hidden while construction proceeds slowly. When the promised property fails to appear, recovering the payment becomes a separate struggle.
A Housing Slump Reaches Beyond Construction
Official data released earlier this year showed that property investment in China fell by 9 percent in January and February compared with the same period a year earlier. New construction starts dropped by 30 percent, their steepest decline in more than a year.
Those figures describe two parts of the slowdown. Less investment means less money going into property development. Fewer construction starts mean fewer new projects beginning. The effects extend to jobs, suppliers awaiting payment and unfinished concrete structures where neighbourhoods were expected to develop.
Real estate and related industries account for about one third of China's economic output. A property downturn therefore reaches beyond developers themselves. Steel mills, cement plants, furniture suppliers and local banks all depend, in different ways, on homes being financed, built and occupied.
Advance payments put homebuyers inside that chain of financing. Households pay for apartments before completion, supplying money that developers use while projects are underway. When developers misrepresent revenue or sell homes they never intend to finish, buyers become both victims and unintended financiers of a risky business model.
Shen's phantom apartment gives that financial risk a concrete form. His payment bought a promise rather than a usable home, and the building's final height made the promised delivery impossible.
The Cost to Families and Public Trust
Evergrande's collapse left hundreds of thousands of buyers waiting for apartments they had already paid for. Some had committed their entire savings and borrowed from relatives. For families in that position, a failed project can affect far more than the value of a property.
The human costs described across the crisis include broken marriages, postponed retirement and mental health crises. Savings intended to provide security instead become tied to an unfinished building or a repayment claim. Unpaid suppliers and lost construction jobs spread the strain to other households.
Shen faced an especially stark version of that loss. His problem was not simply that construction had fallen behind schedule. The floor containing his supposed apartment was absent from the building, leaving no prospect of moving into the unit as sold.
Fraud involving both local developers and major companies also weakens confidence in markets, regulators and courts. Buyers need to trust that sales documents describe a real property, that authorities can identify serious breaches and that a legal claim can lead to a meaningful remedy.
Rebuilding that confidence requires visible justice for victims as well as changes to how projects are checked and financed. Fines can punish misconduct, but households also need protection before their savings disappear into a development that cannot deliver.
Why Enforcement Is Harder on Rural Land
Chinese authorities recognise that unchecked property fraud threatens social stability and economic growth. The China Securities Regulatory Commission has pledged tougher action against securities fraud and protection for small investors. The regulator described the intended strength of its enforcement in these words:
teeth and horns
The record fines involving Evergrande and Hui signal that even the largest participants can face punishment. Police surveillance of Hui also places attention on personal accountability at the top of a company.
National regulators can pursue listed companies relatively readily because their financial disclosures are visible and shareholders demand answers. Village projects on collective land are harder to police. They sit between rural governance, urban planning and private contract law, with responsibilities spread across different institutions.
Local governments sometimes resist strict enforcement because these developments house migrants and generate revenue outside formal tax channels. Officials can face a conflict between promoting economic growth and enforcing land rules, especially once paying residents already occupy a project.
For buyers such as Shen, going to court can be frustrating. Courts sometimes decline disputes involving limited property rights housing because the underlying contracts breach land rules. Even a successful judgment may be difficult to collect if the developer has transferred assets or declared bankruptcy.
The reforms proposed in response address different stages of that risk: integrating rural land records into national databases, requiring independent inspections before advance sales and placing buyers' payments in escrow accounts. An escrow account holds money under conditions that control when it can be released. Linking withdrawals to verified construction milestones would stop developers from taking the money before the required work is completed.
These proposals focus on making the promised home verifiable and keeping payments connected to construction. Shen's experience shows why both matter: a buyer needs a reliable record of what is being sold, as well as a way to prevent the purchase money from disappearing before delivery.
Key Points
- Shen bought a 90 square metre apartment near Xi'an in 2013, then learned four years later that its advertised 34th floor did not exist in a building with 32 floors.
- He paid 2,646 yuan per square metre, approximately $400 at the time and roughly one third of the local average housing price.
- Limited property rights homes are built on collectively owned rural land and lack official title deeds and many protections available to conventional buyers.
- The securities regulator accused Evergrande and Hui Ka Yan of inflating revenue by roughly $78 billion during the two years before the company's debt default.
- Hengda Real Estate received a fine of nearly $584 million; Hui received a $6.5 million fine and faces a lifetime financial markets ban.
- Property investment fell by 9 percent and new construction starts by 30 percent in January and February compared with the previous year.
- Proposed protections include integrated land records, independent inspections before advance sales and escrow accounts tied to verified construction progress.