Rp 17,668 to the Dollar Puts Indonesia Under Pressure
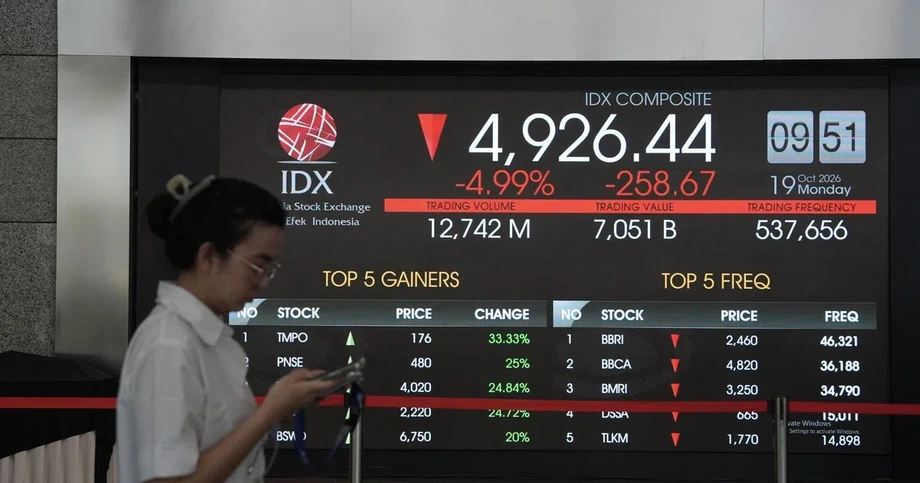
Indonesia's rupiah reached an intraday low of Rp 17,670 per United States dollar in mid-May before settling near Rp 17,668, its weakest recorded level. By May 19, 2026, the currency had lost roughly 5 percent since the start of the year, breaking through both the Rp 17,500 threshold watched by markets and the Rp 17,600 mark.
Contents
- Rp 17,668 to the Dollar Puts Indonesia Under Pressure
- Why the Budget Matters to the Currency
- Structural Weaknesses Make Shocks Harder to Absorb
- Oil, United States Rates and Share Deletions Add Pressure
- How the Pressure Built Through May
- Bank Indonesia Faces Competing Goals
- Why Villagers Still Feel a Falling Rupiah
- What Economists Say Must Change
- Possible Currency Levels and Uneven Benefits
- The Bottom Line
The exchange rate has also moved far beyond the Rp 16,500 per dollar assumption used to prepare the 2026 state budget. Finance Ministry sensitivity calculations put the additional fiscal deficit at about Rp 800 billion for every Rp 100 deviation from that assumption. At Rp 17,668, that relationship implies roughly Rp 9.3 trillion in added pressure on the deficit.
The new low carries particular weight in a country that remembers the 1998 Asian financial crisis, when the rupiah reached Rp 16,800 per dollar at its worst. The latest decline has widened the gap between official assurances that the currency is undervalued relative to economic fundamentals and investors' willingness to hold Indonesian assets.
Indonesia faces several pressures at once: higher oil prices increase its import and subsidy bills, weak tax revenues restrict government choices, and foreign investors are withdrawing money. Questions about policy consistency, institutional independence and the cost of major government programs have added to the unease.
Bank Indonesia is intervening to support the currency while trying to keep borrowing conditions supportive of growth. Households are encountering the same problem through a different channel. Imported ingredients, packaging, fuel and other goods can become more expensive even when buyers pay entirely in rupiah.
The breach of Rp 17,500 has consequently become more than a market milestone. It has sharpened concerns about Indonesia's economic resilience as global volatility tests emerging economies and domestic budget pressures leave less room to respond.
Why the Budget Matters to the Currency
Teuku Riefky, an economist at the University of Indonesia Institute for Economic and Social Research (LPEM FEB UI), argues that the decline is driven less by monetary mechanics than by worsening fiscal strains. His concern centers on the shrinking space between the government's available resources and its spending commitments.
Riefky described the pressure from energy costs and tax collection:
The fiscal issue lies in the shrinking fiscal space caused by rising fuel subsidy burdens amid higher oil prices and weak tax revenues.
Higher global oil prices make fuel subsidies more expensive to maintain. Weak tax revenues leave the government with less money to absorb that increase while paying for other commitments. A falling rupiah adds another layer of cost because dollars used to buy imported energy require more local currency.
President Prabowo Subianto's flagship initiatives also draw on the budget. Riefky pointed to the Free Meal Program (MBG) and the Red and White Village Cooperatives (KDMP), arguing that these politically popular programs are consuming resources when fiscal room is already narrowing.
Riefky urged the government to redirect spending from items he regards as less productive toward social assistance and productive expenditure that directly supports welfare and growth. His argument places spending priorities at the center of currency stabilization, alongside the actions of the central bank.
The Finance Ministry's sensitivity calculation illustrates the scale of the exposure. The gap between Rp 16,500 and Rp 17,668 is Rp 1,168 per dollar, or 11.68 increments of Rp 100. Multiplying those increments by Rp 800 billion produces the roughly Rp 9.3 trillion estimate of additional deficit pressure.
That pressure complicates efforts to keep public finances sustainable without heavier borrowing or damaging spending cuts. The government must address a larger energy bill while preserving resources for programs that support households and economic activity.
Structural Weaknesses Make Shocks Harder to Absorb
Indonesia's currency vulnerability extends beyond the current budget. The country has run current account deficits for most of the past three decades and has financed growth through volatile portfolio inflows rather than stable domestic savings. The current account tracks trade and other income flows between a country and the rest of the world.
Portfolio investment, such as money placed in shares and bonds, can leave quickly when investors become nervous or find more attractive returns elsewhere. Indonesia's reliance on those flows leaves the rupiah exposed when global investors move toward dollar assets.
Indonesia's export base remains heavily dependent on commodities. Prices for those goods can swing sharply, while exports of manufactured products and services have not generated enough foreign exchange to overcome the underlying vulnerability. Dollars earned from exports matter because they help meet demand for foreign currency.
These weaknesses help explain why the rupiah has performed worse than the Thai baht and Philippine peso during the recent dollar rally. All have faced pressure from United States interest rates staying higher for longer and from investors seeking assets regarded as safer. Indonesia's structural deficits make those external shocks harder to absorb.
Frequent policy changes have added to investor concerns. Sudden regulatory shifts and ambitious projects led by the state, without clear revenue models, have made investors more cautious. The establishment of the Daya Anagata Nusantara Investment Management Agency (Danantara), intended to consolidate assets of enterprises owned by the state, has raised governance questions.
The appointment of a nephew of President Prabowo as a deputy governor at Bank Indonesia has also fueled concerns about political influence over monetary policy. Markets are sensitive to perceptions that central bank independence could weaken, because confidence in policy decisions affects whether investors keep money in the country.
Between mid-March and mid-April, Indonesia recorded net portfolio outflows of $1.47 billion, concentrated in equities. The outflow trend continued as global appetite for risk deteriorated further.
Oil, United States Rates and Share Deletions Add Pressure
Escalating tensions in the Middle East, particularly the conflict involving Iran and the possibility of a blockade of the Strait of Hormuz, have pushed global oil prices to around $110 per barrel. Indonesia is a net oil importer, bringing in roughly one million barrels a day of combined fuel and crude.
Its annual energy import bill approaches $40 billion. Each additional dollar in the oil price adds to the import burden, widens the trade deficit and increases demand for United States dollars to pay for shipments. The weaker rupiah makes those dollar payments more expensive in local currency.
The United States Federal Reserve's reluctance to cut interest rates from the current 3.75 percent level has compounded the pressure. Yields on United States Treasury bonds maturing in 10 years have climbed to 4.47 percent, narrowing the return advantage Indonesian assets offer over dollar instruments.
Investors weigh that difference against the risks of holding emerging market assets. When they judge the extra return insufficient, they can shift money toward assets regarded as safer. Indonesia recorded net capital outflows of $1.6 billion in the first three weeks of January, and the pace accelerated after the Iran war began.
Index provider MSCI delivered another blow in its May 2026 review, removing 18 Indonesian equities from its indexes, far more than Jakarta had anticipated. The deletions reflected concerns about concentrated shareholding and limited free float in major listed companies. Free float refers to the shares available for public trading rather than those held by controlling owners.
The removals triggered heavy foreign selling ahead of index rebalancing and reduced dollar inflows into Indonesia's stock market. Together, the oil shock, attractive dollar returns and equity withdrawals have increased pressure on a currency already weakened by domestic concerns.
How the Pressure Built Through May
Indonesia's currency difficulties developed across several months. The sequence connects early capital withdrawals, later portfolio selling, falling reserves and the exchange rate's record low.
- First three weeks of January 2026: Indonesia recorded net capital outflows of $1.6 billion.
- Mid-March to mid-April: Net portfolio outflows reached $1.47 billion, concentrated in equities.
- March and April: Foreign exchange reserves fell from $148.2 billion to $146.2 billion, completing four consecutive months of declines.
- May 2026: MSCI removed 18 Indonesian equities during its index review, prompting foreign selling ahead of rebalancing.
- Mid-May: The rupiah touched Rp 17,670 per dollar before settling near Rp 17,668, taking its decline since the start of the year to roughly 5 percent.
The next policy event identified is Bank Indonesia's May meeting. Economists at DBS and OCBC expect a rise of 25 basis points to 5 percent. A basis point is one hundredth of a percentage point, so that forecast represents an increase of 0.25 percentage points. As of May 19, it remains an expectation rather than an announced decision.
Bank Indonesia Faces Competing Goals
Bank Indonesia Governor Perry Warjiyo has insisted that the central bank is making every effort to defend the rupiah. Intervention has intensified in the spot currency market, non deliverable forwards and the bond market. Spot transactions involve currency exchanged at current rates, while non deliverable forwards provide a way to manage exchange rate exposure through contracts settled without delivery of the underlying currency.
The central bank has deployed seven stabilization measures, including operations through Bank Indonesia Rupiah Securities (SRBI). These efforts seek to support the currency and financial markets while preserving conditions for economic growth.
Foreign exchange reserves nevertheless declined for a fourth consecutive month in April, falling by $2 billion from March to $146.2 billion. That stock still covers roughly 5.8 months of imports, but continued declines constrain how long the central bank can maintain intervention without creating a new concern about its own resources.
The policy tension is known in economics as the Impossible Trinity. A country cannot simultaneously maintain a stable exchange rate, conduct an independent monetary policy and allow capital to move freely. Pursuing currency stability while keeping interest rates supportive of growth places pressure on reserves when investors are moving money abroad.
Bank Indonesia's effort to smooth rupiah volatility has therefore come at a growing reserve cost. A rate increase would shift the balance toward defending the currency, but some analysts warn that higher rates would only buy time without fiscal consolidation, meaning measures to bring government spending and revenues into a more sustainable balance.
Finance Minister Purbaya Yudhi Sadewa's Bond Stabilization Fund (BSF) scheme faces the same confidence problem. Riefky argues that it is unlikely to have a meaningful effect while investors remain skeptical about the government's broader fiscal direction.
Why Villagers Still Feel a Falling Rupiah
President Prabowo has twice told audiences in East Java that villagers have no reason to worry because they do not transact in United States dollars. He has also insisted that Indonesia's food and energy supplies are secure and that the economy is fundamentally strong.
The remarks prompted sarcastic memes and parodies across Indonesian social media. One viral video mocked the suggestion that rural communities are insulated from global markets by claiming that villagers still use horses for transport and must hunt for food.
Finance Minister Purbaya later softened the message, explaining that the president had been trying to cheer up a village crowd. Economists nevertheless challenged the idea that paying in rupiah protects rural households from a weakening exchange rate.
Bhima Yudhistira, executive director of the Centre of Economic and Law Studies (Celios), pointed to imported fuel, liquefied petroleum gas, fertilizer, motorcycles and electronics used even in remote communities. When more rupiah are needed to buy those goods or their imported components, the cost can reach consumers through local prices.
In Blitar, East Java, Ninik Sukarmi, a housewife aged 57, noticed that portions of tofu and tempeh from her local seller had become smaller than they were before the Eid holidays in March. When she asked about the change, the seller cited higher costs for plastic packaging and imported soybeans.
Her experience shows how the exchange rate reaches familiar food through ingredients and packaging. A household may buy a traditional staple from a nearby seller, yet part of its cost still depends on supplies purchased through global markets. Smaller portions also reduce what a family's money buys, even when the change is less visible than a higher price.
What Economists Say Must Change
Eddy Junarsin, an economist at Gadjah Mada University, warned that poorly managed pressures could trigger destabilizing speculation, with panic encouraging further currency selling. His concern is that the decline could feed on itself as investors and other market participants react to expectations of additional losses.
Junarsin described a difficult interest rate choice. Cutting rates could stimulate growth but risk fueling inflation. Raising rates could restrain inflation while slowing growth and increasing unemployment. Either direction carries a cost when the government and central bank are trying to protect both the currency and economic activity.
Foreign exchange intervention is necessary, he said, but should remain limited and sterilized. Sterilization means offsetting the effect of an intervention on the amount of money circulating domestically. He argued that intervention should avoid draining reserves or weakening confidence over the longer term.
Junarsin also stressed that monetary policy cannot work alone. Government support is essential, particularly through maintaining budget balance and managing national debt efficiently. Clear policy communication, legal certainty and political stability are needed to attract investment that stays, rather than speculative money that can leave quickly.
Riefky's fiscal concerns and Junarsin's policy recommendations converge on the need for coordination. Currency intervention can respond to immediate market pressure, while budget decisions and predictable rules address the concerns that influence whether investors return and remain.
Possible Currency Levels and Uneven Benefits
Technical market analysts warn that breaking Rp 17,500 could mark the beginning of a prolonged consolidation phase, with the rupiah trading within a weak range rather than recovering quickly. Their baseline scenario assumes Middle East tensions continue without a major escalation.
Under that scenario, the rupiah could trade between Rp 17,550 and Rp 17,700 per dollar through the coming months. A prolonged closure of the Strait of Hormuz, accompanied by oil prices above $120 per barrel, would create a more severe situation. Forecasts under those conditions suggest levels of Rp 18,000 or even Rp 18,300 per dollar.
Those weaker levels would increase inflation driven by imported goods, squeeze company profit margins and raise the risk of layoffs as manufacturers try to reduce costs. The same combination of expensive energy and a weaker currency would put further pressure on households and the public budget.
A weaker rupiah does offer some benefits. Indonesian exports become more competitive in foreign currency terms, and lower local production costs for overseas firms could attract foreign direct investment. Tourism has already received a lift, with Singaporean visitors traveling to Batam and Bintan to benefit from favorable exchange rates.
Those gains are unlikely to offset the broader economic damage if the currency continues to slide without restraint. As of May 19, Indonesia's challenge is to contain the immediate market pressure while addressing spending, revenue and confidence problems that currency intervention alone cannot resolve.
The Bottom Line
- The rupiah touched Rp 17,670 per dollar and settled near Rp 17,668 in mid-May, its weakest recorded level and roughly 5 percent below its value at the start of 2026.
- The 2026 budget assumes Rp 16,500 per dollar. Finance Ministry sensitivity figures imply about Rp 9.3 trillion in additional deficit pressure at Rp 17,668.
- Rising fuel subsidies, weak tax revenues and spending on MBG and KDMP have narrowed fiscal room, according to economist Teuku Riefky.
- Commodity dependence, current account deficits, volatile investment flows and concerns about policy and institutional independence have weakened confidence.
- Oil near $110 per barrel, United States interest rates and MSCI's removal of 18 Indonesian equities have added external pressure.
- Foreign exchange reserves fell to $146.2 billion in April. DBS and OCBC economists expect a 25 basis point rate increase to 5 percent at Bank Indonesia's May meeting.
- Rural households are exposed through imported goods and ingredients, including the soybeans and packaging behind smaller tofu and tempeh portions in Blitar.
- Forecasts put the rupiah at Rp 17,550 to Rp 17,700 under the baseline scenario, with Rp 18,000 to Rp 18,300 possible if a prolonged Hormuz closure pushes oil above $120.