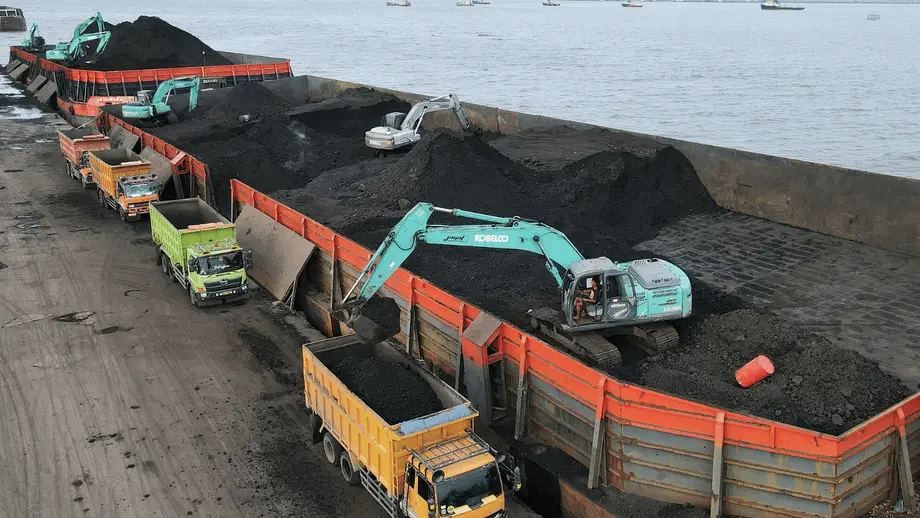
A shrinking market for Indonesia's biggest coal customers
Indonesia's coal exports fell 12% to 187 million tons in the first five months of 2025, according to analytics firm Kpler, as China and India bought less Indonesian coal and turned increasingly to competing suppliers. Shipments reached their lowest level in three years, putting pressure on an industry that contributes about 3.6% of Indonesia's economic activity and employs tens of thousands of people.
Contents
- A shrinking market for Indonesia's biggest coal customers
- Why higher energy coal is winning buyers
- China and India expand their supply choices
- Domestic production adds to the pressure
- Falling prices change the economics
- Can Indonesian buyers absorb more coal?
- Idle machinery and a search for reliable customers
- Regulations add to miners' financial strain
- Coal expansion clashes with energy transition plans
- A warning about dependence on a few buyers
- Key Points
Indonesia, long the world's largest exporter of thermal coal, faces a difficult combination: its biggest customers are producing more coal themselves, while falling international prices are making coal with a higher energy content more attractive. Thermal coal is burned to generate heat and electricity.
Exports of Indonesian thermal coal to China fell 12.3% in January through May, while shipments to India dropped 14.3%. Both declines were steeper than the respective countries' reductions in total coal imports. China and India together account for nearly two thirds of Indonesia's coal exports, leaving Indonesian producers heavily exposed to changes in their purchasing.
The pressure reaches beyond export earnings. Mining companies are dealing with idle equipment, demands for lower costs and regulations they say increase financial strain. They are seeking more domestic buyers, especially mineral smelters, but expected growth in Indonesian consumption is too small to absorb the coal that producers have been supplying.
As of June 30, 2025, the industry faces two connected challenges: competing for buyers who want more energy from each ton of coal, and adjusting production as demand from its largest overseas markets weakens.
Why higher energy coal is winning buyers
Indonesia predominantly produces coal with medium and low calorific value, or CV. Calorific value measures how much energy a fuel releases when burned. Coal with a higher CV provides more energy per ton, allowing a power plant or industrial user to meet its needs with a smaller quantity.
Higher grades from suppliers including Australia, Mongolia, South Africa and Russia have become more attractive as global coal prices have fallen. The price gap between lower and higher grades has narrowed, changing the calculation for buyers who compare the energy they receive with the money they spend.
Vasudev Pamnani, director at Indian coal trader I-Energy Natural Resources, explained why buyers are reconsidering Indonesian supply:
Higher CV coal is more expensive, but produces more energy for every dollar spent at current prices. One million tons of higher CV coal can replace 1.2-1.3 million tons or even 1.5 million tons from Indonesia.
The comparison puts Indonesia's challenge in practical terms. A buyer may pay more for each ton of higher grade coal but need fewer tons to obtain the same energy. Power plants and industrial users can therefore reduce the amount they burn, cutting costs and emissions while meeting their energy needs.
Price competition also extends to coal of similar quality. Discounted Russian supplies are squeezing Indonesian exports, according to Kpler analyst Zhiyuan Li, who said Indonesia's medium and low calorific coal was struggling against cheaper alternatives. Indonesia is consequently facing competition both from suppliers selling more energy per ton and from those offering comparable grades at lower prices.
China and India expand their supply choices
Mongolia's coal exports to China rose 44.8% in the first five months of 2025, while South African shipments to India increased 26.1%. Their shares of the Chinese and Indian markets, respectively, reached record highs as buyers shifted their purchasing.
Australia's higher grade coal has gained market share in China. Indian traders have also been diversifying toward coal with greater energy content. China and India have increased purchases from Kazakhstan, Colombia, Mozambique and Tanzania, widening the range of suppliers competing with Indonesia.
Tanzania has emerged as a new participant in the global coal market since the Russia-Ukraine conflict disrupted established trade routes. Those disruptions have encouraged buyers to find new partners and have helped redirect coal shipments between countries.
Transport has supported the shift. Better infrastructure and rail links have made coal arriving in China from Mongolia and Russia more economical. At sea, an oversupply of dry bulk shipping capacity has kept freight rates low, helping buyers purchase coal from a wider range of origins. Dry bulk ships carry unpackaged commodities such as coal.
Indonesia still has a geographical advantage with nearby Southeast Asian customers. Yet the combination of cheaper transport elsewhere and more competitive coal prices has broadened the choices available to its two largest buyers.
Domestic production adds to the pressure
China's coal output reached a record 4.9 billion tons, while India's production passed 1 billion tonnes. Both countries have been expanding local supply to strengthen energy security and reduce dependence on imports, while seeking to manage costs and control emissions.
More domestic coal means utilities and industrial consumers can meet a larger share of their needs without buying from overseas. For Indonesia, that reduces the market available to exporters even before customers choose between competing foreign suppliers.
China's benchmark thermal coal price has fallen to its lowest level in four years. Chinese utilities are increasingly able to obtain better quality coal domestically or from nearby suppliers, adding pressure on Indonesian market share.
Li Xuegang, an analyst at the China Coal Transportation and Distribution Association, described how tighter environmental policy affects buying decisions:
The government's tighter emission controls will slash demand for low-heating and poor-quality grades.
Indonesia's export decline therefore has several causes operating together. China and India are increasing their own production, purchasing from a wider range of countries and becoming more selective about the energy content of imported coal. Indonesian suppliers must compete in a smaller import market while responding to changing quality requirements.
Falling prices change the economics
Global coal prices have been declining since late 2023. In May 2025, the Australian Newcastle benchmark for coal with an energy content of 6,300 kilocalories per kilogram averaged $104.41 per ton, down 26.5% from a year earlier. The quoted price was on a free on board basis, meaning before the cost of shipping it to the buyer.
Indonesian and Australian coal indexes covering grades preferred by Chinese buyers have both fallen, but the Australian benchmark has dropped faster. Higher grade Australian coal has consequently become more accessible, accelerating the move away from Indonesian supply.
Indonesia's own reference price, known as HBA, has also declined. It was set at $98.61 per ton for the second half of June 2025, down 2.33% from the first half of the month and 23% below its March level.
Some buyers argue that the HBA, used as the basis for export shipments, remains above prevailing international market prices and has contributed to weaker exports. Indonesian producers are therefore dealing with both falling prices and complaints that the official reference still makes their coal less competitive.
The main developments leading into the end of June show how the pressure has built:
- Since late 2023, global coal prices have been falling.
- In 2024, Indonesia produced 836 million tons of coal and consumed 233 million tons domestically.
- In January through May 2025, Indonesian exports fell 12% to 187 million tons, while shipments to China and India fell 12.3% and 14.3%, respectively.
- In May 2025, Australian Newcastle coal averaging 6,300 kilocalories per kilogram cost $104.41 per ton, down 26.5% from a year earlier.
- For the second half of June 2025, Indonesia's HBA was set at $98.61 per ton.
Can Indonesian buyers absorb more coal?
Indonesian miners are redirecting sales toward the domestic market, where mineral processing offers an outlet for coal that is harder to sell abroad. Domestic deliveries now represent 48.6% of national supply, the highest share in more than a decade.
Nickel smelters have become a particularly attractive customer. These facilities use energy to process ore into metal and offer better prices than the heavily regulated power utility sector or international buyers. Expanding mineral processing has given miners another source of demand as exports weaken.
Indonesia's domestic market obligation, or DMO, requires producers to sell a portion of their coal locally. Smelters are expected to absorb 31.2% of this year's DMO, while electricity generation remains the largest consumer at 58%.
Domestic demand nevertheless has limits. Consumption is expected to rise to between 250 million and 260 million tons in 2025, from 233 million tons in 2024. That represents an increase of 17 million to 27 million tons.
Production is projected to fall below 800 million tons this year, from 836 million tons in 2024. Even with lower output and higher local consumption, a large amount of coal will still need an overseas buyer. Smelter growth can provide relief, but it cannot absorb production on the scale Indonesia has been supplying.
Idle machinery and a search for reliable customers
Weaker demand is already affecting mining operations. Equipment bought to support higher output is being used less, leaving companies with machinery that generates less revenue while still tying up capital.
Ardhi Ishak Kosen, head of industrial relations at the Association of Indonesian Mining Professionals, known as Perhapi, described the situation:
Mining equipment is underutilized, some machines stand idle, while others run on reduced hours or not at all.
Ardhi has urged coal producers to improve operating efficiency and reduce capital expenditure. For companies facing weaker sales, that means controlling the cost of producing coal and limiting spending on equipment or expansion.
Producers are also concentrating on existing contracts and nearby markets that continue to use Indonesian grades. Gita Mahyarani, acting executive director of the Indonesian Coal Mining Association, known as APBI, outlined that approach:
Producers are prioritizing the fulfillment of existing contracts. They are especially focusing on countries still reliant on medium-calorific value coal in the Southeast Asian region, where the use of coal-fired power plants remains high and continue to show solid demand for [MCV] coal, and their proximity offers a logistical advantage.
Southeast Asian demand gives miners a market suited to their coal and relatively short shipping distances. Cost efficiency has become a priority as companies try to preserve that business. Limited growth in local demand and the risk of producing too much coal remain concerns.
Regulations add to miners' financial strain
Indonesian mining companies are asking the government to remove policies they say make the downturn harder to manage. Ardhi has called for the withdrawal of mandatory B40 biodiesel blending and requirements to retain a portion of foreign exchange earnings from exports in Indonesia.
The B40 policy requires the use of a fuel blend containing 40% biodiesel. Miners identify the fuel requirement and the retention of export earnings as financial burdens at a time when coal prices and overseas sales are falling.
Domestic supply rules and high royalties also squeeze profits. Royalties are payments made to the government for extracting resources. For the state, a prolonged coal downturn threatens revenue as well as jobs in mining regions; for producers, these payments remain part of the cost of operating in a weaker market.
Companies face other constraints on their response. Most Indonesian coal businesses are tightly controlled by insiders, limiting flexibility and innovation. Access to international financing is restricted, while private companies and investors generally focus on returns in the near term rather than plans for a longer transition.
Inconsistent government policies add to the uncertainty. Together, these pressures make it harder for miners to adjust their businesses while maintaining earnings and employment. Regulatory relief is one industry request, but the central commercial problem remains the reduced appetite for Indonesian coal among its largest customers.
Coal expansion clashes with energy transition plans
Indonesia has pledged to reduce emissions and move toward cleaner energy, while continuing to expand coal production and approve new plants. Domestic subsidies keep coal inexpensive, supporting its use even as the country pursues a different direction for its future energy supply.
The state electricity utility plans to retire coal plants early under a $20 billion transition deal. At the same time, new coal plants are being built to support mineral smelting. The effort to give miners more domestic customers therefore sits alongside plans to reduce coal use in electricity generation.
Abrupt export bans have also disrupted international markets. Indonesia's policies must account for local energy needs, industrial development, export earnings and emissions commitments, interests that are pulling in different directions.
China's changing energy supply adds another source of pressure. More than 75% of the growth in its energy demand last year was met by clean energy sources. India is also investing heavily in renewable energy and seeking to reduce its dependence on imported coal.
Those changes accompany the immediate competition over coal quality and price. Indonesia's customers are adjusting both where they buy coal and how they meet growing energy needs, leaving exporters exposed to developments beyond the mining industry itself.
A warning about dependence on a few buyers
Indonesia's reliance on China and India makes a sustained change in either market costly. Their combined share of nearly two thirds of exports means that stronger domestic coal production or a preference for other suppliers can quickly affect Indonesian mines, government income and regional employment.
Hazel Ilango of the Energy Shift Institute cautioned that miners need to respond to the warning signs:
These are signs that Indonesian coal miners have to start taking seriously as well.
The depth and duration of the downturn remain uncertain. Its immediate features are already visible: lower exports, cheaper competing coal, growing production in customer countries and a domestic market too small to absorb Indonesia's existing output.
Indonesia faces pressure to diversify its economy and energy sector while managing the consequences for workers and businesses dependent on coal. Improving efficiency and selling more to smelters may help companies manage current conditions, but a lasting adjustment also requires investment decisions that account for changing overseas demand and the country's clean energy commitments.
Key Points
- Indonesia's coal exports fell 12% to 187 million tons in January through May 2025, their lowest level in three years.
- Shipments to China declined 12.3%, while exports to India fell 14.3%. The two buyers account for nearly two thirds of Indonesian coal exports.
- Falling prices have made higher energy coal more attractive, while discounted Russian coal also competes with Indonesian grades.
- China and India are producing more coal domestically and buying from a wider range of foreign suppliers.
- Indonesian consumption is forecast at 250 million to 260 million tons in 2025, against production projected below 800 million tons.
- Miners are pursuing smelter sales, existing contracts and Southeast Asian customers while seeking lower costs and regulatory relief.
- Indonesia continues to support coal production and new plants while pursuing emissions cuts and early plant retirements under a $20 billion transition deal.