A Mongolian banking partnership built around credit data
South Korea's KakaoBank has signed an agreement to acquire 15 percent of Mongolia's M Bank, putting credit assessment technology at the centre of its third overseas banking partnership. The investment would make KakaoBank the second largest shareholder in a lender with about 700,000 customers, roughly one fifth of Mongolia's population.
Contents
- A Mongolian banking partnership built around credit data
- How the agreement developed
- What 700,000 customers mean in Mongolia
- How borrowers with little credit history could benefit
- Why the models must fit local businesses
- Changes planned for the mobile banking app
- A third overseas market, with a different focus
- What the stake changes for KakaoBank
- Key Points
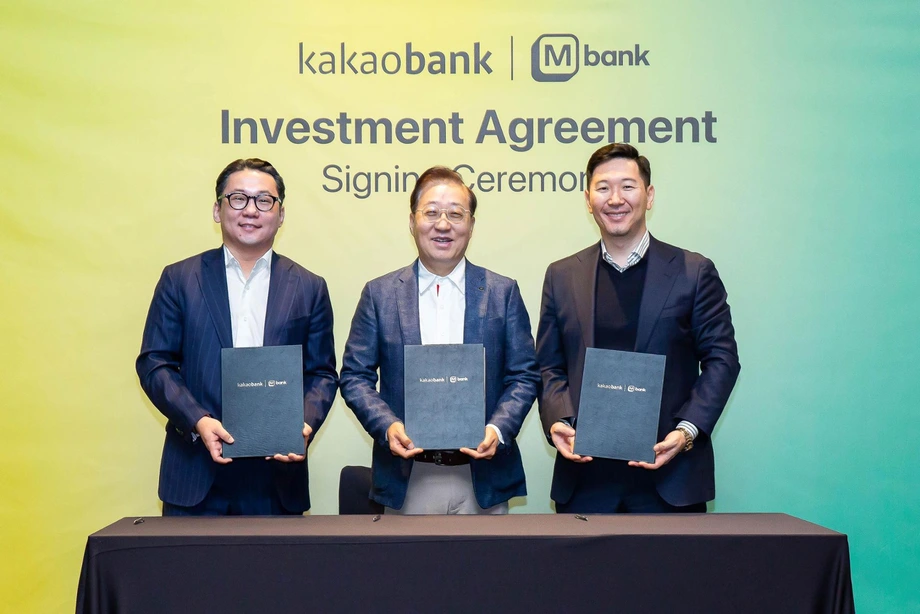
KakaoBank announced the investment on November 18, following a signing ceremony on November 17 at Gravity Josun Seoul Pangyo in Seongnam, South Korea. The bank described an acquisition agreement, while the purchase was also reported as completed on November 18. The investment amount was not disclosed.
The partnership reaches beyond owning shares. KakaoBank and M Bank plan to develop financial products, improve the Mongolian bank's mobile application and build systems that assess borrowers using financial records alongside information from telecommunications and retail businesses.
M Bank belongs to MCS Group, Mongolia's largest conglomerate, whose businesses span those sectors. That combination gives the partners a local customer base and potential sources of data for assessing people who have little conventional borrowing history.
For Mongolian customers, the central promise is access to lending that takes a broader view of their circumstances. For KakaoBank, the investment creates another overseas business alongside Indonesia's Superbank and Thailand's BankX, with Mongolia intended as a base for exploring Central Asian markets.
How the agreement developed
KakaoBank and MCS Group began with a strategic memorandum of understanding in April. Such a document sets out areas where companies intend to cooperate before they finish detailed investment and operating agreements.
M Bank's investment terms announcement records another step: the signing of a document setting out the basic investment terms during the Mongolia–Korea Business Forum, held during South Korean President Lee Jae-myung's state visit to Mongolia.
M Bank said at that stage that KakaoBank aimed to invest before the end of the year, after completing agreements and required procedures. Its announcement also identified credit scoring and broader access to digital financial products as central parts of the cooperation.
- 2022: M Bank was established as a financial subsidiary of MCS Group.
- April: KakaoBank and MCS Group signed a strategic memorandum of understanding.
- During the Mongolia–Korea Business Forum: The partners signed a document setting out basic investment terms.
- November 17: The investment agreement signing ceremony took place in Seongnam.
- November 18: KakaoBank announced the 15 percent investment.
The progression matters because the relationship now combines an ownership interest with plans to share banking technology. KakaoBank will have a financial stake in M Bank's business as well as a role in developing services.
What 700,000 customers mean in Mongolia
M Bank has attracted around 700,000 customers since its establishment in 2022, according to KakaoBank. KakaoBank describes it as Mongolia's only digital bank.
Mongolia has about 3.5 million people. Dividing 700,000 by 3.5 million gives 20 percent, matching the population comparison cited by the companies. In simple terms, M Bank's customer count is equivalent to about one person in every five across the country.
KakaoBank brings a much larger operating base. It has more than 27 million customers and approximately $60 billion in assets. Those figures help explain the partnership's appeal to M Bank: access to experience from a digital lender serving tens of millions of people.
M Bank chief executive Temuulen Batmunkh has described the investment as Mongolia's first instance of a foreign bank serving individual customers becoming a shareholder in a local bank. M Bank's own announcement calls the cooperation the first partnership of a major digital bank in Mongolia's banking sector.
How borrowers with little credit history could benefit
KakaoBank's main technical contribution will be its experience assessing borrowers with medium or low credit scores and customers with limited financial transaction histories. The latter are often called thin file customers because banks have relatively little recorded information about their borrowing and repayment.
A credit assessment model is a system that helps a lender estimate whether someone can repay a loan. Traditional models rely heavily on financial information, including previous loans and repayment records. Someone who has rarely borrowed may have little information for that system to assess.
KakaoBank and MCS Group intend to develop alternative models that also use nonfinancial data. Their plans identify telecommunications and retail information alongside financial data, drawing on the range of businesses within MCS Group.
KakaoBank chief executive Yun Ho-young said in M Bank's official announcement that the Korean lender had provided 16 trillion won in loans to customers with medium or low credit histories. He presented that lending experience as a foundation for improving M Bank's credit assessment capabilities.
For a customer with little borrowing history, the intended change is practical: a lender could consider a wider set of information when reviewing an application. The partners' stated aim is to make financial services more accessible to people who struggle to obtain credit through existing assessment methods.
Why the models must fit local businesses
MCS Group and KakaoBank are developing credit assessment models for more than M Bank alone. The planned work covers the group's specialist consumer finance company, financial platform and digital bank.
Each business has its own customers and lending activities. The partners therefore plan to design models around those business characteristics and Mongolia's financial conditions, rather than simply transferring a Korean system unchanged.
KakaoBank also plans to share risk management expertise. In lending, that means estimating potential losses, deciding how much credit to extend and monitoring whether customers can keep up with repayments. Those tasks sit alongside the goal of reaching more borrowers.
The use of information across MCS Group's businesses will depend on local rules and customer consent procedures. The companies have not detailed the precise data they will use, when the models will enter service, how widely they will guide lending decisions or whether technology advice will generate separate fees. Those operating details will shape both customer access and the commercial value of the partnership.
Changes planned for the mobile banking app
M Bank customers may also see changes in the way they use the bank's application. KakaoBank plans to advise on user experience and user interface design, commonly shortened to UX and UI.
User experience concerns how easy it is to complete a task, such as finding account information or applying for a product. User interface concerns the screens, menus and buttons through which the customer carries out that task. The partners intend to make M Bank's mobile banking service more convenient.
The cooperation also includes jointly developing financial products and services and sharing international digital banking experience. The stated ambitions extend to individuals and people running small and medium businesses, with more accessible products and flexible terms.
Temuulen Batmunkh, M Bank's chief executive, described how the two sides expect their capabilities to fit together:
We expect to combine Kakao Bank's digital banking expertise with the MCS Group ecosystem to develop new financial services for millions of customers.
MCS Group contributes its local businesses and customer relationships. KakaoBank contributes experience in operating a digital bank, designing services and assessing lending risk. The proposed products bring those roles together.
A third overseas market, with a different focus
Mongolia follows KakaoBank's expansion through Superbank in Indonesia and BankX in Thailand. Together, the three partnerships show a strategy based on working with local institutions rather than building every overseas operation alone.
KakaoBank holds 10 percent of Superbank. Its 15 percent interest in M Bank is five percentage points larger. Thailand's BankX involves a joint venture, giving the Korean lender another structure for participating in an overseas market.
The services under development also vary. In Indonesia, KakaoBank has cooperated on automatic savings and financial products using game features. In Thailand, plans include automatic savings, savings organised around groups and a financial coach using artificial intelligence.
Mongolia's most concrete technical project is credit assessment using local financial and nonfinancial information. At its 2026 Press Talk event in April, KakaoBank identified services tailored to local markets and wider access to finance as key elements of its overseas strategy. The M Bank partnership puts both ideas into a specific development programme.
What the stake changes for KakaoBank
A 15 percent holding gives KakaoBank an ownership interest and the position of second largest shareholder, while leaving it without a majority of M Bank's shares. The partnership therefore depends on cooperation with MCS Group and M Bank's management.
KakaoBank's potential benefits combine an investment in a growing local bank with opportunities to put its technology to work abroad. The practical measures of progress will include the products introduced, the credit models used in lending and the performance of the resulting loans.
Central Asia is the next area the partners intend to explore together. KakaoBank wants to use the Mongolian relationship to identify further opportunities and connect its overseas partners into a broader digital banking network.
Yun Ho-young, KakaoBank's chief executive, set out the international ambition behind the agreement:
Through this strategic partnership, we will expand our global business and combine our digital finance capabilities to develop new business models in international markets.
M Bank offers KakaoBank an established customer base and a partner with businesses spanning finance, telecommunications and retail. Turning that combination into useful lending decisions and convenient services is the immediate task behind the wider regional ambition.
Key Points
- KakaoBank's 15 percent investment makes it M Bank's second largest shareholder.
- The investment amount was not disclosed.
- M Bank has about 700,000 customers, equivalent to roughly 20 percent of Mongolia's population.
- The partners plan credit assessment models using financial, telecommunications and retail information.
- Cooperation also covers new financial products, mobile app design and risk management.
- Mongolia is KakaoBank's third overseas banking partnership after Indonesia and Thailand.
- The companies intend to explore further opportunities in Central Asia.