A smaller deposit, with proposals due next year
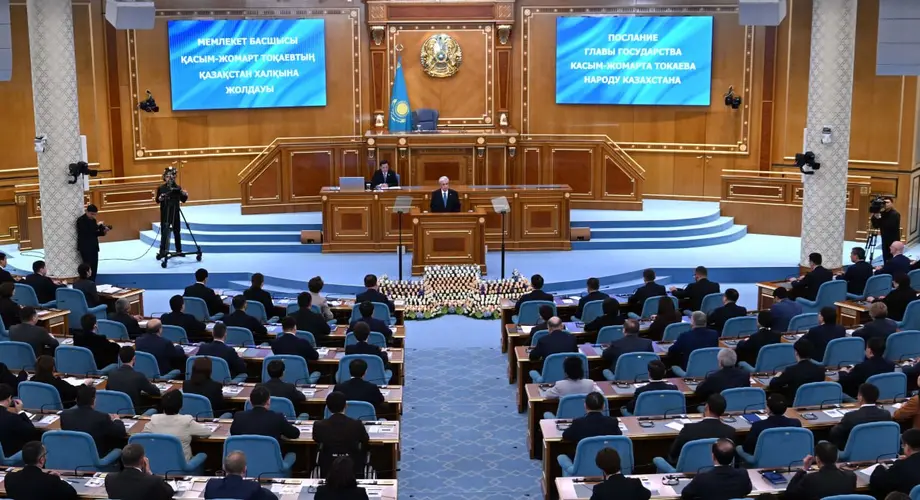
Kazakhstan is developing a mortgage financing mechanism with a down payment of 10%, with proposals expected to be presented in 2027. Bakytzhan Zhunisbekov, chairman of the Ministry of Industry and Construction's Committee for Construction and Housing and Communal Services, outlined the work at a government briefing on November 17, 2026.
Contents
- A smaller deposit, with proposals due next year
- What has changed since the prime minister's instruction?
- Why involve banks beyond Otbasy?
- Some borrowers already qualify for 10%
- Umay applications show the pressure on limited funding
- How much could buyers save upfront?
- A smaller deposit means a larger loan
- Saving takes years while prices keep moving
- Builders face weak sales and uncertainty over supply
- Key Points
The ministry is preparing the financial model with Otbasy Bank, while also considering participation by other banks and the Kazakhstan Housing Company. The proposal would address one of the biggest barriers to buying a home: collecting several million tenge before a bank provides the rest of the purchase money.
A buyer purchasing a home for 30 million tenge would need 3 million tenge at a 10% deposit, compared with 6 million tenge at 20%. The smaller initial payment would leave more of the purchase to be financed through borrowing.
Zhunisbekov said the ministry and Otbasy Bank were developing the financial model and gave an approximate timetable for presenting it:
We will announce these new mechanisms approximately in 2027.
Final interest rates, eligibility rules, funding arrangements and the opening date for applications have not been announced. For households planning a purchase, existing mortgage conditions continue to determine how much they must save.
What has changed since the prime minister's instruction?
Prime Minister Olzhas Bektenov previously asked the Agency for Regulation and Development of the Financial Market and the Ministry of Industry and Construction to prepare proposals for reducing down payments under housing programs. The October mortgage proposal set the policy direction without specifying a replacement deposit percentage.
The November briefing adds two concrete details: a target of 10% and an approximate year for presenting the new mechanism. Zhunisbekov also described an approach involving the raising of borrowed funds on market terms, giving a clearer picture of the financing work now under discussion.
The ministry subsequently clarified that participation was envisaged for banks beyond Otbasy Bank. In his more detailed comments, Zhunisbekov referred to commercial banks that have housing savings instruments. The eventual scope will therefore depend on the financial model and the institutions able to use it.
The main developments leading to the announcement were:
- August 31, 2026: Applications for the first Umay funding allocation closed on the opening day after a tranche of 9 billion tenge was exhausted.
- October 13 and 14, 2026: The prime minister's instruction to prepare proposals for smaller housing deposits was publicized.
- November 3, 2026: A further Umay application round attracted 850 applications totaling 20 billion tenge in one day.
- November 17, 2026: Zhunisbekov outlined the proposed 10% mechanism and the approximate 2027 announcement timetable.
- 2027: Officials expect to present the new financing proposals.
Why involve banks beyond Otbasy?
Otbasy Bank is central to the design work because its business is built around housing savings and loans. Customers accumulate money before borrowing, with the savings history and product rules helping determine access to financing.
Zhunisbekov said the mechanism could also operate through the Kazakhstan Housing Company. He described the possible involvement of other banks with housing savings tools, rather than limiting delivery to a single institution.
Raising money on market terms means obtaining funding from financial markets or other lenders, rather than relying entirely on a direct budget allocation. That funding has a cost, which must be reflected somewhere in the mortgage model, whether through the borrower's interest rate, public support or other financing arrangements.
Kazakhstan's reliance on subsidized mortgages helps explain why the funding structure matters. Preferential programs accounted for 74% of new mortgage lending in 2025, according to the Association of Financiers of Kazakhstan. Otbasy Bank held 58.3% of outstanding mortgages at the start of 2026, according to the Kazakhstan Sustainability Fund's mortgage market report.
Some borrowers already qualify for 10%
Kazakhstan already has housing programs requiring deposits of 10%. Zhunisbekov specifically identified 2-10-20 and 5-10-25 when explaining how the planned mechanism would sit alongside existing assistance.
Some preferential housing loans carry annual interest rates of 2% or 5% for eligible categories of borrowers. Certain programs also allow a housing certificate to cover part of the deposit. Such a certificate provides financial assistance toward the amount a household must contribute itself.
Other products require more savings. The 7-20-25 program requires 20%, while Nauryz generally starts at 20% of the loan amount, with a 10% option for newly built homes with completed interior finishing. Under the Own Home program, the deposit ranges from 20% to 50% of the property price, depending on the loan and accumulated savings.
Otbasy Bank's standard housing loan follows a different savings model. Customers must accumulate at least 50% of the home's value, save for at least three years and reach an assessment indicator of at least 16. That indicator is the bank's measure used to assess a customer's savings record. Annual interest rates for this loan range from 3.5% to 5%.
The practical issue is therefore which households will gain access to the new financing route. A 10% deposit already exists for some buyers, while others face a requirement of 20% or a much larger savings target under the standard Otbasy model.
Umay applications show the pressure on limited funding
Umay, a mortgage program for women, provided the immediate backdrop to questions at the government briefing. Its application rounds attracted more demand than their funding limits could accommodate.
On August 31, the bank stopped accepting applications on the opening day after the first tranche of 9 billion tenge was exhausted. That allocation was taken up within seven hours. On November 3, another round drew 850 applications totaling 20 billion tenge, and intake again stopped after the limit was reached.
Queues formed outside an Otbasy Bank branch in Almaty when applications resumed in early November. The program currently requires a minimum deposit of 20% in Astana and Almaty and 15% in other cities, with a maximum loan of 50 million tenge.
Plans call for raising 90 billion tenge for Umay and Green Mortgage through cooperation with the Asian Development Bank. That planned total covers both programs, whereas the 9 billion tenge figure relates to Umay's first allocation.
Vice Minister of Industry and Construction Olzhas Saparbekov said expanding access depended on additional financing. He linked the work to the resources available from the budget, the market and participating institutions.
With additional financing, we are ready to expand them to reduce excessive demand.
The repeated closures show why deposit requirements and funding availability have to be considered together. A household may collect the required savings yet still need to wait for a program to reopen or secure an allocation.
How much could buyers save upfront?
October 2026 housing prices show the scale of the savings challenge. According to Bureau of National Statistics figures, a square meter of new housing averaged 629,500 tenge nationally, while existing homes averaged 639,000 tenge.
Almaty and Astana were substantially more expensive. Existing apartments averaged 756,300 tenge per square meter in Almaty and 742,700 tenge in Astana. At those averages, an apartment measuring 65 square meters would cost about 49.2 million tenge and 48.3 million tenge respectively.
A 20% deposit would be roughly 9.8 million tenge in Almaty and 9.7 million tenge in Astana. Applying 10% to the same purchase prices would bring the initial contribution down to about 4.9 million tenge and 4.8 million tenge.
Kyzylorda's average price for existing homes was 346,300 tenge per square meter. An apartment of the same size would cost about 22.5 million tenge, requiring approximately 4.5 million tenge at 20%, or 2.25 million tenge at 10%.
These calculations use city averages and a deposit expressed as a share of the purchase price. Individual apartments vary by location, condition and building, while particular programs may define their deposit requirements differently.
A smaller deposit means a larger loan
A household buying a home for 20 million tenge illustrates the tradeoff. With a 20% deposit, it contributes 4 million tenge and borrows 16 million. At 10%, it contributes 2 million and borrows 18 million.
The initial savings requirement falls by half, while the loan grows by 2 million tenge, or 12.5%. If the interest rate and repayment period stay the same, the monthly payment rises in proportion to the larger loan.
Real estate specialist Marzhan Bakhyt cited commercial mortgage rates reaching 21.7% as a major constraint on purchasing power. She gave an example of a home costing 20 million tenge, a deposit of 4 million and payments of about 300,000 tenge a month over 15 years.
For buyers, the interest rate and monthly repayment are therefore as consequential as the deposit. A household that can save enough to enter a program still needs income sufficient to service the mortgage and meet everyday expenses.
The scale of unmet need is substantial: more than 846,000 people were waiting for housing from the state housing stock. Their circumstances and eligibility vary, making the eventual participation rules central to who benefits.
Saving takes years while prices keep moving
A target of 10 million tenge requires monthly savings of about 278,000 tenge over three years, or 167,000 tenge over five years, without interest. Those amounts help explain why a smaller deposit could shorten the wait for a purchase.
A savings model using an effective annual deposit return of 15% reduces the required monthly contribution to about 225,000 tenge over three years or 116,000 tenge over five years. The model assumes regular deposits, no withdrawals and interest remaining in the account.
Bank rates can change when deposits are renewed, and apartment prices can move during the savings period. Bureau of National Statistics figures show that new housing prices rose 10.4% in the year to October 2026, while existing housing rose 7.1%.
A household's savings target therefore depends on both the deposit percentage and the eventual purchase price. A lower percentage can reduce the amount needed at the start, while rising prices increase the tenge amount represented by that percentage.
Builders face weak sales and uncertainty over supply
Kazakhstan's housing market was slowing even as applicants competed for preferential mortgages. September recorded 35,406 home purchase transactions, down 14.3% from a year earlier. Sales of newly built housing had fallen by approximately 40% during the year.
Real estate agency head Galym Iskakov said developers were offering discounts reaching 30%. Vyacheslav Lazarev, vice president of the Union of Builders of Kazakhstan, pointed to a different pressure: notifications of the start of construction had fallen almost by half.
Lazarev linked fewer new projects to the new Tax Code and said developers were completing projects begun in 2024 and 2025. He forecast that tighter supply could push housing prices up by at least 15% in the second quarter of 2027.
His forecast concerns a possible future shortage, while current discounts reflect developers competing for buyers now. Both matter to the mortgage proposal: financing can help households purchase available apartments, but a rise in borrowing demand can also put pressure on prices if fewer homes are completed.
The government's next concrete step is the expected presentation of the financing mechanism in 2027. Its value to buyers will depend on the combination of deposit size, borrowing cost, eligibility and the amount of money available for lending.
Key Points
- Kazakhstan is developing a mortgage financing mechanism with a 10% down payment, with proposals expected in 2027.
- The Ministry of Industry and Construction is working with Otbasy Bank and considering other participating financial institutions.
- Some existing housing programs already allow deposits of 10%, while others require 20% or more.
- Umay application rounds exhausted limited funding quickly, highlighting demand for preferential mortgages.
- Moving from a 20% deposit to 10% halves the initial contribution but increases the amount borrowed.
- Interest rates, eligibility rules and an application opening date for the new mechanism are still to be announced.