More lending room amid pressure on the rupiah
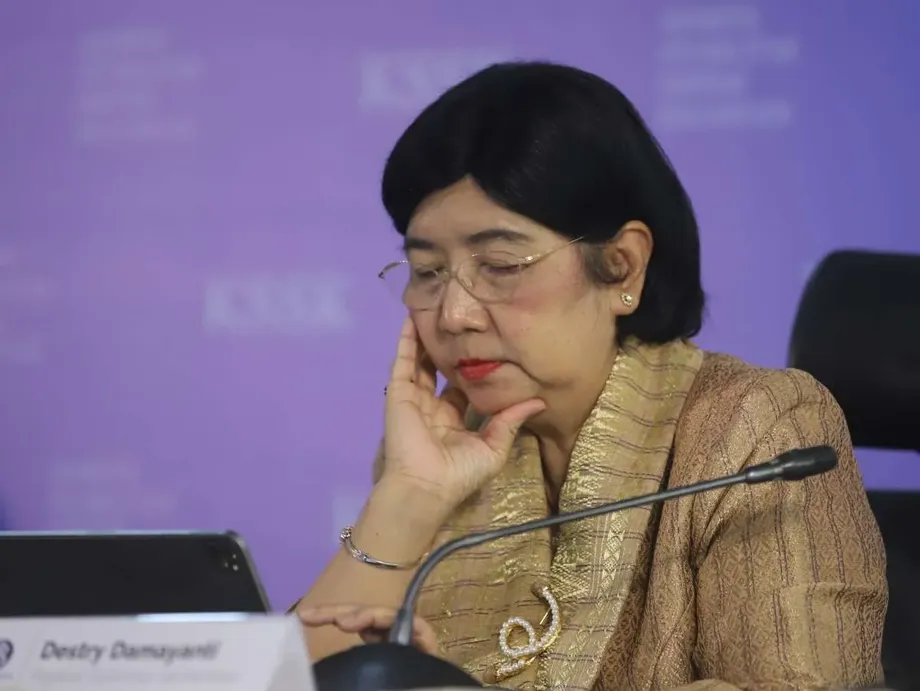
Bank Indonesia will lower reserve requirements for conventional and Islamic banks by two percentage points in November and December 2026, a move Governor Destry Damayanti said would release about Rp190 trillion into the banking system. The decision comes as lending grows faster than deposits and banks face renewed pressure after a sharp stock market selloff.
Contents
- More lending room amid pressure on the rupiah
- How the reserve cuts will work
- Why banks are feeling the squeeze
- Islamic and regional banks see immediate uses
- Liquidity incentives are being reduced and redirected
- Why BI raised one rate while releasing funds
- Currency support extends beyond interest rates
- Other safeguards remain in place
- Housing, vehicles and payments also feature
- Key Points
Announced in Jakarta on October 21 after the Board of Governors met on October 20 and 21, the changes will reduce conventional banks' reserve requirement from 9% to 7%. Islamic banks and Islamic business units will see their requirement fall from 7.5% to 5.5%. Both reductions will take place in two equal stages.
BI paired the release of bank funds with a different move on interest rates: it raised its overnight deposit facility rate by 0.25 percentage points to 5%, while holding its benchmark BI Rate at 5.75% and its overnight lending rate at 6.50%. The combination aims to give banks more room to finance businesses while keeping money market conditions supportive of the rupiah.
September figures help explain the urgency. Bank credit increased 13.26% from a year earlier, compared with deposit growth of 8.22%. Lending was therefore growing 5.04 percentage points faster than the funds banks were collecting from depositors.
Bank leaders welcomed the reserve cuts, although their descriptions of the problem varied. Some said liquidity was tight; others said funds were available but expensive. For borrowers, the practical issue is whether additional room on bank balance sheets leads to accessible loans at affordable rates.
How the reserve cuts will work
The reserve requirement, known in Indonesia as Giro Wajib Minimum, or GWM, determines how much banks must hold in accounts at Bank Indonesia. Lowering it reduces the amount tied up at the central bank, giving banks more flexibility to manage payments, make loans or invest.
The announced schedule is:
- October 21, 2026: BI announced the changes following its October policy meeting.
- November 1, 2026: Conventional banks' GWM falls from 9% to 8%; Islamic banks and Islamic business units move from 7.5% to 6.5%.
- December 1, 2026: Conventional banks' GWM falls to 7%; Islamic banks and Islamic business units move to 5.5%. Changes to liquidity incentives and reserve remuneration also take effect.
Each banking category receives a cut of two percentage points. Put simply, before adjustments for applicable incentives, a two percentage point reduction means Rp2 less in required reserves for every Rp100 in the relevant deposit base. BI estimates the resulting additional liquidity at about Rp190 trillion.
Why banks are feeling the squeeze
Hendra Lembong, deputy chairman of the Indonesian Banks Association, Perbanas, and president director of Bank Central Asia, described banking liquidity as somewhat tight and said the BI measure would help. Lani Darmawan, another Perbanas deputy chair and president director of CIMB Niaga, said liquidity was available but funding costs were high.
Those comments describe two connected pressures. A bank needs enough accessible funds to meet withdrawals and finance loans. It also needs to obtain those funds at a cost that leaves lending commercially viable. Competition for deposits can push up what banks pay savers, making it harder to lower loan rates.
BI's figures show that the banking system's liquid assets relative to deposits increased from 23.04% in August to 24.08% in September, a rise of 1.04 percentage points. At the same time, credit was expanding much faster than deposits. The combination helps explain why a stronger aggregate liquidity measure can coexist with complaints about expensive funding and uneven access to money.
Hery Gunardi, Perbanas chairman and president director of Bank Rakyat Indonesia, said the reserve reduction could increase lending and improve the loan to deposit ratio. That ratio compares loans outstanding with deposits and helps banks assess how much of their deposit funding has been committed to lending.
Islamic and regional banks see immediate uses
Koko Tjatur Rachmadi, secretary general of the Indonesian Islamic Banks Association, Asbisindo, and president director of Bank Aladin Syariah, described liquidity as very tight following the previous Friday's stock market shock. He welcomed the reduction in Islamic banks' GWM and called for further measures to improve liquidity and business conditions.
Koko also pointed to the timing. Banks usually compete for deposits in the final quarter, he said, and the market disruption had added to that pressure. For Islamic banks and Islamic business units, the November and December reductions will arrive during that period of competition for funds.
Agus Haryoto Widodo, chairman of the regional development banks association, Asbanda, and president director of Bank Jakarta, said the additional flexibility could support regional lending. He identified micro, small and medium enterprises, business working capital and productive sectors that create jobs as priorities.
Working capital pays for everyday business needs such as stock, materials and wages. For regional lenders, more flexible funding could make it easier to meet those needs. Agus said success should be measured by wider access to sound financing and tangible benefits for businesses and communities.
Liquidity incentives are being reduced and redirected
Alongside the GWM reduction, BI will lower the maximum Macroprudential Liquidity Policy Incentive, known as KLM, from 6% to 5%, effective December 1. This mechanism gives banks reserve relief linked to qualifying lending and money market activity.
The financing component will fall from a maximum of 4% to 3% of third party funds, the banking term for customer deposits. Its scope will include further support for sectors that create jobs. The money market deepening component will remain capped at 2%, with the aim of encouraging funds to move between banks and reach lending institutions that need them.
Through the first week of October, banks had received Rp458.5 trillion in KLM incentives. Financing accounted for Rp336.4 trillion, while money market deepening accounted for Rp122.1 trillion. Those figures show that the incentive programme was already a substantial part of BI's support for banking liquidity before the new reserve cuts.
Deputy Governor Solikin M. Juhro said BI could adjust sector incentives as conditions changed, shifting support when previously assisted sectors improved. He said the broader GWM reduction would provide additional liquidity alongside the smaller financing incentive.
BI also set a cap on the portion of average rupiah reserve fulfilment that receives remuneration, meaning a return paid by the central bank. From December 1, that remunerated portion will be capped at 5% of average rupiah GWM. The amount of the Rp190 trillion release reaching individual banks will depend on their deposit bases and applicable incentive positions.
Why BI raised one rate while releasing funds
BI's decision separates the availability of bank funds from the interest rates guiding short term markets. Lower reserves give banks more room to use their money. A higher deposit facility rate increases the return banks receive when they place funds overnight at the central bank, helping support short term market rates.
Solikin, explaining the approach, said BI was responding to several pressures at once:
"Because we are addressing multiple challenges, we need to address them with different policies," BI Deputy Governor Solikin M. Juhro said.
Irman Faiz, an economist at Bank Danamon in Jakarta, said the deposit facility increase could help prevent the reserve cut from pushing money market rates too low. Maintaining those rates can help preserve the attraction of holding rupiah assets.
Gareth Leather, senior Asia economist at Capital Economics, questioned whether BI could successfully support both the currency and economic growth. He expressed his concern in these terms:
"I think they are trying to do two things at once (support the rupiah and boost growth), which I am not sure is possible," Leather said.
Destry said earlier rate increases totalling one percentage point, delivered between May and June, were sufficient to anchor inflation. BI continues to target inflation of 2.5%, plus or minus one percentage point, in 2026 and 2027. The October decision follows her defence of rate autonomy amid concern about political influence over monetary policy.
Currency support extends beyond interest rates
BI recorded the rupiah at Rp17,985 per US dollar on October 20, down 0.61% from the end of September. The currency remained under pressure after the October 16 market selloff, when it weakened beyond Rp18,000 per dollar and Indonesian shares suffered steep losses.
The market disruption followed an MSCI warning about potentially moving Indonesian equities from Emerging Market to Standalone Market status. The consultation is scheduled to close on April 30, 2027, with a final classification decision due by June 30, 2027.
BI is continuing currency intervention through offshore non-deliverable forwards, domestic non-deliverable forwards and spot transactions. Spot transactions exchange currencies at current market prices. Non-deliverable forwards allow participants to manage future exchange rate exposure through contracts settled on the difference between agreed and prevailing rates.
BI is also increasing discounts on the cost of domestic non-deliverable forward hedging. The discount for contracts lasting six months rises from 25% to 40%, while the discount for contracts lasting 12 months rises from 30% to 45%. Each increases by 15 percentage points.
The incentives cover qualifying foreign portfolio investment, overseas borrowing by banks and foreign direct investment. Destry said hedging incentives introduced in June had attracted $9.9 billion in capital inflows by October 20. Cheaper hedging reduces the cost of protecting an investment against currency movements, making rupiah assets more attractive to investors concerned about exchange rate losses.
Other safeguards remain in place
BI kept several banking safeguards unchanged while loosening reserve requirements. The Macroprudential Intermediation Ratio remains at 84% to 94%, and banks' foreign funding ratio remains capped at 40% of bank capital. The countercyclical capital buffer stays at 0%.
The Macroprudential Liquidity Buffer remains at 4%, with repo flexibility of 4%. For Islamic banks, the corresponding figures remain 2.5% and 2.5%. Repo flexibility allows eligible securities held as liquidity buffers to be used to obtain temporary funding through repurchase transactions.
August banking data showed a capital adequacy ratio of 24.10%. Capital acts as a financial cushion against losses. Gross nonperforming loans stood at 2.11%, while the net ratio was 0.84%, providing another measure of the banking system's condition as BI sought to support further lending.
BI also said it would strengthen implementation of its Inclusive Macroprudential Financing Ratio policy. Taken together, the measures seek to expand financing while retaining requirements covering capital, liquidity and banks' funding structure.
Housing, vehicles and payments also feature
BI extended rules permitting property financing of up to 100% of collateral value and minimum down payments of 0% for new motor vehicles throughout 2027. Both measures had been scheduled to expire on December 31, 2026; they will now run from January 1 through December 31, 2027.
The property measure covers landed homes, apartments, shop houses and office houses. Eligibility depends on banks meeting specified criteria, including conditions relating to problem loans or financing. A bank's lending assessment will determine the financing offered to an individual borrower.
For households, a smaller down payment reduces the cash needed at purchase, while a larger financed amount increases the debt to be repaid. The extension gives eligible lenders room to offer such financing during the same period that BI is seeking more credit for businesses and employment.
BI also plans trials of QRIS payments across borders with Hong Kong and Timor Leste in the fourth quarter of 2026. QRIS is Indonesia's standard for QR code payments. The trials form the payments component of a broader package combining currency management, bank funding and support for economic activity.
Key Points
- Conventional banks' reserve requirement falls from 9% to 7% in two stages on November 1 and December 1, 2026.
- Islamic banks and Islamic business units receive an equivalent reduction, from 7.5% to 5.5%.
- Governor Destry Damayanti estimates the reserve cuts will add about Rp190 trillion in banking liquidity.
- The maximum KLM incentive falls from 6% to 5% on December 1, with financing support capped at 3% and money market incentives at 2%.
- BI held its benchmark rate at 5.75% and raised its overnight deposit facility rate to 5%.
- September lending growth of 13.26% exceeded deposit growth of 8.22%, keeping attention on funding availability and cost.
- Currency hedging incentives and the extension of eligible property and vehicle financing rules accompany the reserve cuts.