Coal cancellations grow, but industrial plants keep advancing
China has cancelled 59.3 gigawatts of coal power projects overseas since President Xi Jinping announced an end to new overseas coal projects in September 2021. Researchers estimate that those cancellations will avoid about 6.1 billion tons of carbon dioxide over the planned lifetimes of the plants. Yet 14 projects remain under construction abroad, with a combined capacity of about 12.1 gigawatts.
Contents
- Coal cancellations grow, but industrial plants keep advancing
- What Xi's 2021 pledge changed
- Why captive coal remains a gap
- Where the remaining projects are concentrated
- China's domestic coal construction and falling coal share
- Clean energy finance has changed direction, but remains limited
- How cleaner electricity could reach industrial users
- Coal trade and growing economies complicate the transition
- China's climate promises and the next five years
- Quick Facts
As of November 10, 2025, the central tension is between a shrinking coal pipeline and the continued construction of plants serving industrial facilities. Many of these projects supply mines, metal smelters or industrial parks directly, operating outside national electricity grids. Private Chinese companies are often behind them, leaving a gap in the application of China's pledge.
By July 2025, the capacity of Chinese backed overseas coal projects still in planning had fallen to 31.4 gigawatts, roughly 37 percent below the 2024 level. Meanwhile, operating capacity increased by 4.1 gigawatts in 2025 as plants already under construction reached completion. A gigawatt measures generating capacity: it describes how much power a plant can supply, rather than how much electricity it produces over a year.
China's retreat from many overseas coal projects is happening alongside rapid expansion in wind, solar, batteries and electricity storage. China is the largest builder and exporter of solar panels, wind turbines and lithium batteries, and its factories help set prices across much of the clean energy supply chain. The country accounts for more than 30 percent of annual carbon emissions, compared with about 12 percent for the United States.
Chinese investment decisions therefore matter well beyond China's borders. They affect whether growing industrial economies meet new electricity demand through coal plants that can operate for decades or through cleaner generation supported by stronger grids and storage.
What Xi's 2021 pledge changed
Xi Jinping's September 2021 announcement promised an end to Chinese support for new coal power projects overseas and increased support for clean energy abroad. The commitment was followed by a visible decline in new coal deals backed by the Chinese state. Databases tracking Chinese development finance and foreign direct investment show no new coal funding commitments after 2021.
Most Chinese state lenders, contractors and large enterprises owned by the state have moved toward wind, solar, hydropower and electricity grid projects in developing markets. The cancellation figures show the scale of the change: 59.3 gigawatts of abandoned coal capacity represents a substantial reduction in plants that would otherwise have produced emissions throughout their operating lives.
The pledge did not spell out how privately financed coal plants serving individual industrial facilities would be treated. It also did not establish an enforcement body to oversee the boundary between projects supplying national grids and those supplying industry directly.
Private projects can be financed through company equity, commercial bank loans and partnerships with local businesses. Equity is money invested by a project's owners. Such arrangements can move forward without a prominent loan from a Chinese policy bank, allowing industrial power projects to follow a different route from large public electricity schemes.
Researchers tracking China's overseas coal projects say cancellation becomes uncommon once construction begins. This helps explain why operating capacity can rise while the planning pipeline contracts: older projects finish even as proposed projects are abandoned.
The main dates and developments show how that transition has unfolded:
- September 2021: Xi announced an end to support for new overseas coal power projects and greater support for clean energy abroad.
- 2022 and 2023: Wind and solar accounted for more than two thirds of new capacity funded through Chinese overseas finance and investment channels.
- 2024: Chinese companies installed about 24 gigawatts of power capacity in Belt and Road countries, with more than half coming from renewables.
- July 2025: Planned overseas coal capacity stood at 31.4 gigawatts, roughly 37 percent below the previous year's level.
- 2025: Completed projects added 4.1 gigawatts to operating overseas coal capacity, while 14 projects totaling about 12.1 gigawatts remained under construction.
Why captive coal remains a gap
Captive power is electricity generated for a particular industrial operation rather than for a national grid. A nickel smelter, copper mine, cement production line or integrated steel facility may build its own coal plant to secure the power it needs.
Private Chinese companies operating mines, metal processing facilities and industrial parks commonly own these plants. Their projects tend to appear where industrial electricity demand is growing quickly and grid supplies are limited, unreliable or expensive. Long waits for transmission permits can also make a dedicated plant attractive to an industrial owner.
Plants embedded in industrial sites can claim that they do not sell electricity to a grid. With no explicit treatment of privately financed captive generation in the 2021 pledge, these projects have continued to advance. Researchers tracking them warn that this gap weakens the promise to end overseas coal investment.
This loophole casts a growing shadow over the progress made in ending Chinas overseas coal investments.
Researchers estimate that China's existing captive coal projects abroad have added about 1.5 billion tons of carbon dioxide emissions over their lifetimes. That is roughly half the estimated lifetime emissions from all Chinese backed coal power currently operating overseas. Projects now under construction could add another 3.4 billion tons over their lifetimes.
Lifetime emissions estimates describe the accumulated pollution expected during years of operation, rather than emissions released in a single year. Industrial coal plants can run for decades, and their size is usually matched to manufacturing or mineral processing that needs large amounts of energy.
Project sponsors argue that factories need reliable electricity around the clock and that grid improvements arrive too slowly. Researchers tracking the projects want clearer rules on what is allowed, who approves it and which alternatives must be examined before industrial coal plants receive approval.
Where the remaining projects are concentrated
Indonesia, India, Laos, Zimbabwe and Zambia have become prominent locations for Chinese backed captive coal projects. These are economies with growing industrial demand or mineral resources that require substantial electricity for extraction and processing.
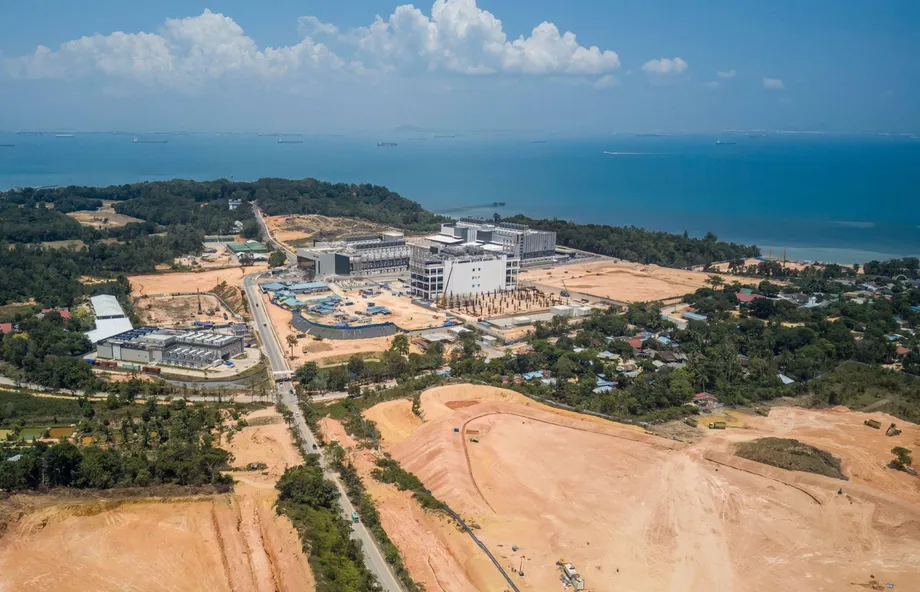
Indonesia illustrates the connection between coal power and the materials used in cleaner technologies. Chinese firms are involved in several gigawatts of coal generation serving nickel processing, an important part of the global battery supply chain. Industrial parks on Sulawesi and elsewhere use dedicated plants to power nickel and other metal smelters.
The other countries show similar links between industrial expansion and dedicated electricity supplies:
- India: Some industrial projects with Chinese investment use captive coal to maintain stable electricity for heavy manufacturing.
- Laos: Industrial parks and mining projects use captive power alongside the country's large hydropower exports to neighboring countries.
- Zimbabwe: Coal additions support mining and metal processing while expansion of the national grid proceeds slowly.
- Zambia: Mining and mineral processing require dedicated electricity supplies where grid capacity remains constrained.
Project promoters often describe coal plants as temporary steps toward cleaner fuels. Whether that transition happens depends on contracts and plant design. Firm retirement schedules and provisions for adding renewable electricity would give industrial owners a defined route away from coal.
Without those provisions, plants built to support today's industrial growth can continue producing emissions well beyond the 2030s. Their owners will already have invested in coal equipment and fuel arrangements, making the choice of power supply at the start of a project consequential for many years.
China's domestic coal construction and falling coal share
Inside China, developers began construction of roughly 95 gigawatts of coal power in 2024, the highest annual figure since the middle of the previous decade. At the same time, coal's share of electricity generation fell to about 51 percent in the first half of 2025, its lowest recorded level, as wind, solar and storage expanded.
Power shortages in 2020 and 2022 strengthened concerns about energy security. Local governments in several provinces approved new coal plants as insurance against future shortages. Rigid rules governing which plants generate electricity and slow reforms to power trading between provinces also contributed to the construction push.
Many Chinese coal units still operate for around half their potential hours. More generating equipment can therefore coexist with a smaller coal share if wind and solar produce more electricity and coal plants spend more time waiting to supply power when needed.
Batteries, pumped hydropower and improved electricity market rules have already helped China meet summer demand peaks without widespread blackouts. Pumped hydropower stores energy by moving water uphill when electricity is available, then releasing it through turbines when demand rises.
Xi has presented the development of new energy as a foundation for energy security. In that approach, renewables, storage and flexible electricity use improve reliability, while coal moves toward a supporting role rather than providing a constant basic supply.
Clean energy can cover new demand even while additional coal capacity connects to the grid. In recent periods, Chinese coal generation has been flat or declining despite the arrival of some new plants. For overseas industrial markets, China's experience points to the value of transmission investment, regional electricity trade and storage as alternatives to building more coal capacity.
Clean energy finance has changed direction, but remains limited
Wind and solar accounted for more than two thirds of new electricity capacity funded by Chinese financiers and investors overseas in 2022 and 2023. That marked a sharp change from the previous two decades, reflecting both policy decisions and the competitive position of Chinese clean energy manufacturers.
Solar modules, inverters and batteries have become much cheaper. An inverter converts the electricity produced by solar panels into a form that electrical equipment and grids can use. Chinese companies dominate these supply chains, giving overseas developers access to equipment that can make renewable projects more affordable.
The amount of finance remains small compared with earlier investment peaks. Chinese overseas finance channels funded only about 3 gigawatts of wind and solar capacity across 2022 and 2023, far below annual levels during the busiest years of the Belt and Road Initiative. Commercial construction contracts and private investment have filled part of the gap.
Chinese companies nevertheless had a record year for building power projects in Belt and Road countries in 2024, installing about 24 gigawatts. More than half was renewable capacity, led by solar and hydropower. Thermal generation, including coal projects already in progress and new gas plants, accounted for the rest.
Coal still makes up a meaningful part of the future project list. Industry analysts expect further cancellations as host countries seek cleaner and cheaper electricity options. The shift depends partly on whether governments and investors can turn proposed renewable projects into investments that lenders consider financially workable.
Asia receives most Chinese overseas power investment and hosts most of the coal projects. The Americas and parts of Africa receive more hydropower investment, with smaller shares going to wind and solar. Africa remains poorly served by clean energy finance from all sources, although Beijing has promised new support that includes dozens of projects producing less carbon.
Feasibility studies, guarantees against financial risks, grid planning and strong environmental and social standards are needed to turn those promises into projects ready for construction. Lower equipment prices help, but they do not remove the need to arrange land, financing and an electricity connection.
How cleaner electricity could reach industrial users
Industrial owners need dependable electricity at predictable prices. In many locations, renewables combined with storage, management of electricity demand and a grid connection could already replace a substantial share of coal use.
Managing demand means adjusting when some equipment runs so that electricity use better matches supply. Storage can save electricity for later use, while a grid connection can allow a factory to draw from more than one source. Together, these measures can reduce dependence on a single coal plant.
Project preparation, land access, transmission and electricity market rules often limit these alternatives more than the technology itself. A renewable plant cannot serve a distant industrial park without suitable transmission, and investors need contracts that give them confidence about future payments.
Researchers tracking China's overseas energy portfolio propose several changes to bring industrial projects into line with the 2021 pledge:
- State explicitly that captive coal falls under the overseas coal ban, whatever the ownership structure or grid connection.
- Require serious assessment of renewable and hybrid alternatives, including storage and management of electricity demand, before approving coal plants.
- Require the best available technology, strict environmental standards and retirement plans with deadlines for plants already under construction.
- Move finance backed by the state toward solar, wind, hydropower, storage and grid modernization in priority markets.
- Help host countries prepare projects, acquire land, secure transmission access and reform electricity markets so industrial users can buy clean power at stable prices.
- Assign an agency to enforce the pledge, coordinate ministries and intervene when projects breach rules or operate irresponsibly.
These proposals aim to increase cancellations where workable alternatives exist and improve the economics of clean power where electricity demand is rising quickly. The rules governing private captive plants and the agency responsible for enforcing them have not been settled.
Coal trade and growing economies complicate the transition
Chinese coal exports rose by about 13 percent in the first five months of 2025 as demand at home slowed. Japan, Indonesia and South Korea were among the leading buyers. Inside China, wind and solar supplied more than a quarter of electricity in some months, contributing to softer coal prices and lower imports during a period that usually involves stockpiling.
Some rapidly growing economies within or alongside the BRICS bloc are adding coal capacity much faster than solar and wind capacity. Analysts warn that new coal, gas and oil projects in these markets can create lasting dependence on high emissions and absorb investment that could otherwise support cleaner electricity.
Chinese firms and enterprises owned by the state are involved in a large share of generation projects under construction in these countries. Their choices therefore affect both the immediate supply of power and the options available when industrial demand increases further.
Clearer captive coal rules, stronger electricity market reforms and more blended finance could shift that balance. Blended finance combines different kinds of funding to make projects easier to finance. Market reforms that reward flexible generation and the use of clean electricity could also make renewable projects more attractive to industrial buyers.
The remaining 12.1 gigawatts under construction abroad are likely to be completed because cancellation becomes rare after work starts. Early retirement provisions or plans to switch fuels would be needed to limit emissions that could otherwise continue for decades.
China's climate promises and the next five years
Guo Jiakun, a spokesperson for China's Foreign Ministry, addressed the country's approach to climate action and its timetable in February. He said China remained committed to its goals for reaching a carbon emissions peak and carbon neutrality.
China has always been a doer in climate response and is firmly committed to green and low-carbon development. We will continue our effort of honoring the pledged goals on carbon peak and carbon neutrality in our own way and at our own speed.
A carbon peak is the point after which emissions begin to fall. Carbon neutrality means balancing remaining emissions with the removal of carbon from the atmosphere. Expert surveys point to a possible peak in China's fossil fuel use around 2028 and cautious confidence about meeting its 2030 emissions target.
China's central government is signaling greater attention to grid flexibility, storage and electricity market reform. Extending that approach to overseas projects, while closing the captive coal gap, could reduce the remaining coal pipeline and accelerate clean energy investment.
Clean power is often the cheapest new source of electricity, and battery storage costs continue to fall. Countries combining rapid renewable construction with practical grid upgrades can reduce coal dependence while maintaining reliable electricity and industrial growth.
The next five years will involve two changes happening at once: completion of coal plants already being built and expansion of cleaner technologies. Contract terms, investment choices and enforcement of the overseas pledge will influence how much industrial electricity shifts from the first to the second.
Quick Facts
- Since 2021, Chinese backed overseas coal cancellations have reached 59.3 gigawatts, avoiding an estimated 6.1 billion tons of lifetime carbon dioxide emissions.
- Planned overseas coal capacity stood at 31.4 gigawatts in July 2025, roughly 37 percent below 2024.
- Operating overseas coal capacity increased by 4.1 gigawatts in 2025 as construction finished on existing projects.
- Fourteen projects totaling about 12.1 gigawatts remain under construction, mostly captive plants serving industry.
- Existing captive projects account for an estimated 1.5 billion tons of lifetime emissions; projects under construction could add another 3.4 billion tons.
- China began building roughly 95 gigawatts of domestic coal capacity in 2024, while coal's generation share fell to about 51 percent in the first half of 2025.
- Wind and solar received more than two thirds of new capacity funded through Chinese overseas finance channels in 2022 and 2023, totaling about 3 gigawatts.
- Chinese companies installed about 24 gigawatts in Belt and Road countries in 2024, with more than half coming from renewables.
- Private captive coal projects remain the central gap in China's commitment to end support for new overseas coal power.