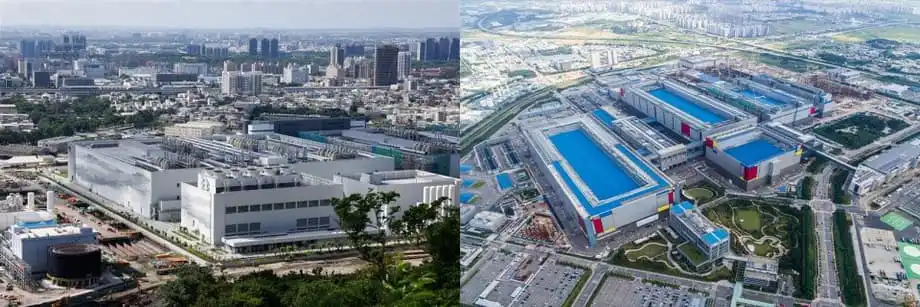
A chip boom with two different outcomes
Taiwan and South Korea are both semiconductor powerhouses, yet the artificial intelligence boom is producing sharply different economic results. As of October 24, 2025, the Asian Development Bank projects Taiwan's economy will grow by about 5.1 percent this year, compared with roughly 0.8 percent for South Korea. The gap is 4.3 percentage points, even as Samsung Electronics and SK hynix recover from a deep downturn in memory chips.
Contents
- A chip boom with two different outcomes
- Why chips have a bigger effect in Taiwan
- Taiwan's advantage in the chips that run AI
- A dense industrial cluster backed by policy
- South Korea's memory recovery has limits
- US demand and tariffs widen the gap
- South Korea's support and the wait for new capacity
- Electricity, water and workers constrain expansion
- Geopolitical risk and factories overseas
- Growth gains meet household pressures
- Different priorities for sustaining growth
- The Bottom Line
August exports illustrate the shift. Taiwan's shipments rose roughly 34 percent from a year earlier to a record near $58.5 billion, edging ahead of South Korea's $58.4 billion. South Korean exports increased just over 1 percent that month. Taiwan's much stronger growth reflects surging orders for semiconductors and electronics used in AI systems.
Forecasts also put Taiwan's gross domestic product per person above $38,000, enough to overtake South Korea for the first time in roughly 22 years. GDP measures the value of goods and services produced in an economy; GDP per person divides that total by the population. South Korea still produces much more in total, although a prolonged stretch of weak growth would narrow the difference.
AI demand is helping companies in both places. Data centers and smartphones need advanced processors to perform calculations and large amounts of memory to hold the information those processors use. The difference is how those gains spread through each economy. Taiwan has a larger concentration of semiconductor activity, while South Korea has a broader industrial base that includes sectors facing slower demand and higher tariffs.
Why chips have a bigger effect in Taiwan
Semiconductors account for an estimated 22 percent of Taiwan's GDP, compared with roughly 10 percent in South Korea. Taiwan's share is therefore more than twice as large. A strong chip cycle has a greater direct effect on Taiwan's total output.
Integrated circuits, the tiny electronic circuits inside chips, also make up about one third of Taiwan's exports, compared with roughly one fifth of South Korea's. Taiwan's trade basket is more closely tied to the products benefiting from the AI investment surge.
South Korea's wider mix of industries spreads its economic activity across more products, but several of those products are under pressure at the same time. Autos, steel and petrochemicals face tariff headwinds or weaker conditions. Energy intensive industries also contend with changing costs and regulations in multiple regions.
Taiwan's concentration magnifies the gains when semiconductor orders rise. The same concentration leaves jobs, investment and exports more exposed to changes in chip demand. The current growth gap comes from that industrial structure, policy choices and trade exposure, as well as the types of chips each economy produces.
Taiwan's advantage in the chips that run AI
Taiwan Semiconductor Manufacturing Company, or TSMC, fabricates the bulk of the most advanced logic chips used by leading American designers of AI processors and smartphones. Logic chips carry out calculations and instructions. A foundry manufactures those chips for customers that design them.
Taiwan holds more than 60 percent of the global market for contract chip manufacturing, according to industry estimates. Its share of the most advanced logic production is near 90 percent or more. Those positions place the island at the center of the fastest growing part of the semiconductor business.
The global AI chip market is projected to expand by around 20 percent a year in the near term, compared with growth closer to the high single digits for semiconductors as a whole. Taiwan's strength in advanced logic allows it to capture a larger share of that faster expansion.
The current AI cycle also rewards advanced packaging and production methods that use power efficiently. Packaging connects and combines chips so they can work together. Advanced packages can place logic processors alongside stacks of high bandwidth memory, allowing large amounts of data to move quickly between them.
South Korea's memory producers benefit from those same systems. Taiwan's advantage is that its foundries and packaging businesses occupy several of the stages receiving particularly strong investment, giving the AI boom a broader reach across its semiconductor economy.
A dense industrial cluster backed by policy
Hsinchu Science Park and the surrounding area bring together chipmaking talent, suppliers, equipment vendors and logistics services. Their proximity helps Taiwan's semiconductor companies reduce costs, improve production yields and get products to customers faster. Yield is the proportion of manufactured chips that work correctly, a crucial measure when production is expensive and technically demanding.
US chip designers depend on this network to meet aggressive launch schedules. Materials, tools, packaging, testing and design support are available within short distances of major fabrication plants, commonly called fabs. Taiwan's advantage rests on that wider network as well as the factories themselves.
Taiwan has strengthened tax credits for research, equipment and talent retention in recent years. It has also set aside billions of dollars through 2033 to keep the most advanced manufacturing capacity and packaging on the island.
During a severe drought, authorities gave chip plants priority access to water to prevent production stoppages. Prioritizing semiconductor operations during dry periods and times of peak electricity demand reflects the government's effort to preserve an industry central to national growth.
Taiwan's chip equipment purchases have exceeded South Korea's in recent quarters, pointing to substantial capacity expansion in advanced logic and valuable packaging operations. That investment supports the export surge, although new plants also add to demands on electricity, water and skilled workers.
South Korea's memory recovery has limits
Samsung Electronics and SK hynix are recovering from a deep memory market downturn. Prices for DRAM and NAND stabilized and then rose as AI training and inference increased demand. DRAM holds data that processors need to access quickly, while NAND provides storage. Training teaches an AI system from data; inference is the process of using that system to produce an answer or perform a task.
SK hynix has benefited from demand for high bandwidth memory used with AI accelerators, the specialized processors that handle AI calculations. Samsung is pursuing new DRAM production technologies and expanding its foundry business for advanced logic chips.
Memory markets tend to move sharply with inventory cycles. When customers have more chips in storage than they need, orders and prices can fall, affecting profits and investment. Orders for advanced logic tied to AI development plans lasting several years can be steadier.
South Korea's chip recovery is also taking place alongside weakness elsewhere. Higher tariffs affect autos, steel and parts in major markets. Changing energy costs and regional regulations add pressure to other manufacturers. Stronger semiconductor profits have therefore provided only a limited lift to the wider economy.
South Korean exports are only modestly higher so far in 2025. Chips and cars have increased, while steel and petroleum shipments have declined. The performance of individual chipmakers and the growth rate of the entire economy reflect different combinations of activity.
US demand and tariffs widen the gap
Taiwan's exports to the United States have surged as cloud computing companies and device manufacturers increase orders for AI semiconductors and electronics. Monthly shipments to the US have risen by more than 60 percent at times this year, helping drive record export totals.
South Korea has faced declines in important categories such as car parts and steel where duties increased. Steel shipments to the US were hit by steep tariffs, while auto shipments softened. Those pressures help explain why August's semiconductor gains coincided with only a small increase in South Korea's total exports.
Many chip products remain largely outside the tightest tariff restrictions because importing economies want to avoid damaging their own technology industries. Traditional industrial products face different treatment. Taiwan's export mix has consequently benefited from strong electronics demand while South Korea's broader mix has encountered more tariff pressure.
Taiwan's expanding trade surplus with the United States reflects the same shift: the island is selling more into the American market than it buys from it. Large bilateral trade imbalances can attract policy attention, although the strategic importance of chips has so far kept many products off new tariff lists.
The main dates and planning horizons show how immediate demand sits alongside investment that takes much longer:
- August 2025: Taiwan's exports reached about $58.5 billion, narrowly exceeding South Korea's $58.4 billion.
- October 24, 2025: The growth outlook stood at about 5.1 percent for Taiwan and 0.8 percent for South Korea.
- Through 2033: Taiwan has set aside billions of dollars to support advanced chip capacity and packaging at home.
- By the 2040s: South Korea plans to build a major cluster of chip capacity and suppliers through substantial public and private investment.
South Korea's support and the wait for new capacity
South Korea has passed a broad support package for semiconductors while extending benefits to other strategic industries in pursuit of more balanced growth. Companies and economists argue that the focus and speed of this support still trail Taiwan's approach.
Debate continues over flexible working arrangements for fabs, exemptions from workweek limits for critical projects, faster permits and simpler incentives for capital spending. Industry executives have asked for flexibility when projects face demanding schedules. Electricity and water infrastructure are also central to decisions about where and when new capacity can operate.
South Korea's planned mega cluster could strengthen manufacturing and supplier networks over the longer term. Its timetable extends into the 2040s because plants, training systems, electricity supplies and reservoir capacity take years to build.
Current tariff pressure on autos and materials arrives much sooner than those investments can deliver their full benefits. Turning the chip recovery into broader growth will depend partly on aligning factory construction with the power, water, workers and local approvals needed to run the plants.
Electricity, water and workers constrain expansion
Taiwan's dense semiconductor network is efficient, but further expansion requires more reliable power and water supplies. Finding suitable locations becomes harder as production moves to increasingly advanced processes. The AI build out requires substantial new electricity generation and grid upgrades.
Both Taiwan and South Korea face deadlines for delivering that infrastructure. Taiwan's decisions to prioritize semiconductor operations during droughts and peak demand periods show how closely resource planning is tied to its industrial strategy.
South Korea is working to secure long term energy and water supplies for its chip clusters. It is also developing training programs to address shortages in process engineering and equipment maintenance, two areas needed to keep factories operating reliably.
Factory investment therefore has several linked requirements. Purchasing manufacturing equipment and constructing buildings must be matched by functioning power lines, substations, water systems and a skilled workforce. Delays in any of those areas can slow the start of production.
Geopolitical risk and factories overseas
Taiwan's dominance in advanced chips creates a major concentration of economic and geopolitical risk. A conflict across the Taiwan Strait would severely disrupt production and supply chains. Economic models of extreme scenarios put global losses from a full scale confrontation toward $10 trillion, with a blockade causing damage measured in trillions of dollars.
The dependence is substantial because Taiwan fabricates the majority of the most advanced logic capacity and its leading foundry holds a dominant share of contract manufacturing. Reproducing the island's efficiency, depth of talent and closely connected suppliers elsewhere is difficult in the near term.
The United States, Europe, Japan and South Korea have introduced subsidies and tax credits to attract fabrication, packaging and materials production. Projects extend from Arizona and New York to Kyushu and Dresden. Bringing production home is often called reshoring; shifting it toward allied locations is commonly called friendshoring.
Taiwanese companies are participating by building some capacity overseas, spreading production across more locations. Costs, labor constraints and the time required to bring factories into operation limit the pace. The most advanced production remains centered on Taiwan, a balance expected to continue for several years.
Growth gains meet household pressures
Taiwan's technology boom has raised wages in information and communications technology and semiconductor businesses faster than pay in other sectors. That uneven growth widens income gaps even while national output rises.
Hsinchu's housing squeeze adds to living costs for workers outside technology. Local evidence points to a mild increase in births among well paid technology families, while affordability problems discourage others from starting families. The benefits of the same industrial boom can therefore vary considerably between households.
Inflation has reduced real wage gains in some periods, meaning that higher pay buys less than the headline increase suggests. Household debt is also high relative to economic output. South Korea faces demographic and affordability pressures of its own, alongside broader living cost problems in major cities.
Taiwan's projected lead in GDP per person sits within this more uneven household picture. Currency movements affect GDP comparisons expressed in dollars, while housing expenses and prices affect how much income families can use. Improving the quality of growth matters alongside adding factories and export sales.
Different priorities for sustaining growth
South Korea can make more use of its chip recovery by addressing construction and production bottlenecks. Faster permits for power lines, substations and water infrastructure would help align services with factory schedules. Stable tax credits for advanced manufacturing processes and packaging could support domestic foundry expansion alongside its established memory strengths.
Training equipment technicians and process engineers could reduce labor shortages that slow the start of production. Flexible work arrangements for critical projects remain an industry request. The mega cluster plan will also need timely energy and water delivery and simpler local approvals.
Beyond chips, support for more valuable autos and batteries, steel made with lower carbon emissions and digital services could spread export risk. Trade diplomacy aimed at reducing tariff friction in autos and materials would help sectors that currently limit the wider economic recovery.
Taiwan's priorities combine protecting its semiconductor lead with broadening the benefits of growth. Water recycling, reliable electricity and training are strategic needs as AI demand increases factory requirements. Keeping advanced production at home will require sustained investment support and predictable policy.
Moving some packaging and mature chip production to allied markets could reduce geographic concentration while preserving leadership in the most advanced technologies. Partnerships with the United States, Japan and Europe support access to critical tools and markets. A measured expansion of free trade agreements could also help industries outside semiconductors that struggle to compete on price alone.
Taiwan must also manage currency swings, financial stability and housing affordability in Hsinchu and Taipei. South Korea's challenge is to connect its recovering chip industry with stronger activity across the economy. Both face the task of turning large industrial investments into gains that reach more households.
The Bottom Line
- Taiwan's projected growth for 2025 is about 5.1 percent, compared with roughly 0.8 percent for South Korea.
- August exports reached about $58.5 billion in Taiwan and $58.4 billion in South Korea.
- Taiwan's GDP per person is forecast to exceed $38,000 and surpass South Korea's for the first time in roughly 22 years.
- Semiconductors account for about 22 percent of Taiwan's GDP and 10 percent of South Korea's.
- Taiwan leads in advanced logic manufacturing and packaging, while South Korea's memory producers also benefit from AI demand.
- Tariffs on autos, parts and steel weigh on South Korea, while many chip products remain outside the tightest restrictions.
- Both economies need more electricity, water infrastructure and skilled workers to support new factories.
- Overseas investment is spreading chip production, but the most advanced manufacturing remains concentrated in Taiwan.