Nearly 50,000 Kilometers of Track, Trillions of Yuan in Debt
China State Railway Group reported a net profit of 3.3 billion yuan, about $457 million, in 2023, its best operating performance in history. By the end of 2024, however, its debt had reached 6.2 trillion yuan, nearly $860 billion. Those figures capture the financial tension behind the world's largest high-speed rail network: a system that has transformed travel while accumulating an enormous bill.
Contents
- Nearly 50,000 Kilometers of Track, Trillions of Yuan in Debt
- How China Built So Much So Quickly
- Why a Record Profit Leaves a Large Debt Problem
- How Railway Borrowing Spreads the Financial Risk
- Fare Increases Bring the Pressure to Passengers
- Who Can Afford a Railway Financed by the Public?
- Why Some Stations Have Too Few Passengers
- Construction Costs and the Freight Tradeoff
- Expansion Continues as Authorities Seek Restraint
- Key Points
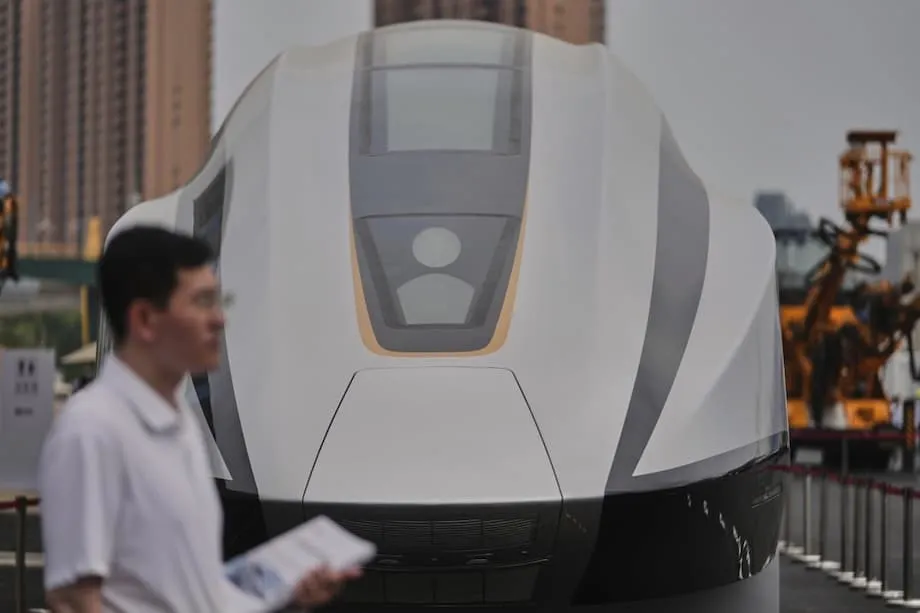
In less than two decades, China built nearly 50,000 kilometers of high-speed railway connecting most major cities. Bullet trains carry passengers between Beijing and Shanghai in just four hours. New magnetic levitation train prototypes, known as maglevs, have reached speeds above 600 kilometers per hour.
The engineering achievement is accompanied by a difficult economic calculation. Busy routes serving prosperous cities can attract enough passengers to make money. Many lines elsewhere face low demand, expensive maintenance and construction debts that ticket sales struggle to support.
As of August 7, 2025, China still planned further expansion, with another 2,600 kilometers of track scheduled for the year and the network projected to exceed 50,000 kilometers. Authorities were also seeking to restrain unnecessary construction, raise revenue and find investment. For passengers, the pressure was already visible in higher fares on several major routes.
How China Built So Much So Quickly
China's modern high-speed rail expansion began in earnest in 2008, when its first high-speed passenger line opened. The government subsequently invested trillions of yuan, treating railway construction as a way to stimulate domestic demand, create jobs and bring development to less prosperous regions.
By 2021, the network connected 93% of cities with populations above 500,000. Its projected length of more than 50,000 kilometers in 2025 would dwarf the combined high-speed railway mileage of Germany, Japan and the United Kingdom.
National pride and the desire to demonstrate Chinese technological capabilities helped drive construction. Provincial governments also wanted investment and higher gross domestic product, the measure of economic output in their areas. They borrowed heavily to build lines and stations, including in remote places where passenger demand was limited.
The underlying expectation was that economic growth and rising incomes would eventually fill the trains. Building early could give an area better transport before businesses and residents arrived. Where that growth failed to produce enough passengers, however, the construction bill remained.
The expansion and the financial pressures developed over several years:
- 2008: China's first high-speed passenger line opened, beginning the rapid expansion.
- Since 2010: More than 20 high-speed rail stations have been closed or left unused because of low passenger traffic.
- 2021: The network reached 93% of cities with populations above 500,000.
- 2023: China State Railway Group reported net profit of 3.3 billion yuan, while an estimate put the profitable share of the network at about 6% by the end of the year.
- June 2024: China Railway announced fare increases of 20% to 40% on four major routes.
- End of 2024: Railway debt reached 6.2 trillion yuan.
- 2025: Another 2,600 kilometers of track were planned, with the network projected to exceed 50,000 kilometers.
Why a Record Profit Leaves a Large Debt Problem
China State Railway Group's 2023 profit was a positive operating result, but it was small beside the debt accumulated through expansion. The 6.2 trillion yuan burden reported at the end of 2024 exceeded the debt of troubled property developer Evergrande Group.
Profit measures what a business earns after its costs over a period. Debt is money borrowed that still has to be repaid. A railway can improve its annual results while continuing to carry a large bill from tracks, stations and other infrastructure built earlier.
Only a handful of routes, mainly in wealthy coastal regions, were profitable. Beijing-Shanghai and Guangzhou-Shenzhen were among the examples. An estimate attributed to analysts put the profitable share of the network at about 6% at the end of 2023. Most routes, particularly inland, faced losses associated with low ridership and high maintenance costs.
Even profitable services face a long process of recovering their original investment. Operating profits, when achieved, leave the separate challenge of paying for construction. The busiest lines are expected to need decades to recover their initial investment.
Wang Kuo-chen, an assistant researcher at the Chung-Hua Institution for Economic Research in Taipei, explained why raising ticket prices could address only part of the financial pressure:
The increase in ticket prices can cover only general income but will not help the deficit in fixed asset investment, which must be filled by real estate. However, China's housing market is sluggish and cannot be used to support high-speed rail.
Fixed asset investment means spending on lasting physical assets, such as railway tracks and stations. Wang's concern connects the railway debt problem to the housing downturn: property development had been expected to help support infrastructure investment, but a weak market reduced that support.
How Railway Borrowing Spreads the Financial Risk
China Railway finances expansion by selling bonds to banks and brokerages owned by the state. A bond is a loan from an investor to the issuer, which promises to repay the money under agreed terms. This arrangement has allowed railway construction to continue on a vast scale.
Borrowing through the railway company allows the government to support expansion without adding the same borrowing directly to the official national debt. The approach has been described as a form of hidden debt because the financial obligation sits outside the headline government borrowing figure.
State institutions are involved on several sides: the railway operator borrows, public financial institutions provide funding, and local governments support construction. Financial risks are consequently spread across the public sector, making them harder to track and manage.
Local governments face their own squeeze. Economic growth has slowed, revenues have shrunk and debts have risen while the property market has deflated. Their ability to keep supporting railway projects has weakened at the same time that some routes continue to need financial help.
Fare Increases Bring the Pressure to Passengers
China Railway announced increases of 20% to 40% in June 2024 on four major high-speed routes, including the profitable Beijing-Guangzhou and Shanghai-Kunming lines. The increases were described as the largest since the network began.
Higher fares were intended to offset rising operating costs and help subsidize routes losing money. Subsidizing a route means using income from elsewhere to help pay for a service that cannot cover its own costs. For a national network, that can keep less busy connections running, but it also places more pressure on passengers using stronger routes.
Business travelers and office workers whose employers reimburse their journeys can more readily absorb higher ticket prices. Passengers paying from their own wages face a different calculation, especially when household finances are already under strain.
Research cited in the debate indicated that about a quarter of the population avoided high-speed rail because of low incomes. During busy periods such as the Spring Festival, many migrant workers chose slower, cheaper trains because a high-speed ticket could cost one or two days of wages.
Lynn Ling, a writer who migrated from Chengdu to Taiwan, described the household pressure behind opposition to higher fares:
The price increase adds insult to injury as wages drop and daily necessities become more expensive.
Users of Douyin and Weibo also expressed frustration. One commenter summed up the feeling of being asked to carry costs without sharing the gains:
Wealth has nothing to do with me, but I have to share all the suffering.
Who Can Afford a Railway Financed by the Public?
Higher fares create a practical dilemma for the government. Charging more can improve railway income, but it can also push ordinary passengers toward slower services. Keeping fares low preserves access while leaving more of the network's financial losses to be covered elsewhere.
Public funds and borrowing helped build the system, yet wealthier travelers are better placed to use it regularly. Concerns about social exclusion center on that gap: people may share the financial burden of a national project while finding its tickets difficult to afford.
Migrant workers illustrate the tradeoff in concrete terms. A faster journey can save hours, but a ticket costing one or two days of wages competes with other household needs. A slower train can therefore remain the more practical choice even where high-speed service exists.
The same system delivers substantial public benefits. It shortens journeys, connects remote regions, reduces regional disparities and has become a source of national pride. Some analysts argue that these social gains should carry weight alongside ticket revenue and company profit.
The financial challenge is deciding how much support those benefits justify when debt is already large. Higher prices, continued subsidies and further expansion each distribute the costs differently among passengers, railway companies and public institutions.
Why Some Stations Have Too Few Passengers
More than 20 high-speed rail stations have been closed or left unused since 2010 because passenger traffic was too low, particularly in inland provinces. Their situation reflects the risks of building ahead of demand in remote or sparsely populated areas.
Many lines and stations formed part of economic stimulus packages. Political goals often carried more weight than assessments of construction costs, likely passenger numbers and the time needed to recover investment. Local governments hoped better rail access would attract businesses and raise nearby property values.
Some stations were built in inconvenient locations or places with too few potential passengers. When development did not arrive as expected, the railway had little traffic to generate fares. The property market's collapse also weakened the land and housing activity that local authorities had expected to support growth around stations.
Zhao Jian, a professor at Beijing Jiaotong University, questioned whether some projects met the central government's own criteria:
Many newly built HSR lines should not have been built, if assessed according to the standards set by the central government.
Local governments were left struggling to repay construction loans while some stations stood empty. Building a line could immediately create activity and jobs, but keeping it financially viable required a lasting flow of passengers.
Construction Costs and the Freight Tradeoff
Each kilometer of high-speed track costs 120 million to 130 million yuan to build, nearly three times the cost of traditional railway. Maintenance also demands extremely precise standards, and the trains need frequent, costly upkeep.
Passenger fares provide most of the network's revenue. High-speed trains are not suited to carrying freight, limiting the scope to earn income from goods as well as people. A sparsely used passenger route therefore has fewer ways to compensate for weak ticket sales.
Zhao argued that China, as a manufacturing powerhouse, needed greater freight capacity, something the high-speed passenger network could not provide. Investment concentrated on high-speed rail has come at the expense of traditional rail systems, affecting the balance of the country's transport and logistics network.
The issue also appears in arguments about railway investment abroad. In the United States, high-speed rail proposals have faced criticism over costs, expected ridership and environmental benefits. A Cato Institute analysis argued that dedicated high-speed infrastructure cannot be shared with freight or other uses, making it less cost effective than highways or conventional rail.
China's experience brings the choice into focus: faster passenger journeys and wider regional connections have value, while construction costs and the need for goods transport also require funding. A line's usefulness to a region and its ability to repay its construction debt are separate parts of that calculation.
Expansion Continues as Authorities Seek Restraint
Chinese authorities have begun tightening approval criteria for new infrastructure, with greater attention to economically strong regions and projects where demand is clearer. President Xi Jinping reportedly ordered a halt to unnecessary new lines, warning that unfinished projects could further depress housing prices and create a cycle of debt and underuse.
China Railway has adjusted timetables, lowered fares in remote areas and sought private investment by listing subsidiaries. Timetable changes can better match services to demand, while lower prices may attract passengers where trains have spare capacity. Selling shares in subsidiaries offers another route to investment.
These measures are unlikely to remove the debt burden or make unprofitable routes viable by themselves. Other proposed reforms include further fare increases, fewer stations and better governance. Each is politically sensitive: higher prices affect affordability, and reducing stations can affect local access.
The planned addition of 2,600 kilometers in 2025 shows that financial restraint has not ended expansion. The government hopes increased passenger and cargo transport will raise railway revenue, while exports of Chinese high-speed rail technology create opportunities abroad. Cargo growth relates to the wider railway business, while high-speed services depend mainly on passengers.
China's network has already changed how people travel and connected places that once required much longer journeys. Its next task is to reconcile those benefits with the cost of maintaining services and repaying construction debt. As of August 7, 2025, no timetable had been given for making the network financially sustainable.
Key Points
- China's high-speed rail network covered nearly 50,000 kilometers and was projected to exceed that length in 2025.
- China State Railway Group reported profit of 3.3 billion yuan in 2023, while debt reached 6.2 trillion yuan by the end of 2024.
- An estimate put the profitable share of the network at about 6% at the end of 2023, with stronger routes concentrated in wealthier regions.
- Fare increases of 20% to 40% announced in June 2024 aimed to improve finances but increased affordability concerns.
- More than 20 stations have been closed or left unused since 2010 because passenger numbers were too low.
- Authorities were tightening project approvals while planning another 2,600 kilometers of track in 2025.
- Faster travel and regional development remain major benefits, alongside the unresolved cost of construction debt and services losing money.