October 30 filing will arrive without a clean audit opinion
Nidec will submit a report on its internal controls to the Tokyo Stock Exchange on October 30, 2026, without the clean audit opinion it had hoped to secure, putting the Japanese motor maker into a review that could end with its shares being delisted.
Contents
- October 30 filing will arrive without a clean audit opinion
- Why PwC still needs more evidence
- What the investigation found across the group
- How the accounting problems reached this point
- What the exchange will examine
- Three possible outcomes for the shares
- Why the timing of a decision matters
- Nidec also plans action against former executives
- Investors face a review while audit work continues
- Key Points
The company said on October 28 that checks requested by auditor PwC Japan remained unfinished, including work concerning employees involved in improper accounting. Nidec had aimed to submit amended financial reports with an audit opinion by the anniversary of its placement under special alert, but now expects to complete its part of the additional checks in November.
PwC Japan has declined to express an opinion on Nidec's accounts for both years ended March 2025 and March 2026 because it could not obtain sufficient evidence. The latest delay leaves the exchange assessing whether Nidec has repaired its financial reporting controls while the audit work continues.
The stakes extend beyond correcting figures. The exchange must decide whether the company's controls are properly designed and working in practice, whether further supervision is appropriate, or whether its shares should leave the market. Nidec is listed on the exchange's Prime Market under stock code 6594.
The October 30 submission comes almost exactly a year after special alert status took effect on October 28, 2025. Under the exchange's rules, companies generally must have suitable internal controls in place and operating by the review held after that first year. Nidec must now demonstrate how its reforms work inside the business, rather than simply describe the systems it has introduced.
Why PwC still needs more evidence
PwC Japan's concerns include the continued involvement in financial reporting of people who had participated in improper accounting. Additional matters requiring checks emerged from late September, extending the work needed before the auditor could reach a conclusion.
A clean audit opinion means the auditor concludes that the financial statements present the company's finances fairly, in all material respects, under the applicable accounting rules. A disclaimer of opinion, the outcome attached to Nidec's accounts, means the auditor lacks enough appropriate evidence to express an opinion.
Nidec had planned to amend its annual report for the year ended March 2026, along with reports for earlier periods, as it submitted its internal control confirmation. It has now postponed those amended filings.
November is the company's target for finishing and reporting its additional work to PwC, while the audit completion date and amended filing dates remain undetermined. The exchange also has no fixed deadline for its decision. A Japan Exchange Group official said previous reviews generally produced results within two to three months.
What the investigation found across the group
Nidec's accounting investigation response says the company received the independent Third-Party Committee's final investigation report on April 17, 2026. The findings covered multiple cases of accounting misconduct at several business bases across the group.
The company identified practices including avoiding the recording of expenses and overstating profit. Expenses are costs a business incurs. Leaving them out can make reported profit look larger because profit is calculated after subtracting costs from income.
Nidec released a revised improvement plan on April 27, ten days after receiving the final report. Its stated priorities were greater organizational diversity, more transparency and replacement of its old system.
The company's stated aim is to complete the revised plan, regain trust and have special alert status removed. The audit delay shows that the immediate work still includes resolving questions about the people and procedures used to prepare financial reports.
How the accounting problems reached this point
Suspected improper accounting cases began emerging in May 2025. The exchange's Nidec designation notice gives a detailed account of the problems that led to its intervention.
The notice describes trade transaction issues at an Italian subsidiary, questions about the treatment of a purchasing lump sum at a Chinese subsidiary, and suspicions that management had arbitrarily considered when to recognize reductions in asset values. An asset write down records that something a company owns is worth less than the amount shown in its books.
The key dates trace how an accounting investigation became a listing review:
- June 27, 2025: Nidec disclosed that the filing deadline for its annual report for the year ended March 2025 had been extended to September 26 while Italian subsidiary issues were investigated.
- September 3, 2025: Nidec disclosed the establishment of an independent committee to investigate additional accounting concerns.
- September 26, 2025: Nidec filed the annual report with a disclaimer of audit opinion while investigations continued.
- October 28, 2025: The Tokyo Stock Exchange placed Nidec under special alert.
- April 17 and April 27, 2026: Nidec received the final investigation report and then released its revised improvement plan.
- October 28, 2026: Nidec announced that it would miss its target for amended accounts carrying an audit opinion.
- October 30, 2026: Nidec plans to submit its internal control confirmation for the exchange's review.
The September 2025 filing followed an extension of about three months. The exchange said at the time that Nidec still could not present a timetable for returning its financial reporting schedule to normal.
What the exchange will examine
The Tokyo Stock Exchange's special alert rules require an affected company to submit an internal control confirmation promptly after a year has passed since designation. The exchange evaluates that document and other information to decide what happens next.
Internal controls are the checks, responsibilities and reporting procedures that help a business prepare reliable accounts and follow its obligations. They include how information reaches management, how accounting decisions are reviewed and how suspected problems are investigated.
Nidec's original designation cited weaknesses in companywide information and communication, as well as controls over the preparation of accounts. Nidec itself had judged those weaknesses serious enough to require disclosure because of their potential effect on financial reporting.
The exchange's rules make the quality and timing of the confirmation consequential. A company that fails to submit it promptly, or submits a document the exchange considers plainly inadequate, is treated as lacking properly established and operating controls. Relevant provisions include Listing Regulations Article 503 and the delisting provision in Article 601, Paragraph 1, Item 9.
Three possible outcomes for the shares
The exchange can lift special alert status if it finds that internal controls are both properly established and operating, subject to rules requiring continued observation for some companies.
It can continue the designation if the controls are properly established but their operation remains inadequate, provided there is a reasonable prospect that they will operate properly. This route gives the company another period in which to demonstrate improvement.
Delisting follows if the exchange finds that controls are not properly established, or that there is no longer a prospect of their proper operation. The rules also allow delisting between scheduled reviews if that prospect disappears.
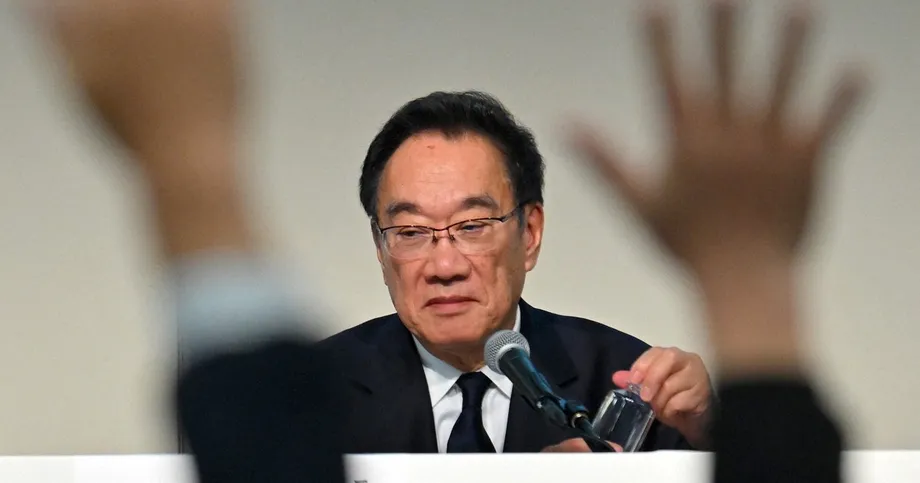
Nidec president and chief executive Michio Kaida said the company had put systems and mechanisms in place, while acknowledging unresolved practical issues raised by the auditor. At the October 28 news conference in Tokyo, he described the company's work:
We have been working to improve our internal control systems and resolve audit-related issues,
Kaida's account places the focus on whether the new arrangements work during actual financial reporting. That is a central test in the exchange's decision between continued supervision and delisting.
Why the timing of a decision matters
The exchange's rules tie the next review period to the financial year in which it decides to continue a designation. Where controls are established but still need to operate properly, the company generally must resubmit its confirmation within three months after the relevant financial year ends.
A special timing provision applies if fewer than three months remain between the continuation decision and that year end. In that case, the following financial year becomes the reference period.
For a company such as Nidec, whose financial year ends in March, the difference can be substantial. A continuation decision in December 2026 would generally point to the year ending March 2027 and a submission within three months afterward. A decision in January 2027 would leave fewer than three months before that March year end, moving the reference period to the year ending March 2028.
Continued observation can also apply to companies whose controls have improved but that meet specified financial or listing risk conditions. Under that separate process, special alert status can continue for as many as three financial years, with repeated checks. The rules therefore allow several forms of continued supervision, each with its own conditions.
Nidec also plans action against former executives
Nidec said on October 27 that it had decided to seek damages from founder Shigenobu Nagamori and eight other former executives over the suspected accounting irregularities. The planned defendants include former chairman Hiroshi Kobe and former chief executives Mitsuya Kishida and Jun Seki.
The group also includes two other former directors, two former corporate auditors and a former chief financial officer. Seki is now chief strategy officer for electric vehicles at Taiwan's Foxconn.
A company appointed committee of outside lawyers said Nagamori had breached his supervisory duties by failing to report suspected irregularities to the board and auditors and by failing to seek necessary investigations. Nidec said it was still determining the compensation amount and would file the lawsuit when preparations were complete.
The planned legal action addresses responsibility for past conduct. The exchange's immediate task is to assess the company's present controls and their operation, including how accounting concerns are identified, communicated and resolved.
Investors face a review while audit work continues
Nidec shares closed 3.6% higher on October 28 after falling as much as 7.7% during the session. The reversal showed a sharp market reaction on a day when investors were weighing both the missed audit target and the approaching submission to the exchange.
Shareholders now face two processes moving alongside each other. PwC must obtain enough evidence to decide whether it can express an audit opinion, while the exchange must assess Nidec's internal control confirmation and decide its listing status.
The company's November work target is the next operational milestone. Its October 30 confirmation is the next formal step in the listing process. For investors, the central information will be whether the remaining checks are completed, what PwC concludes and whether the exchange finds that Nidec's reforms work in practice.
Key Points
- Nidec plans to submit its internal control confirmation on October 30, 2026, without a clean audit opinion.
- PwC Japan declined to express opinions on the accounts for the years ended March 2025 and March 2026 because it lacked sufficient evidence.
- Nidec expects to complete its additional checks in November; the audit and amended filing dates are undetermined.
- The exchange can lift special alert status, continue supervision under specified conditions or delist the shares.
- Nidec's investigation identified expense recording avoidance and profit overstatement across multiple group locations.
- The company also plans to seek damages from founder Shigenobu Nagamori and eight other former executives.