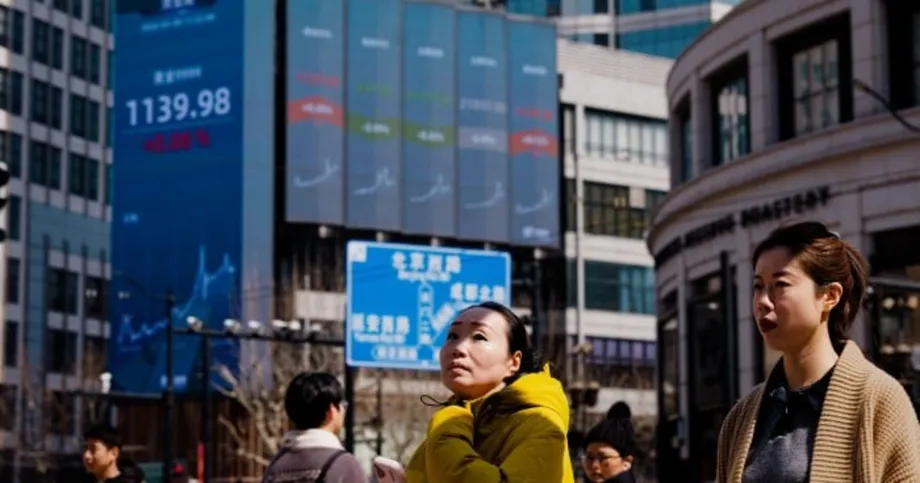
A 40% fall puts China's technology ambitions under pressure
China's STAR50 Index has fallen about 40% in less than four months, erasing roughly $480 billion in market value and exposing a widening gap between enthusiasm for artificial intelligence and the profits companies are delivering. The figures, described in accounts dated October 26 and 27, 2026, capture a sharp reversal after a rally lasting about two years.
Contents
- A 40% fall puts China's technology ambitions under pressure
- Why the losses spread across the market
- Popular listings suffer some of the sharpest falls
- Lower prices still leave demanding valuations
- AI service discounts meet rising chip costs
- Robotics and export access face separate tests
- Beijing's market reforms confront a funding problem
- The dates behind the reversal
- Some investors stay invested as regional risks grow
- Key Points
The main account measures the decline from a July peak; another measures it from June. The broader CSI300 Index, which tracks large Chinese companies, has fallen about 20% from its June high. Estimates put the loss across China's stock market since May at $2.4 trillion, a much broader measure than the losses associated with the STAR50.
The pressure reaches beyond share prices. Companies preparing to sell shares face weaker investor demand, households that bought into the technology boom are nursing losses, and Beijing's effort to channel savings into domestic innovation has become more difficult.
Even after the retreat, STAR50 shares trade at about 100 times earnings over the previous 12 months, compared with roughly 30 times for the US Nasdaq 100. Investors are still paying a large premium for Chinese technology companies at a time when demand, export access and profitability are uncertain.
No single trigger has been identified. Traders have pointed to expensive valuations, tax bills and concern that Washington could restrict Chinese equipment in American data centers. Together, those pressures have turned a debate about future growth into a more immediate test of business returns.
Why the losses spread across the market
Goldman Sachs estimates that AI stocks account for 42% of the combined market capitalization of mainland A shares and Hong Kong H shares, and 57% of their trading value. A shares trade on mainland exchanges, while H shares are shares of mainland companies listed in Hong Kong.
Those figures show how concentrated investment has become. Companies connected to AI represent more than four dollars in every ten dollars of market value in that universe, while attracting more than half the money changing hands. A sharp fall in that group therefore reaches investors far beyond specialist technology funds.
China's market has a large population of individual investors. Chen Wensheng, a small business owner and investor in Hainan, joined the rally partly because he believed companies such as robot maker Unitree enjoyed official support. He and his friends are now facing losses.
Dong Baozhen, a fund manager based in Beijing, described the earlier surge as a speculative boom that had reversed:
The stock market later evolved into a speculative crazy bull. And now we see the bubble bursting.
The US Nasdaq Composite was down about 6% from a record reached three weeks earlier. China's 40% STAR50 decline covers a longer period, but the figures illustrate the much deeper retreat confronting Chinese technology investors.
Popular listings suffer some of the sharpest falls
Unitree shares have lost about half their value since trading began in August. During its initial public offering, or IPO, individual investors applied to buy roughly 8,000 times the number of shares available to them. An IPO is the first sale of a company's shares to public investors.
That extraordinary demand was followed by steep losses. Memory chipmaker CXMT has fallen more than 25% over the preceding month. Chip developers MetaX Integrated Circuits and Moore Threads Technology have each lost about half their value since July.
MetaX and Moore Threads had previously surged about 700% and 400%, respectively, on their first trading days in 2025. Such jumps helped build expectations that new technology listings could deliver exceptional gains very quickly.
Zhongji Innolight and Eoptolink Technology, which make optical communications components, have fallen about 60% from their June and July highs. Their products help move data through the infrastructure used for AI computing, making access to overseas data center customers a central concern.
Lower prices still leave demanding valuations
The STAR50's price to earnings ratio has dropped from nearly 250 to around 100. This ratio compares share prices with the profits companies earned over the previous year. At 100 times earnings, investors are paying about $100 for every $1 of annual profit represented by the index.
The Nasdaq 100 trades at about 30 times earnings. On those figures, the STAR50's multiple remains roughly 3.3 times as high. The two indexes contain different businesses, but the comparison helps explain why investors remain concerned about prices even after a large decline.
Companies valued at high multiples usually face strong expectations for future profit growth. If sales grow more slowly than expected, costs climb or competition squeezes margins, investors may become willing to pay less for each dollar of earnings.
Dan Wang, China director at Eurasia Group, pointed to weak domestic demand, disappointing profit margins and US interest rate pressure as reasons for the anxiety. She also described concern among technology companies about whether investment supported by the state could translate into sufficient commercial demand.
Chinese consumers' reluctance to spend matters because businesses need paying customers as well as investment capital. Building advanced chips, AI systems or robots can expand production capacity, while earning a durable profit requires customers willing to pay enough to cover development and operating costs.
AI service discounts meet rising chip costs
Price competition in AI services was already visible in May 2024. Alibaba cut prices on some Tongyi Qwen models by up to 97%. Baidu made Ernie Speed and Ernie Lite free for business users, while ByteDance priced its main Doubao model 99.3% below the industry average.
These models are the software systems behind many generative AI products. Businesses can pay to access them through cloud services rather than building their own systems. Lower access prices can attract customers, while leaving suppliers with less revenue for each unit of use.
Hardware has recently faced pressure in the opposite direction. Accounts dated September 10, 2026, described indicated prices for Huawei's Ascend 950DT accelerator card rising 20% to 50% from quotations two months earlier, depending on contract terms. Cambricon's planned next generation processor was repriced 20% to 30% higher, with similar increases described at MetaX and Iluvatar CoreX.
A shortage of high bandwidth memory helped drive those increases. This memory stacks chips vertically so AI processors can access large amounts of data quickly. More expensive components raise the cost of supplying computing power, even as customers seek cheaper AI services.
Wang Zhuo, a partner at Shanghai Zhuozhu Investment Management, warned that competitive pressure would eventually reach chipmakers and AI suppliers:
Just like all other Chinese manufacturers, (chipmakers and AI suppliers) will eventually end up in a price war. There's no exception. All bubbles inevitably burst.
Robotics and export access face separate tests
China launched a state supported AI investment fund worth 60 billion yuan during the month covered by the October accounts. The funding reflects Beijing's continued commitment to domestic technology development despite the market retreat.
Robotics occupies a prominent place in that effort. Embodied AI means putting artificial intelligence into machines that interact with the physical world, such as humanoid robots. China sees potential uses for these machines as its population ages and its workforce shrinks.
Demand currently comes heavily from government agencies and research institutions. Many household buyers still find the machines too expensive or insufficiently practical. Dan Wang questioned how quickly that business could reach a broad consumer market:
It doesn't look like embodied intelligence could turn into profits in the in the mass market.
Overseas sales face political risks as well. US restrictions on Chinese humanoid robots have added to concern about access to American customers, while possible restrictions on Chinese data center components are weighing on optical equipment suppliers.
The timing and scope of any additional US restrictions on data center components remain unsettled. For companies already struggling with weak demand at home, the prospect of losing export opportunities adds another reason for investors to reconsider earnings forecasts.
Beijing's market reforms confront a funding problem
Chinese authorities have tried to replace repeated booms and busts with steadier gains. Measures have included tighter controls on borrowing to buy shares and on high frequency trading, in which computers place large numbers of orders at great speed. Investors supported by the state have also sold shares during rallies to restrain excessive gains.
China Securities Regulatory Commission Chairman Wu Qing met market participants earlier in the month to hear proposals for improving capital markets. The wider policy objective is to make share investment more dependable while directing capital toward businesses that support technological development.
Leo Wang, a partner at Beijing based Qianchuang Capital, argued that the strong focus on technology companies in major indexes had pulled money away from other industries and encouraged excessive valuations in favored sectors.
Falling prices now complicate the next stage of fundraising. An existing listed company may have to sell more shares to raise the same amount of money. A business preparing an IPO may have to accept a lower valuation or postpone its plans.
Hong Hao, managing partner and chief investment officer at Lotus Asset Management in Hong Kong, described the potential effect on prospective listings:
What's happening is now going to put a stop for many of the companies trying to get themselves listed.
China has also tightened restrictions on overseas investment, with further regulations scheduled to take effect on December 1. Those measures sit alongside the effort to encourage domestic investment, although households facing stock losses have increasingly sought more defensive assets.
The dates behind the reversal
The current selloff follows several stages of enthusiasm, aggressive pricing and rising costs. Keeping those events in order helps explain why investors are now examining both customer demand and the expense of supplying AI.
- May 21, 2024: Price cuts by Alibaba, Baidu and ByteDance illustrated intensifying competition in AI model services.
- 2025: MetaX and Moore Threads recorded gains of roughly 700% and 400% on their stock market debuts.
- June and July 2026: Major Chinese indexes and several AI suppliers reached the highs used to measure the subsequent declines.
- August 2026: Unitree began trading after exceptionally heavy demand from individual IPO investors.
- September 10, 2026: Accounts of higher AI processor prices highlighted pressure from memory shortages.
- October 26 and 27, 2026: Market accounts described the STAR50's roughly 40% fall and mounting concern over technology valuations.
- December 1: Further Chinese regulations affecting overseas investment are scheduled to take effect.
US corporate earnings offer another near term checkpoint. Alphabet, Microsoft, Amazon and Meta Platforms were scheduled to report during the week of the October market accounts. Their spending forecasts matter to suppliers selling equipment for AI infrastructure.
Some investors stay invested as regional risks grow
HSBC research found that funds focused on Asia still held a greater share of Chinese stocks than their benchmarks, despite net selling over the previous three months. A benchmark is the index against which a fund's allocation and performance are compared.
Goldman Sachs included Innolight and CXMT among dozens of companies on a revised list of recommended Chinese AI stocks. William Bratton, a strategist at BNP Paribas Securities, also saw selective buying opportunities for careful investors. Their positions show that the market retreat has produced different judgments about individual companies.
Dan Wang described continuing optimism in AI research and satellites, with the latter benefiting from expectations of sustained state support because of military connections. At the same time, many mainland investors have shifted toward other sectors or are waiting for lower prices.
Thailand and other Asian economies have a stake in how the adjustment develops because China plays a large role in regional electronics and semiconductor supply chains. If Chinese companies delay fundraising or capacity expansion, suppliers elsewhere could face changes in investment plans and future orders.
The concrete measures to watch are company earnings, customer orders, capital spending and expansion decisions. Share prices can change much faster than factories or purchasing contracts. For regional suppliers, the business impact will depend on whether financial pressure reaches those operating decisions.
Key Points
- The STAR50 has fallen about 40%, with roughly $480 billion in market value erased.
- The broader CSI300 has declined about 20% from its June high.
- Goldman Sachs estimates AI stocks represent 42% of combined A share and H share market value and 57% of trading value.
- The STAR50 still trades at around 100 times trailing earnings, compared with about 30 times for the Nasdaq 100.
- Weak demand, expensive components, service price cuts and possible US restrictions are putting expected profits under pressure.
- Lower valuations could delay IPOs and make technology fundraising harder.
- Some investment firms still see buying opportunities, while regional suppliers are watching orders and capital spending.