Regulator orders sales suspension through January 2027
Japan's Financial Services Agency has ordered Prudential Life Insurance and Gibraltar Life Insurance to stop soliciting insurance and signing new contracts from October 13, 2026, through January 31, 2027, after finding serious failures in supervision, customer protection and management oversight.
Contents
- Regulator orders sales suspension through January 2027
- Why the financial totals differ
- How the scandal developed
- Personal relationships escaped company oversight
- Gibraltar and the parent face separate findings
- Compensation reviews are not the same as payments
- Discipline reaches 157 employees
- Pay and branch reforms target sales incentives
- Customer monitoring expands, but data risks persist
- What must happen before sales can return
- Key Points
The October 9 action followed the publication of an independent investigation into fraudulent or inappropriate transactions involving Prudential Life customers worth 5.2 billion yen, approximately $33 million, over more than three decades. The regulator also ordered the insurers' parent, Prudential Holdings of Japan, to improve its governance and supervision of subsidiaries.
The FSA's administrative orders require all three companies to submit improvement plans by November 30, 2026. For the two insurers, the agency demands thorough investigations, appropriate customer compensation, disciplinary action and changes to sales management and compensation systems. It also requires responsibility to be established for current and former executives.
The suspension is narrower than a shutdown of the insurers. Services for existing contracts, including insurance payments and benefits, will continue. The agency did not revoke Prudential Life's operating license, and its orders allow individual exceptions where the regulator considers an activity necessary to protect policyholders.
Prudential Life had already voluntarily stopped new sales in February. The compulsory suspension now extends beyond the November 5 end date announced for that voluntary pause. The January 31 expiry date does not settle when sales will actually resume: the company must still address the failures identified by investigators and the regulator.
Why the financial totals differ
The scandal has produced several different monetary figures, each describing a different assessment or stage of the investigation. They should not be treated as interchangeable measures of confirmed losses or compensation paid.
The October 8 investigation announcement put fraudulent or inappropriate customer transactions at 5.2 billion yen. Another account of the investigation put losses reported by victims above 6.1 billion yen. A separate company disclosure described confirmed fraud involving 157 current and former employees, 676 customers and approximately 4.34 billion yen.
These figures distinguish the value of transactions examined, losses claimed by customers and fraud described as confirmed. They cannot be added together, and a reported loss is not automatically a compensation award. The final amount payable depends on individual reviews.
The scale is greater than at the first disclosure in January, when Prudential Life identified approximately 3.1 billion yen improperly received from customers. A more detailed account put that initial amount at 3.14 billion yen, involving 107 current and former employees and 503 customers between 1991 and 2025. The October transaction figure of 5.2 billion yen is about 2.06 billion yen, or 66%, above the initial 3.14 billion yen figure, although the later investigation covered a broader set of conduct.
Customer counts also differ. Prudential Life's October official release identifies 498 individuals in the January 16 cases, rather than the 503 cited in the earlier account. The company does not explain that difference in the release. Neither figure represents the full number of people who subsequently submitted claims or inquiries.
How the scandal developed
The regulatory action followed months of expanding complaints, compensation reviews and inspections. Prudential Life's initial disclosure led to the resignation of then President Kan Mabara and an FSA inspection beginning in late January.
The main developments span the following dates:
- January 16, 2026: Prudential Life disclosed misconduct involving more than 100 current and former employees and approximately 3.1 billion yen received from customers.
- February 10: The company began a voluntary suspension of new sales, initially scheduled to end on May 9.
- April 22: The company reported about 700 damage reports and inquiries and extended the sales pause through November 5.
- October 7: A system for recording specified customer meetings and producing AI summaries began operating.
- October 8: Prudential Life published the independent investigation and announced compensation, disciplinary and reform updates.
- October 9: The FSA announced suspension and improvement orders.
- October 13 to January 31, 2027: The compulsory suspension of insurance solicitation and new contract signing applies to both insurers.
The April total of about 700 reports and inquiries was more than double the approximately 300 disclosed on February 10. About 70 concerned Gibraltar Life, showing that complaints had extended beyond Prudential Life well before the October orders.
The regulator found that the voluntary sales pause had not solved supervision problems. At Prudential Life, some sales employees contacted customers without sales manager approval, contrary to restrictions during the pause. Cases involving inappropriate receipt of customer money also continued to emerge after the suspension began.
Personal relationships escaped company oversight
The investigation and regulatory findings describe a business problem extending beyond individual employees. Prudential Life relied exclusively on sales staff known as Life Planners, whose pay was fully linked to performance and who generally had freedom over their working hours and locations.
Branches recruited their own salespeople and gained considerable independence as they expanded. According to the FSA, successive management teams had repeated opportunities to address the risks but preserved the model to prioritize sales. Headquarters became reluctant to challenge branches, while branch managers and other sales managers were themselves involved in some misconduct cases.
Prudential Life's October 8 reform statement says the independent committee found that private relationships between employees and customers made it difficult for managers and headquarters to see what was happening. Inappropriate money transfers and investment solicitations could continue repeatedly without detection.
The problems included personal lending and borrowing, investment solicitations unrelated to insurance, unsuitable insurance sales and policy replacements. The FSA also identified failures to verify whether sales met customer wishes and whether required information had been provided.
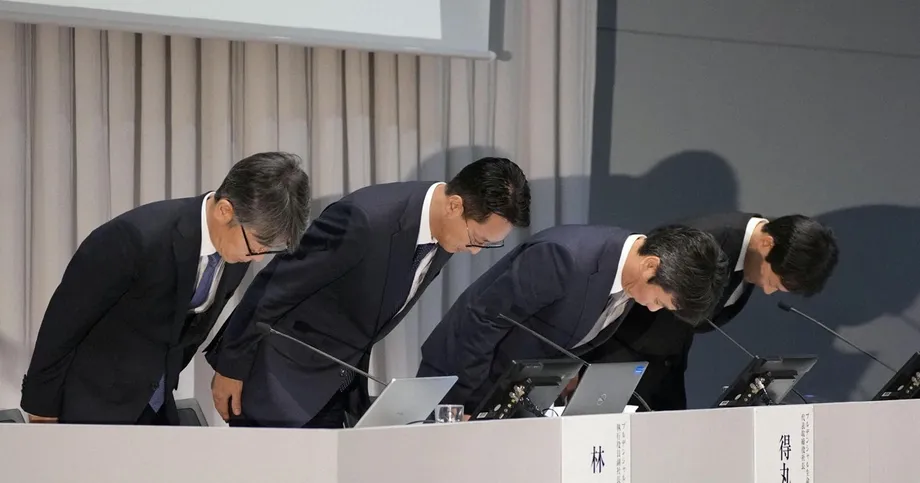
Hiromitsu Tokumaru, Prudential Life's president, acknowledged at the October 8 press conference that management had contributed to both the misconduct and its duration.
We take seriously that we have shaken the very foundation of trust," Tokumaru said. "It was not the problem of specific employees, but the way the management operated that caused the misconduct and prolonged the situation.
Gibraltar and the parent face separate findings
Gibraltar Life received the same suspension dates, but the FSA set out findings specific to its operations. Unlike Prudential Life, Gibraltar sells through general agencies as well as its own Life Plan Consultants.
The regulator said Gibraltar had adopted a similar recruitment, training and sales model after beginning operations in 2001. Recruitment favored employees able to produce sales quickly, often through their existing personal networks. That approach helped create customer relationships that managers and headquarters could not adequately observe.
Gibraltar's management recognized problems with rewards tied to sales and private customer relationships but feared staff departures and weaker business performance if it made fundamental changes, according to the FSA. Supervisors' own compensation and evaluations also depended heavily on recruitment and their teams' sales, weakening their incentive to challenge problematic conduct.
The parent company's failures were broader still. Prudential Holdings of Japan was supposed to supervise its insurance subsidiaries, but the FSA found that it gave excessive weight to their independence, checked reports formally rather than examining operations deeply, and failed to provide sufficient compliance resources.
Internal audit arrangements also fell short. Although audit resources had been centralized, personnel seconded from subsidiaries continued to audit their original companies, limiting examination across the group. The agency also identified management statements and behavior that discounted the importance of internal audit.
The insurers' suspension and improvement orders were issued under Article 132, paragraph 1, of Japan's Insurance Business Act. The parent's improvement order was issued under Article 271-29, paragraph 1. The FSA relied on its own inspections and legally required reports, as well as the independent investigation, rather than simply accepting the company's findings.
Compensation reviews are not the same as payments
An independent Customer Compensation Committee established by Prudential Holdings of Japan decides whether compensation is warranted and how much should be paid. The distinction between a completed review and a payment matters when assessing progress.
Prudential Life said reviews were complete for 492 of the 498 individuals in the January 16 cases, leaving six unfinished in that defined group. That is approximately 98.8% reviewed. The release refers to a compensation progress update dated September 16, 2026, but completion of a review does not itself mean a customer received compensation.
A broader account said the committee had assessed claims from 1,345 customers, including Gibraltar Life customers, and approved compensation for 676. It did not disclose how many cases remained under review. Those figures cover a different population from the 498 individuals in Prudential Life's January cases.
The same caution applies to an April update. By April 17, screening and compensation procedures covering 1.7 billion yen for 259 customers had been completed, but the company said that group included customers denied compensation. The 1.7 billion yen therefore cannot be described as money paid to victims.
Tokumaru has said that compensation and discipline must take precedence over reopening sales.
"We'll never prioritize resuming sales over compensating victims and taking disciplinary measures against those involved," he said.
Discipline reaches 157 employees
The detailed disciplinary figures help explain the reported total of 157 current and former sales employees. Prudential Life identified 146 people involved in the January cases and completed action against that group by April 2026.
Of those 146, 53 were dismissed or asked to resign, 68 were suspended, and 25 received warnings, reprimands or other measures. The figures include equivalent measures applied to former employees. In separate cases, another 11 employees were dismissed or asked to resign.
The Prudential Financial filing repeats that breakdown. Adding the 53 and 11 gives 64 dismissals or requested resignations. Some reports describe all 64 as dismissals, but the official wording includes both forms of departure.
Tokumaru, Vice President Yasuhiro Akiyama and Vice President Kuniyoshi Hayashi will each voluntarily return 30% of their monthly remuneration for three months. Tokumaru indicated that he intended to remain in office to complete preventive measures.
The pay returns are only one part of management accountability. The company says decisions concerning current and former management remain subject to external advice and board procedures. The FSA explicitly requires responsibility to be clarified, including that of past directors.
Pay and branch reforms target sales incentives
Prudential Life plans to introduce a minimum guaranteed salary in 2027. Under the proposed design, the company would make up the difference when monthly compensation falls below a specified amount. It has not disclosed that guaranteed amount.
The plan also increases the share of compensation for servicing existing policies from less than 5% to approximately 20%. At the stated figures, that would be more than four times the previous share. New contract commissions would be paid over seven years instead of four, while evaluations would include policy continuation, compliance and sales quality.
These changes aim to reduce pressure to obtain immediate new sales and give greater weight to maintaining suitable customer relationships. Their effectiveness is not established simply by announcing them, particularly given the FSA's findings that previous measures were postponed or inadequately tested.
Sales manager compensation would also change. The basic salary share would be approximately 30%, direct links between pay and the number of recruits would be abolished, and managers would generally stop selling insurance themselves so they could concentrate on supervision.
The company plans to replace its 139 branches with 40 to 50 under a new structure, a reduction of approximately 64% to 71%. Seven pilot branches are scheduled to begin on November 1, 2026, alongside the planned closure of 30 existing branches. New management roles would divide responsibility for branch governance, oversight of multiple teams and supervision of individual sales employees.
Customer monitoring expands, but data risks persist
Prudential Life has introduced daily activity reports for sales employees and provided governance training to approximately 4,000 sales staff. It also obtained declarations that employees had not engaged in inappropriate handling of money. Where necessary, it may request credit information and tax returns voluntarily and with employee consent.
A Customer Support Partner program introduced in April gives customers direct contact with headquarters rather than leaving the relationship solely with their salesperson. The team had 51 members at the October release, with expansion planned from fiscal 2027.
The meeting recording system launched on October 7 records specified meetings with customer consent and uses artificial intelligence to produce summaries. It covers designated discussions involving existing contracts as well as applicable sales and servicing meetings. The company's stated purpose is to make interactions visible and detect customer protection problems earlier.
Customer information requires separate attention. The FSA found improper removal of information by former sales employees and weaknesses in investigations into similar cases. At Prudential Life, it also identified suspected improper import and use of personal information acquired through previous employment.
Gibraltar had comparable risks involving departing employees taking customer contact details. Recording meetings addresses visibility into conversations, but it does not by itself resolve how information is collected, accessed or removed. Prudential Life says it is strengthening information controls and moving to company issued smartphones.
What must happen before sales can return
The November 30 improvement deadline applies to Prudential Life, Gibraltar Life and their holding company. Both insurers must obtain reviews of their improvement plans and implementation from external specialists with insurance or corporate governance expertise.
All three companies must report progress every three months, with the first reporting reference date at the end of February 2027. Reports are due by the 15th of the following month, making the first scheduled submission March 15, 2027.
The final compensation bill, the full number of unresolved claims and further decisions on former executives remain unsettled. Prudential Life also continues to review suspected inappropriate insurance solicitation. Its announced approach would permit sales only by employees confirmed to meet company standards, but that approach must now operate within the regulatory suspension.
The commercial cost is already substantial. In April, Prudential indicated that the scandal could reduce profits by $550 million under the American parent's consolidated outlook. It also reported increased policy cancellations compared with the previous year. That forecast is separate from customer losses and compensation amounts.
The central test is whether revised pay, branch management and direct customer contact produce effective oversight where previous controls failed. The FSA's orders require evidence of implementation and continuing progress, extending scrutiny beyond the formal sales suspension.
Key Points
- Prudential Life and Gibraltar Life must suspend insurance solicitation and new contract signing from October 13, 2026, through January 31, 2027.
- The investigation described 5.2 billion yen in fraudulent or inappropriate transactions; reported losses and confirmed fraud figures use different measures.
- Existing policy services, including insurance payments and benefits, will continue.
- Prudential Life disciplined 157 current and former employees, including 64 dismissed or asked to resign.
- Planned 2027 reforms include minimum guaranteed pay, greater compensation for policy servicing and longer commission payment periods.
- All three companies must submit improvement plans by November 30, with continuing progress reports required.
- The final compensation total and actual date for resuming sales have not been settled.