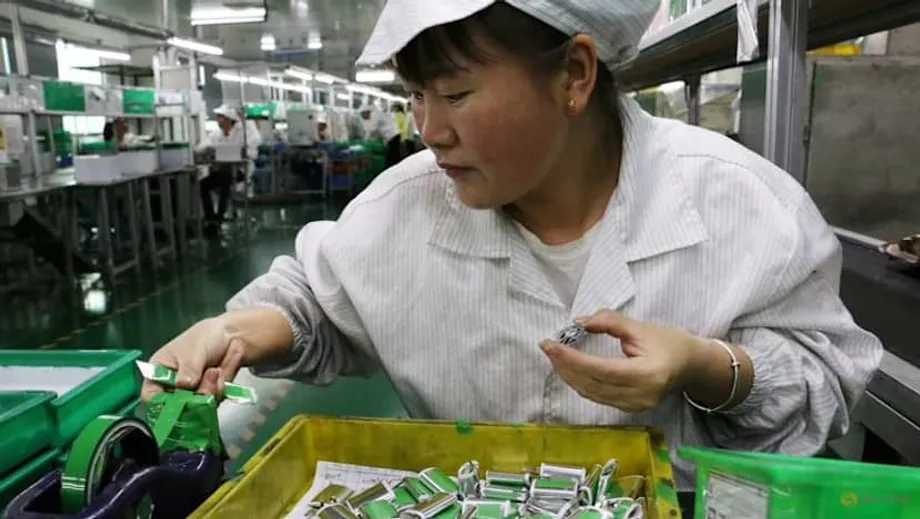
The battery bottleneck sits inside chemical plants
China controls between 60 and 70 percent of global lithium chemical refining capacity despite ranking ninth in lithium resources, according to Benchmark Mineral Intelligence (BMI), a London agency specializing in battery supply chains and price reporting. That imbalance places Chinese chemical plants at the center of the shift from petrol engines to electric motors, from Berlin to California.
Contents
- The battery bottleneck sits inside chemical plants
- Why mined lithium needs another transformation
- Why production outside China still depends on China
- A price collapse delayed the next wave of supply
- Zimbabwe's export suspension exposed another dependency
- The dates behind the supply pressures
- Discarded batteries return to the same processing network
- New refineries need more than a completed building
- Higher costs make diversification harder to finance
- Alternative batteries and US brines offer a long timetable
- What to Know
Governments seeking to reduce transport emissions need batteries, and batteries need lithium processed to exacting standards. Possessing lithium deposits is only the first step. The more decisive constraint comes when rock or salty underground water must become chemicals that battery manufacturers can use reliably.
Luc Braun, a BMI research analyst specializing in lithium and global hard rock mining, described China's position in converting minerals extracted from rock:
China thus completely dominates hard rock conversion capacity,
Refining shapes costs and supply reliability. China's advantage also reaches beyond lithium chemicals: BMI puts its share of global cathode active material production at approximately 86 percent and battery cell manufacturing at 85 percent. Cathode active material is a key battery ingredient into which processed lithium goes.
As of March 17, 2026, efforts to build competing supply chains face a difficult combination of technical challenges, volatile prices and higher construction costs. China also dominates the processing of discarded batteries, while alternative battery technologies depend on other chemicals whose production is concentrated there.
The central problem for countries seeking greater independence is therefore larger than opening mines. They need dependable chemical plants, customers willing to approve their output, financing that survives price crashes, and systems for recovering materials when batteries wear out.
Why mined lithium needs another transformation
Australia supplied approximately 31 percent of mined lithium in 2025, followed by South America at 27 percent, China at 21 percent and Africa at 19 percent, according to BMI. Much of the material extracted outside China travels there for conversion.
Lithium generally comes from two sources: spodumene, a mineral mined from hard rock largely in Australia and parts of Africa, and underground brine in South America's Lithium Triangle. Brine is water containing dissolved salts, including lithium.
Srinivas Popuri, a battery value chain expert advising automakers and investors, explained why extracting those materials leaves substantial work unfinished:
A mine gives you lithium-bearing rock or brine, but the battery supply chain runs on tight-spec lithium carbonate and lithium hydroxide,
Popuri compared the process with making usable fuel from oil:
Mining gives you crude oil. Refining gives you petrol and diesel that meet strict specifications and behave predictably in engines,
Lithium is similar. You take a relatively messy raw input and convert it into a purified chemical with tightly controlled impurities and consistent physical properties.
Small differences in purity or physical properties can change battery performance, manufacturing yield and lifespan. Yield means how much usable output a factory gets from its inputs. Problems at this stage affect both the price carmakers pay and the dependability of their supplies.
Chemical conversion requires considerable energy and technical skill. China's established industrial clusters put equipment suppliers, engineers, chemical companies and battery manufacturers close together. That arrangement helps reduce costs and shorten production timelines, advantages that a new plant operating far from such a network struggles to reproduce.
Why production outside China still depends on China
South American brine producers often make lithium chemicals at facilities connected to their own extraction operations. Braun described the limits of this capacity:
the vast majority of chemical output outside China comes from South American brine operations, which are typically integrated facilities,
Those facilities generally process their own feedstock rather than material supplied by other mines. Roughly half of South America's chemical output also falls short of battery grade and needs further refining, frequently in China.
Australia and Africa supply much of the hard rock feedstock used by Chinese converters. Concentrated ore travels to Chinese plants, where it becomes lithium carbonate or lithium hydroxide. Once purified, it can move quickly into nearby cathode and battery factories, sometimes within the same industrial clusters.
The International Energy Agency's 2025 Global Critical Minerals Outlook found that refining became more geographically concentrated across nearly all critical minerals between 2020 and 2024. For lithium, the combined share of the three largest refining countries rose from around 82 percent to 86 percent, an increase of four percentage points, with China driving most of the growth.
That combination of imported minerals and concentrated processing creates dependencies in both directions. Overseas buyers rely on Chinese chemical production, while Chinese refiners need a continuing flow of material from mines abroad.
A price collapse delayed the next wave of supply
Lithium prices rose eightfold during 2021 and 2022 as electric vehicle demand accelerated, then fell by more than 80 percent by 2024, according to IEA data. The reversal forced producers to cut activity and made new projects harder to finance.
Contemporary Amperex Technology (CATL), China's largest battery maker, scaled back lithium operations in Jiangxi province because of high costs and weak prices. Jiangxi Jiuling Lithium suspended production at mining units. In Australia, Global Lithium Resources scaled back feasibility studies, while Arcadium Lithium announced plans to place its Mt Cattlin spodumene operation into care and maintenance by the middle of 2025. That status means keeping a site maintained while production is halted.
YJ Lee, director at Singapore based Arcane Capital Advisors, described 2023 to 2025 as:
a pretty painful lithium winter.
Lee said the downturn was brief compared with the full energy transition, but its effect on investment lasted longer:
What did happen was a lack of capital that caused many lithium developers to put a hold on their projects, delaying them by several years,
Projects postponed during a period of low prices can leave less supply available later. Recovery was expected only by 2028, extending the pressure on developers trying to finance new capacity.
Lithium conversion also produces waste and residues that require careful treatment. Environmental compliance, permitting and waste management add costs and uncertainty to construction schedules.
A leading Chinese lithium producer, speaking anonymously, connected the industry's health to dependable mining supply:
Only when upstream mine supply is stable can the industry chain develop normally,
The producer also said costs and the maturity of production processes at different stages affect prices and supply quality.
Zimbabwe's export suspension exposed another dependency
Zimbabwe announced an immediate suspension of all lithium concentrate exports on February 25, 2025, including shipments already in transit. The decision unsettled Chinese industry and triggered an overnight rally in lithium prices.
Zimbabwe accounted for roughly 10 percent of global mined lithium supply and approximately 15 percent of the lithium processed in China. Its export ban had originally been planned for January 2027, but the government brought the restriction forward to push companies into processing more material locally.
Nick Mangwana of Zimbabwe's information ministry accused some operators of rushing to export before the planned deadline:
Instead of preparing for value addition, some actors engaged in a frenzy of mining activity, seeking to extract and export as much raw lithium as possible before the deadline,
Mangwana described the resulting stockpiling as a "plunder" of the country's economic future. The suspension created a direct supply shock for Chinese refiners dependent on imported spodumene concentrate from Africa and Australia.
Chinese companies including Sichuan Yahua Industrial Group and Zhejiang Huayou Cobalt were building lithium sulfate plants in Zimbabwe to meet local processing requirements. Lithium sulfate is an intermediate product, so producing it locally still leaves further steps within China's wider industrial network.
Calisto Radithipa, founder of Botswana based Kemcore, said lithium sulfate has greater value than raw concentrate and generates higher royalties for host governments. Farai Maguwu of the Centre for Natural Resources Governance warned that such arrangements risk creating "the illusion of local industrialization" while increasing dependence on Chinese companies whose priorities may differ from local development goals over the longer term.
The dates behind the supply pressures
The sequence of price changes, restrictions and investment decisions shows how quickly supply conditions can shift, even though building replacement capacity takes years.
- 2021 and 2022: Lithium prices increased eightfold as demand for electric vehicles accelerated.
- By 2024: Prices had fallen more than 80 percent, prompting production cuts and investment delays.
- January 2025: Tesla began operations at its lithium refinery near Corpus Christi, Texas.
- February 25, 2025: Zimbabwe immediately suspended lithium concentrate exports, bringing forward restrictions originally planned for January 2027.
- Middle of 2025: Arcadium Lithium had planned to place Mt Cattlin into care and maintenance.
- July 2025: China's new black mass standards were scheduled to take effect.
- 2027: Production from prospective US brine developments could begin.
- 2028: Recovery from the lithium downturn was expected.
These different schedules leave a gap between a sudden disruption and the years needed to develop another dependable source of processed material.
Discarded batteries return to the same processing network
China's position extends into recycling. BMI projected that China would process 3.6 million tonnes of scrap batteries in 2025, accounting for 78 percent of global pretreatment capacity and 89 percent of black mass refining capacity.
Black mass is the material left after batteries are shredded. Refiners recover lithium, nickel and cobalt from it so that those materials can return to new cathodes. Shredding and chemical recovery are separate stages, and the latter requires sophisticated processing.
China's black mass refining capacity was projected to reach 2.5 million tonnes in 2025, up from 895,000 tonnes in 2022. By comparison, North America had 21,000 tonnes of capacity and Europe 28,000 tonnes. China's projected capacity was therefore almost 2.8 times its 2022 level.
Large capacity does not mean every plant is busy. Some Chinese recycling refinery units were operating at utilization rates as low as 20 to 30 percent amid excess capacity. New national black mass standards scheduled for July 2025 were expected to legalize imports and introduce unified production standards, strengthening the supply chain.
Battery chemistry creates another financial problem. Manufacturers are moving toward lithium iron phosphate (LFP) batteries and away from some nickel cobalt manganese (NCM) formulations. Without nickel and cobalt, the materials recovered from an LFP battery have lower intrinsic value.
Luke Sweeney, senior battery recycling analyst at Fastmarkets, described the difficulty:
The lack of nickel and cobalt kills the economics of recycling LFP batteries,
That pressure is particularly difficult for recyclers outside China already competing against its scale. Recycling can return valuable material to production, but China's dominance at the recovery stage means discarded batteries can feed back into the same concentrated supply chain.
New refineries need more than a completed building
The United States and Europe have launched efforts to establish more lithium refining at home. Tesla began operating its refinery near Corpus Christi in January 2025, designed to supply battery grade lithium for its own electric vehicle production.
Dutch supplier AMG illustrated the remaining gaps by continuing to ship spodumene from Brazil to China for conversion before processing in Germany. Limited alternatives can keep Chinese plants involved even when companies are building capacity elsewhere.
Braun said recently opened plants were still working toward their intended production levels:
Those projects that have only recently been commissioned are in their ramp-up phases and have output well below their nameplate capacity,
Nameplate capacity is the amount a plant is designed to produce. Actual output can be much lower while equipment, chemical processes and operating routines are being stabilized.
Popuri described what customers and investors need from competing plants:
They need plants that run steadily at high yield, producing consistent battery-grade material that is qualified by major cathode and cell makers and backed by long-term offtake to support financing,
Qualification means a battery manufacturer has approved the material for use. Offtake agreements are commitments to buy future output, giving lenders more confidence that a plant will earn money.
Higher costs make diversification harder to finance
Capital costs for projects in regions seeking to diversify supply typically run 50 percent higher than those of incumbent producers, according to the IEA. Price volatility and economic uncertainty make private investors more cautious about funding those projects.
Lee of Arcane Capital Advisors said parallel Western supply chains would be "structurally higher-cost" and "will take far longer than the US and EU countries think." The challenge combines construction expense with the work of achieving consistent commercial production.
The gutting of major components of the US Inflation Reduction Act, which provided funding and incentives for batteries and electric vehicles, cooled investment sentiment. Chinese companies, meanwhile, benefited from subsidized credit.
AidData research found that the ten largest publicly traded Chinese mining companies paid effective interest rates of 3.7 percent, compared with 7.1 percent for foreign competitors. The difference was 3.4 percentage points. Cheaper borrowing helps companies tolerate volatile prices and thinner margins while prioritizing strategic market expansion over immediate profits.
The United States imported 97 percent of its lithium, primarily from Argentina and Chile, while still requiring Chinese processing for battery grade materials. Its dependence therefore involved both foreign mineral supply and the chemical steps needed to make that supply usable.
Alternative batteries and US brines offer a long timetable
Lithium was considered unlikely to be displaced from electric vehicle batteries within five to ten years. Sodium-ion batteries offered the most promising alternative because their manufacturing processes resemble those used for lithium-ion batteries, although their lower energy density suits particular applications. Lower energy density means storing less energy for a given battery size or weight.
China's position extends to ingredients used in alternative chemistries. It produces 95 percent of high purity manganese sulphate and 75 percent of purified phosphoric acid, important inputs for sodium-ion and LFP batteries. Changing chemistry can therefore leave other processing dependencies in place.
The United States had only one commercial scale lithium production operation, in Nevada. The Smackover Formation in Texas had emerged as a potentially substantial brine source, with ExxonMobil and Chevron acquiring land positions and production potentially beginning in 2027.
Water use, the management of toxic chemicals and permitting delays could slow development. Domestic supply was expected to remain marginal for years, even as companies pursued these deposits.
David Zhang of the International Intelligent Vehicle Engineering Association in Hong Kong predicted that China's existing advantages could sustain its lead for five to ten years. He also expected the location of the constraint to shift:
But the bottleneck will change,
Constraints could move between chemical production routes or toward other inputs between mining and battery manufacture. Lithium would remain part of the chain even as the most difficult processing step changed.
The IEA projected that by 2035 the average share held by the top three refined material suppliers would decline only to 82 percent, returning to the concentration level recorded in 2020. Meaningful diversification was expected to take until the late 2020s and 2030s, leaving the electric vehicle transition dependent on Chinese refining for years.
What to Know
- China controls 60 to 70 percent of lithium chemical refining capacity despite ranking ninth in lithium resources.
- Australia supplied 31 percent of mined lithium in 2025, South America 27 percent, China 21 percent and Africa 19 percent.
- China also accounts for approximately 86 percent of cathode active material production and 85 percent of battery cell manufacturing.
- Lithium prices fell more than 80 percent by 2024 after rising eightfold in 2021 and 2022, delaying investment and new supply.
- Zimbabwe's February 25, 2025 export suspension exposed Chinese refiners' dependence on imported mineral concentrate.
- China held 89 percent of global black mass refining capacity, extending its position into battery recycling.
- Higher costs, technical difficulties and financing pressures mean substantial diversification will take years.