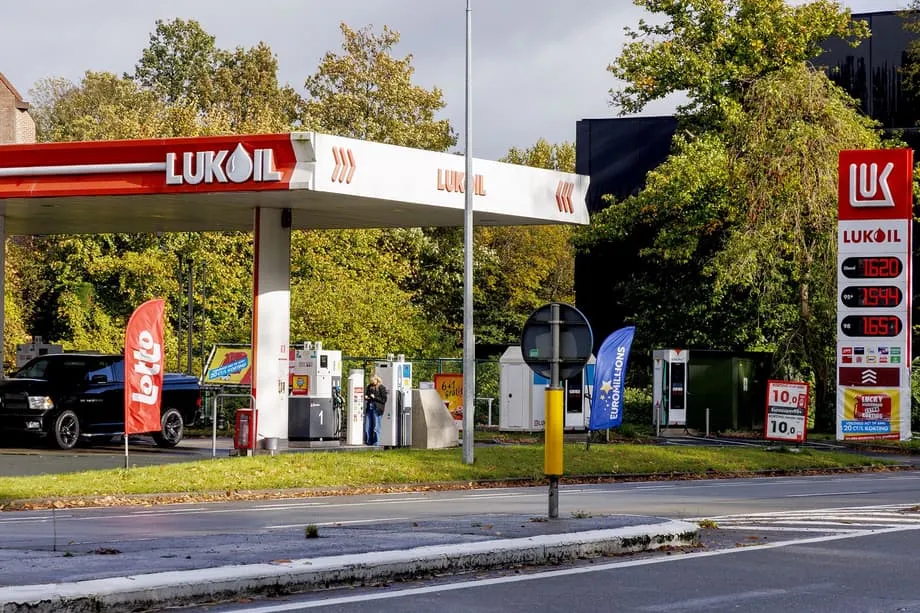
A global oil portfolio faces a change of hands
Lukoil, Russia's second largest oil producer, has accepted an offer from Swiss energy trader Gunvor to buy Lukoil International GmbH, the subsidiary holding its overseas assets. The proposed sale brings together interests in more than 30 countries, including a 75 percent stake in Iraq's West Qurna 2 oil field, refineries in Bulgaria and Romania, terminals and retail fuel networks.
Contents
- A global oil portfolio faces a change of hands
- Why selling the whole portfolio is a major step
- What the November 21 deadline means
- West Qurna 2 is the largest upstream prize
- European refineries anchor the fuel business
- Customers face changes in contracts and supply arrangements
- Why Gunvor wants physical assets
- The price depends on more than the assets
- Approval must come country by country
- Trade routes may change more than oil prices
- What the companies must settle next
- The Bottom Line
As of October 31, 2025, the transaction still requires regulatory permission, including approval from the US Treasury's Office of Foreign Assets Control, known as OFAC. Lukoil and Gunvor have disclosed neither a price nor a closing date. Gunvor has confirmed talks about the acquisition, while Lukoil has committed not to negotiate with other potential buyers.
New US sanctions against Lukoil and fellow Russian producer Rosneft have created pressure to act quickly. A temporary Treasury license allows companies to wind down transactions with the two producers until November 21. Lukoil says an extension will be sought if necessary while the proposed transfer proceeds.
The acquisition would move a broad collection of oil fields, processing plants and distribution businesses from one of the world's largest private oil companies to one of its largest independent commodity traders. Host governments, banks, insurers, employees and customers all have a stake in how that transition is managed.
Lukoil linked its decision directly to international restrictions. In its company statement, the oil producer said the sale was due to:
"restrictive measures of some states introduced against the Company and its subsidiaries".
The immediate challenge is to turn an accepted offer into an approved transaction while keeping oil production, refinery operations, payments and deliveries running across many jurisdictions.
Why selling the whole portfolio is a major step
Russian energy companies have adjusted their businesses since 2022 as buyers, insurers and banks in Europe and North America distanced themselves from Russian crude and petroleum products. Lukoil's proposed disposal goes further by putting its entire international portfolio into a single transaction.
Executives and market participants view the agreement as the most consequential corporate action by a Russian energy group since sweeping Western sanctions connected to the war in Ukraine reshaped global oil trade. Selling the overseas business would remove a layer of sanctions risk for Lukoil and place responsibility for those assets with Gunvor.
Gunvor would need to manage the operations under a compliance framework acceptable to Western authorities and the countries hosting them. The sale would also accelerate a shift in which buyers aligned with Western markets, commodity traders and companies owned by governments have taken larger roles in assets and supply chains once dominated by Russian oil groups.
Lukoil's decision reflects both formal restrictions and the growing difficulty of doing business across different legal systems. Even where a particular transaction remains temporarily permitted, a bank, insurer or supplier may decide that its own exposure to sanctions risk is too great.
What the November 21 deadline means
The US Treasury's wind down license gives companies limited time to close out business with Lukoil and Rosneft. Such licenses are temporary legal permissions: they allow activities such as ending contracts, receiving payment for past deliveries and reorganising operations without breaching the relevant sanctions rules.
November 21 is a tight deadline for businesses linked to oil fields, refineries and storage facilities. Each operation depends on numerous contracts covering equipment, maintenance, transport, financing and sales. Closing or changing those arrangements takes coordination among companies that may operate under different national laws.
OFAC permission for the acquisition is a separate requirement. Its authorisation can determine how banks process payments, insurers cover risks and shipping companies move cargo connected to the assets during the transition.
Lukoil has said the parties will seek an extension of the current license if needed. Both companies have indicated that extensions may be necessary to prevent interruptions while the transaction advances. The temporary permission helps counterparties understand what they can do, although many banks and insurers apply internal rules stricter than the license itself.
The sequence leading to the proposed sale is short:
- Since 2022, Western sanctions and changes in commercial relationships have reshaped Russian oil trading.
- New US sanctions against Lukoil and Rosneft prompted a temporary allowance to wind down transactions.
- By October 31, 2025, Lukoil had accepted Gunvor's offer for its international subsidiary and agreed not to negotiate with other buyers.
- November 21 is the current deadline for winding down transactions under the Treasury license, with an extension to be sought if necessary.
West Qurna 2 is the largest upstream prize
Lukoil's 75 percent interest in Iraq's West Qurna 2 is the most prominent production asset in the international portfolio. The field is among the world's largest and has been a major source of growth for Lukoil outside Russia.
Production reached around 480,000 barrels a day in April, with further development phases planned by the operator and the Iraqi government. Upstream operations, the industry term for finding and producing oil and gas, therefore represent a substantial part of what Gunvor would acquire.
Iraq relies on West Qurna 2 for a material share of its exports. A transfer would require approval from Iraqi authorities and coordination with project partners, contractors and customers buying the oil. Field services, procurement and export logistics through Basra would all need to continue through the ownership change.
Lukoil's production interests extend beyond Iraq. They include a 25 percent stake in the Marine XII block offshore Congo, concessions in Egypt and exploration and development interests in other regions. Its wider overseas portfolio includes upstream and downstream projects in Central Asia, Africa and Latin America. Downstream operations process, distribute or sell the fuel produced from crude oil.
European refineries anchor the fuel business
Lukoil owns the Neftohim Burgas refinery in Bulgaria, the largest refinery in the Balkans, with capacity of about 190,000 barrels a day. It also owns the Petrotel refinery in Romania. Both plants supply regional markets with gasoline, diesel and raw materials used to make petrochemicals.
The refineries sit within wider networks of storage, pipelines and fuel distribution. Selling them would involve more than transferring industrial equipment and land. Supply agreements, maintenance contracts and environmental obligations would also need to be addressed.
Bulgarian and Romanian authorities would expect a new owner to maintain domestic fuel supplies while meeting environmental, safety, customs and tax requirements. Labour agreements and investment plans would need to remain consistent with national and European standards.
Lukoil also holds interests in oil terminals and retail fuel chains across parts of Europe, which are expected to transfer if the deal closes. Those businesses connect imported or locally processed oil to customers, making continuity in distribution as important as keeping refinery machinery operating.
Customers face changes in contracts and supply arrangements
Lukoil supplies crude to buyers in Central Europe and Turkey, including deliveries to Hungary and Slovakia. Its supply business has also included barrels destined for Turkey's STAR refinery, owned by Azerbaijan's state oil company SOCAR.
STAR relies heavily on Russian crude grades and has worked with several trading partners to secure feedstock, the crude oil a refinery processes. A change in ownership of Lukoil's foreign operations could alter who arranges those flows, while leaving the refinery's need for dependable supplies unchanged.
Customers in Central Europe will be watching delivery schedules and the terms of their contracts. Some agreements may be novated, meaning the new owner formally replaces the existing contracting party. Others may be renegotiated to meet fresh compliance requirements.
Most large refiners and traders have prepared contingency plans over the past two years. Those preparations should help limit unexpected changes in scheduling and product availability. New commercial arrangements would be intended to keep cargo moving without gaps.
The sale would therefore affect both ownership and the daily coordination of trade. A refinery needs crude to arrive at the right time, storage space to be available and buyers ready to receive its products. Banks and insurers must also be willing and legally able to support those movements.
Why Gunvor wants physical assets
Gunvor is a major independent commodity trader based in Switzerland. It became prominent in the 2000s as a leading trader of Russian crude. Cofounder Gennady Timchenko sold his stake in 2014 after the United States imposed sanctions over Russia's annexation of Crimea.
Since 2022, volatile oil and gas markets and higher trading margins have benefited Gunvor. The company has reinvested profits in energy infrastructure, including refineries, production assets, power generation and renewables.
Owning physical assets gives a trader more choices about where to source, process, store and sell energy. A refinery can process different mixes of crude, while a trader can seek better returns by adjusting timing, blending and the markets where finished products are sold.
Storage tanks and terminals provide room to hold cargo or redirect it when prices are stronger elsewhere. Retail networks supply a steady outlet for fuel and give their owner closer knowledge of local demand. Lukoil's portfolio would expand Gunvor's access to all of those activities across several regions.
Trading houses traditionally concentrated on moving oil and gas without owning the fields or plants producing them. Since the war in Ukraine began, several have bought refinery or production interests. Physical assets can provide steadier cash flows and help manage risks when shipping, insurance or financing becomes constrained.
The price depends on more than the assets
Valuing Lukoil's international business means assessing a giant Iraqi oil field, two European refineries, logistics networks, retail operations and production interests across Africa and other regions. Estimates vary widely because information about the assets is uneven between countries.
Sanctions add costs and uncertainty beyond those in a conventional sale. A buyer must consider regulatory conditions, access to financing and the expense of operating across many jurisdictions. Analysts tracking distressed transactions and sales affected by sanctions expect those pressures to produce a discounted price, potentially well below book value, the value recorded in company accounts.
The final figure will depend on exactly which assets are included and how inventories and working capital are treated. Working capital covers the resources needed for everyday operations, including money tied up in stock and outstanding customer payments.
Payment arrangements present another challenge. Banks handling the transaction would need to be willing to participate and authorised to do so under OFAC permissions. Escrow accounts, where money is held until agreed conditions are met, and payments made in stages are common features of sales involving sanctions.
Lukoil's decision to negotiate exclusively with Gunvor gives the parties space to work through those issues. They still need a binding agreement specifying the assets, price adjustments and arrangements for handing over staff and operations.
Approval must come country by country
OFAC clearance is central to the transaction, with other US and European agencies also likely to have a role. Host countries will examine changes in ownership under their own oil and gas, competition and environmental laws.
Some jurisdictions require formal notification and approval periods before control changes hands. National oil companies or ministries may also hold rights to buy an interest before another purchaser, or powers to veto a transfer.
The portfolio's presence in more than 30 countries makes the process unusually broad. An authorisation covering one field, refinery or subsidiary would sit alongside requirements elsewhere, each with its own commercial relationships and legal obligations.
Employees, communities and local suppliers also have practical interests in the outcome. Refinery workforces expect continuity, while environmental liabilities and commitments to repair damage must be addressed as assets change ownership. Governments may seek specific promises on investment and maintenance before approving a buyer, particularly for strategic refineries and major producing fields.
Trade routes may change more than oil prices
Oil prices have been driven primarily by OPEC plus policy, global demand and supply disruptions connected to conflicts. Transferring ownership of assets already operating generally has a limited immediate effect on prices.
Trade routes and commercial margins could see a greater effect. A trader controlling refineries and storage can choose different sources of crude, redirect products, change inventory levels and use different hedging strategies. Hedging means using financial contracts to reduce exposure to changes in market prices.
Gunvor, Vitol and Trafigura have expanded beyond their traditional merchant roles since 2022. Owning infrastructure in strategic locations can help them manage shipping bottlenecks and connect sourcing, processing and sales more closely.
A completed acquisition would bring one of the largest overseas portfolios connected to a Russian oil producer under a trader seeking to operate within US and European compliance systems. Its commercial importance lies in how those existing assets could be organised and supplied under new control.
What the companies must settle next
Lukoil and Gunvor must agree on the final transaction terms and a detailed transition plan. Due diligence, the process of checking a business before buying it, will focus on permits, environmental commitments, supply contracts running for many years and amounts owed by or to the operations.
West Qurna 2 and Burgas will require particularly careful planning because production and refining must continue safely during any handover. Partners, contractors and regulators will need to coordinate changes without interrupting essential services.
The parties intend to use the temporary Treasury permission to support permitted operations and banking while the sale progresses, seeking more time where needed. Once approvals are obtained, Gunvor would integrate the businesses into its supply, trading and risk management systems.
Employees and customers will judge the transition by practical results: salaries paid, maintenance completed and deliveries arriving on schedule. The companies' aim is continuity across those activities while ownership, contracts and financial arrangements change.
The Bottom Line
- Lukoil has accepted Gunvor's offer for its international subsidiary and agreed not to negotiate with other buyers.
- The proposed sale follows new US sanctions against Lukoil and Rosneft.
- The current Treasury license allows transactions to be wound down until November 21, with an extension to be sought if necessary.
- The portfolio spans more than 30 countries and includes 75 percent of West Qurna 2 and refineries in Bulgaria and Romania.
- Completion requires OFAC permission and approvals across the countries hosting the assets.
- The price will depend on the assets included, financing, sanctions risks and regulatory conditions.
- Keeping production, fuel deliveries, salaries and maintenance running is central to the planned handover.