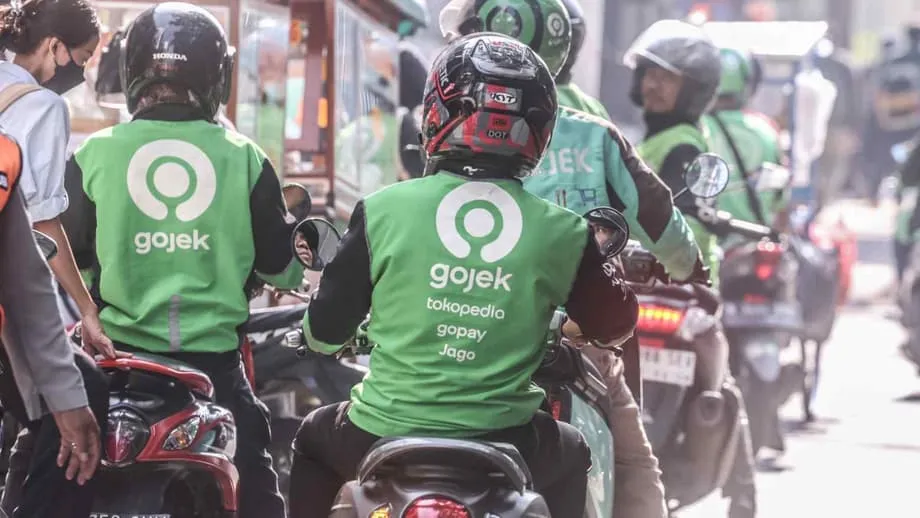
Financial services drive GoTo's next growth push
GoTo Group plans to build more minigames inside its apps to encourage users to explore credit features and small cash loans, as financial services grow faster than its ride hailing and delivery businesses. The Jakarta based company behind Gojek, Tokopedia and GoPay is putting everyday payments at the start of a broader journey into saving and borrowing.
Contents
- Financial services drive GoTo's next growth push
- What the latest numbers show
- How small games build daily habits
- From a payment reward to a loan offer
- A smaller app reaches beyond major cities
- Bank Jago connects payments, savings and borrowing
- Competition centers on repeat visits
- Rewards need clear boundaries around borrowing
- Credit checks must keep pace with growth
- What the next 12 months will reveal
- Key Points
The financial results explain the attraction. Third quarter net revenue reached about 4.7 trillion rupiah, up roughly 21 percent from a year earlier. Financial services revenue rose around 55 percent to nearly 1.5 trillion rupiah, while revenue from services such as ride hailing and delivery increased about 10 percent to roughly 3.2 trillion rupiah.
GoPay also passed 500 million transactions in September for the first time. Management wants to turn that payment activity into more frequent engagement, then use those visits to introduce other financial products. Interactive challenges, rewards for daily visits and small games have already helped encourage activity in payments. Credit is the next area of focus.
The strategy rests on a simple commercial idea: a person who regularly opens GoPay to transfer money or pay a bill is easier to reach than someone who must first be persuaded to download another app. A short game or reward can provide another reason to return, creating more opportunities to present a relevant savings or loan feature.
For GoTo, the potential benefit is a lower cost of bringing customers into additional services. For users, the important details are the size of a loan, its full cost and the repayment schedule that follows the initial invitation to borrow.
What the latest numbers show
GoTo recorded adjusted profit before tax of about 62 billion rupiah for the third quarter and raised its adjusted earnings guidance for the year to approximately 1.8 trillion to 1.9 trillion rupiah. These adjusted measures give a separate view of performance from revenue, which measures the money the business brings in.
Financial services gross transaction value rose about 30 percent from a year earlier to roughly 170 trillion rupiah. Gross transaction value is the total value moving through a service, rather than the amount the company keeps as revenue. Consumer loan growth and steady increases in payment transactions supported the financial services business.
Financial services revenue grew about five and a half times as quickly as revenue from on demand services, using the reported growth rates of 55 percent and 10 percent. Yet on demand services remained the larger business by revenue, at about 3.2 trillion rupiah compared with nearly 1.5 trillion rupiah for financial services. Fintech is taking a larger role while transport and delivery growth stabilizes.
GoPay's reach gives the strategy considerable scale. The value processed within its ecosystem is equivalent to roughly 3 percent of Indonesia's gross domestic product, and around 12 percent of the country's adult population uses the app each month.
How small games build daily habits
Minigames are brief, optional activities within an app, rather than full games. They can include rewards for checking in each day, wheels that offer a chance to win small vouchers, scratch cards, missions and progress bars that fill as tasks are completed. Their purpose is to create a quick sense of progress or anticipation.
GoTo has already used familiar versions of these tools. Daily bonuses encourage a sequence of visits. Wheels and scratch cards offer small prizes such as vouchers or fee waivers. Missions can reward someone for paying a phone bill, transferring money to a friend and topping up a wallet within a week. Badges and progress bars show when an activity is complete.
GoPay can fit these interactions into the short visits people already make to pay bills, buy mobile data or send money. The features work best when they are quick, reliable and consume little data, particularly for people using lower cost smartphones or slower connections.
Behavioral science and research into how people use apps help explain the approach: small rewards and visible progress can encourage repetition. A daily streak provides a reason to return, while a progress bar can guide someone through setting up bill reminders. Over time, repeated visits may improve customer retention and reduce the cost of introducing related products, including pay later services and small cash loans.
From a payment reward to a loan offer
GoPay's proposed journey connects attention with product discovery. A reward for checking in could lead to a discount on a utility payment. That payment could then provide the occasion for an invitation to try an installment plan. The intended starting point is a small loan with plain terms, clear pricing and a short repayment schedule.
A user who frequently pays bills might see missions and discounts connected to those payments. Someone interested in shopping on Tokopedia could receive an offer for a first installment plan with a low limit and a short term. These examples describe how engagement can guide the next offer toward a service the person already uses.
Preapproval connects that customer activity with underwriting, the process a lender uses to decide whether to lend and on what terms. Wallet transactions, purchases through online marketplaces and verified identity checks can help build a picture of a user and support a cautious initial credit limit.
GoTo's approach could allow an app to present an offer tailored to that information instead of directing someone to a lengthy form. Repayment amounts and dates could reflect previous behavior, while payments could come from the wallet balance or linked accounts. Automated repayments and reminders can make borrowing easier to manage and reduce missed payments.
The plan does not specify a launch date for the additional minigames or numerical targets for how many users should become borrowers. Its success will depend on whether frequent app visits translate into useful products, affordable repayments and lasting customer relationships.
A smaller app reaches beyond major cities
GoPay launched its standalone app in 2023 to reach further beyond Indonesia's largest cities. It uses less mobile data, is designed to work smoothly on lower cost phones and promotes free transfers and lower fees for bill payments.
Daily rewards and minigames have helped the app reach mass market users in tier 2 and tier 3 cities, meaning smaller urban markets beyond the main metropolitan centers. For these users, the practical value of an app includes how much data it consumes, how reliably it runs and what it costs to complete ordinary transactions.
GoTo gains more than payment volume from that wider reach. With permission, transaction activity can supply additional information for credit models. Regular payments and transfers can help the company understand patterns of use as it considers which products and limits to offer.
The sequence of developments shows how the payments business has become the entry point for a larger financial strategy:
- 2023: GoPay launched its standalone app to expand beyond major cities, with low data use and features suited to lower cost phones.
- September 2025: GoPay exceeded 500 million transactions in a month for the first time.
- Third quarter of 2025: Financial services revenue reached nearly 1.5 trillion rupiah, rising around 55 percent from a year earlier.
- October 31, 2025: GoTo's growth strategy includes plans for more minigames that encourage users to explore credit and small cash loans.
Bank Jago connects payments, savings and borrowing
GoTo owns about 22 percent of Bank Jago, which is integrated into GoPay. Users can open and manage bank accounts within the app, creating a route from everyday payments to saving and borrowing without moving between separate services.
Banking integration can simplify the movement of funds used for loans and give customers one place to follow balances, repayments and upcoming bills. Salary deposits and timely bill payments can also add verified information that helps assess credit risk, including the likelihood that a borrower will fail to repay.
For borrowers, reminders and automatic repayment can reduce the chance of forgetting a due date. For GoTo and its partners, closer integration can lower the cost of managing loans and improve the collection of money when a borrower falls behind.
The same structure supports gradual product development. A lender can begin with a small, simple credit line and increase the limit after a record of timely repayment. Installment options can be offered at checkout on Tokopedia and at other merchants. Savings pockets that reserve money for bills and microinsurance could eventually broaden the relationship beyond payments and credit.
These connections give GoTo several ways to deepen engagement. A customer might use GoPay for a transfer, Bank Jago for savings and an installment product for a purchase, with each service accessible through the same app experience.
Competition centers on repeat visits
Indonesia's digital finance market brings wallets, pay later providers and online lenders into daily competition for attention. Grab, Sea Group, Kredivo and Akulaku are among the regional platforms and local specialists seeking to turn frequent app use into broader financial relationships.
Reward points, daily tasks and challenges resembling games are part of that competition. The mechanics can look similar across apps, making execution important. Simple, dependable rewards connected to useful actions can support retention without pushing customers toward products they do not want.
GoTo's commercial goal extends beyond winning downloads. It wants people to form routines around the app. When customers return regularly for payments or small rewards, the cost of reaching them again can fall, and there are more opportunities to introduce relevant services.
Lending makes that calculation especially important. Interest and fee income must cover funding costs, promotional spending and losses when borrowers do not repay. Frequent visits are valuable to the business when they help generate income after those costs, rather than simply increasing the number of people who open the app.
Rewards need clear boundaries around borrowing
Indonesia's regulators have tightened oversight of consumer lending and pay later services in recent years. Expectations include responsible marketing, standardized price disclosures, checks on whether borrowers can afford repayments and protection of personal data.
Games create a particular design challenge when they sit beside credit products. A small reward is immediate, while a loan creates payments that continue after the interaction ends. Responsible design therefore needs to make the financial commitment easy to understand before a user accepts it.
Small starting limits, the full cost shown in rupiah before confirmation and repayment dates aligned with pay cycles are practical protections. Periods in which users pause before taking another loan can limit repeated borrowing in quick succession. Warnings near a credit limit and simple explanations of interest and fees can help people understand their commitments.
Games should never require users to take a loan to receive a reward. Rewards for setting up a bill reminder or building emergency savings offer ways to encourage helpful habits without making borrowing the condition for participation. These are responsible design measures for such services, rather than a list of safeguards confirmed for every GoTo product.
Credit checks must keep pace with growth
GoTo can combine wallet and marketplace histories with device checks and information from banking partners to verify identity and assess lending risk. Those inputs can help determine a starting limit and identify signs that a customer may be struggling.
Credit models can respond by reducing limits or pausing offers. Repayment records can then feed into later decisions, with higher limits following evidence of consistent payments on time. This creates a gradual lending process in which access grows alongside a borrower's demonstrated ability to repay.
Fraud controls also matter when promotions attract repeated participation. Biometric verification, which checks identity through physical characteristics, and anomaly detection, which looks for unusual patterns, can help address identity theft and abuse of rewards campaigns.
GoTo and its partners also need to manage the costs of serving borrowers after a loan begins. Funding arrangements, reminders, collections and the handling of missed payments all affect whether growth in lending produces a sustainable business.
What the next 12 months will reveal
GoPay's daily active users, the share interacting with minigames and the number completing a first loan will be early measures of adoption. The time between a first, second and third loan, together with repayment behavior, will help show whether entry through games leads to durable customer relationships.
Credit quality will require separate attention. Past due ratios show how much lending has fallen behind schedule. Net charge offs measure loans written off after accounting for recoveries. Roll rates track how borrowers move from one stage of late payment into another. Following these measures across groups of borrowers, regions, income bands and product types will be useful as GoPay expands into smaller cities.
Investors will also watch the cost of credit losses, funding costs through banking partners, marketing expense for each active borrower and cash operating profit per loan. Improvements would support the business case for games as a way to acquire lending customers at lower cost.
Savings, insurance and investment features could diversify revenue and give people further reasons to use GoPay. Closer collaboration with Tokopedia merchants, telecommunications companies and utility providers could extend payment uses while improving information for lending decisions and fraud prevention.
GoTo's central task is to connect its growing payments audience with financial products that customers can use and repay. The strongest evidence of progress will come from engagement, credit quality and profitability improving together.
Key Points
- GoTo plans more minigames to encourage exploration of credit features and small cash loans.
- Third quarter net revenue reached about 4.7 trillion rupiah, up roughly 21 percent, with adjusted profit before tax of about 62 billion rupiah.
- Annual adjusted earnings guidance rose to approximately 1.8 trillion to 1.9 trillion rupiah.
- Financial services revenue grew around 55 percent to nearly 1.5 trillion rupiah, compared with growth of about 10 percent in on demand services revenue to roughly 3.2 trillion rupiah.
- Financial services gross transaction value rose about 30 percent to roughly 170 trillion rupiah, and GoPay passed 500 million monthly transactions in September.
- GoPay processes value equivalent to roughly 3 percent of Indonesia's GDP and reaches around 12 percent of adults monthly.
- GoTo's stake of about 22 percent in Bank Jago supports banking services integrated into GoPay.
- Clear loan costs, affordability checks, data protection and repayment performance are central to responsible expansion.