A S$2,000 holiday purchase can mean S$135 in GST
A traveller returning to Singapore after a week abroad with a bag bought for S$2,000 owes S$135 in Goods and Services Tax (GST), even if the bag was used during the holiday. The calculation is straightforward: subtract the S$500 personal relief from the purchase price, then apply Singapore's 9 percent GST rate to the remaining S$1,500.
Contents
- A S$2,000 holiday purchase can mean S$135 in GST
- How much relief does each traveller receive?
- Which purchases count toward the limit?
- Receipts, gifts and proof of ownership
- How to calculate the GST bill
- Liquor and tobacco have separate rules
- Declare before arrival or use the Red Channel
- What happens when goods are not declared?
- Shopping sent home follows different rules
- Key Points
As of October 31, 2025, the amount of relief depends on how long a traveller has been outside Singapore. An absence of 48 hours or more gives an eligible traveller S$500 in relief. An absence of less than 48 hours gives S$100. GST is payable only on the value above that allowance for qualifying personal goods.
Singapore citizens, permanent residents and tourists are covered by these rules, although certain pass holders and transport crew members are excluded from personal relief. New purchases, souvenirs, gifts and food for personal use count toward the allowance. Goods brought in for business or commercial purposes do not qualify.
Singapore's government information site, Factually, explains the reason in its overseas purchases explainer. It describes GST as a tax on where goods or services are consumed:
GST is a tax on the consumption of goods or services in Singapore.
Goods carried home from an overseas shopping trip are consumed in Singapore, so they fall within that principle. The traveller allowance provides limited relief while keeping the treatment of overseas shopping aligned with purchases made locally. Paying foreign sales tax or value added tax (VAT) overseas does not remove the obligation to pay Singapore GST.
How much relief does each traveller receive?
Singapore Customs sets out the allowances in its GST relief guide. The allowance belongs to each eligible traveller and is based on the time spent outside Singapore before arrival. The relevant total is the value of all qualifying goods that person brings in, rather than the price of each purchase considered separately.
A traveller away for six days who brings back S$800 in personal goods has S$500 in relief. The remaining S$300 attracts GST of S$27. A traveller away for 36 hours who brings back S$1,200 has only S$100 in relief, leaving S$1,100 taxable and a GST bill of S$99.
The difference between the two allowances is S$400: S$500 for an absence of at least 48 hours, compared with S$100 for a shorter trip. Checking the length of a journey is therefore part of working out the shopping budget, particularly for brief visits across the border.
A single item cannot be split to fit the limit. A bag costing S$2,000 remains one purchase when calculating the traveller's taxable total. The allowance reduces the amount subject to GST; it is not a separate allowance for every bag, watch, souvenir or food purchase.
Employment pass, work permit, student pass, dependant pass and long term pass holders, along with transport crew members, do not receive personal GST relief. Travellers in these groups must declare taxable goods and pay GST without deducting the S$500 or S$100 allowance.
Commercial goods are outside personal relief regardless of who carries them. A traveller bringing items into Singapore for sale or another business purpose must treat them separately from shopping intended for personal use. Intoxicating liquor and tobacco also have separate rules.
Which purchases count toward the limit?
New articles, souvenirs, gifts and food for personal use all contribute to the traveller's total. Several modest purchases can therefore produce a tax bill even when no individual item costs more than the allowance. The calculation follows the combined value brought into Singapore.
A second hand item bought overseas also counts. Its value is the price paid in that transaction. Buying an item that another person has already used does not take it outside the rules for overseas purchases.
Gifts belong in the total too. A present received from a friend abroad has a value even though the traveller did not pay for it. Where there is no receipt, Singapore Customs determines that value by reference to identical or similar goods on the open market.
A bag, watch or jacket bought during a trip remains a new overseas purchase for this purpose even after the traveller wears or uses it. The S$2,000 bag used during a week abroad still produces S$135 in GST after the S$500 allowance. Removing tags or packaging to try to avoid checks does not prevent officers from assessing the value.
Items bought at duty free shops in Singapore before departure also count toward the GST relief when they are brought back after the trip. Their purchase location does not remove the need to include them when returning.
Used personal belongings already owned before leaving Singapore are treated differently. They do not count toward the overseas shopping total, provided the traveller can show prior ownership. A camera taken from home and brought back is therefore handled differently from a camera purchased during the holiday.
Receipts, gifts and proof of ownership
Singapore Customs bases GST on the purchase price, so receipts and invoices are central to the calculation. Travellers should keep both paper and digital records, together with proof of payment. Seller emails, online order confirmations and photos can provide useful backup.
A missing receipt does not remove an item's taxable value. Customs can assess purchases and gifts by comparing them with identical or similar goods on the open market. Keeping a record of the price paid is especially useful for second hand purchases, which are valued at their transacted price.
A local purchase receipt or warranty card can help show that a bag, camera or watch belonged to the traveller before departure. Dated photographs taken in Singapore can also help, including photographs containing time and location metadata. Metadata is information stored with a photo that can record when and where it was taken.
Customs officers assess prior ownership case by case. Clear documents reduce the time needed to check whether an item was taken out of Singapore or acquired abroad. Travellers should keep these records accessible alongside receipts for new purchases.
Digital copies can be stored on a phone or in cloud storage. High value items and their documents should be kept together near the top of luggage so that officers can inspect them quickly. Payment confirmations should also be easy to retrieve if a declaration has been completed before arrival.
How to calculate the GST bill
The calculation starts with the total price paid for qualifying personal goods, expressed in Singapore dollars. Deduct the applicable personal relief, then multiply the amount above the allowance by 9 percent. For travellers excluded from relief, taxable goods must be declared without that deduction.
Foreign currency purchases must be converted into Singapore dollars using the exchange rates used by the authorities, which follow rates published by the Monetary Authority of Singapore. Keeping the original invoice makes it easier to identify the currency and purchase amount.
- Six days abroad, S$800 in personal goods: subtract S$500 relief, leaving S$300 taxable. GST is S$27.
- Thirty six hours abroad, S$1,200 in personal goods: subtract S$100 relief, leaving S$1,100 taxable. GST is S$99.
- One week abroad, a bag costing S$2,000: subtract S$500 relief, leaving S$1,500 taxable. GST is S$135, including when the bag was used during the trip.
Foreign VAT or sales tax paid at the shop does not remove the Singapore GST obligation. Receiving a VAT refund overseas also leaves the Singapore requirement in place, because the goods will be consumed in Singapore.
Travellers can keep a running tally of shopping before returning and set aside money for the expected tax. Liquor, tobacco and commercial goods need separate attention because the ordinary personal allowance does not cover them.
Liquor and tobacco have separate rules
Intoxicating liquor and all tobacco products are excluded from the personal GST relief for general shopping. Liquor may qualify for a separate duty free concession, subject to conditions concerning the traveller, the journey and the intended use.
A traveller seeking that liquor concession must be at least 18 years old, have spent 48 hours or more outside Singapore and not be arriving from Malaysia. The liquor must be for personal use. The concessions cannot be used for sale or gifting, and eligibility is checked on arrival.
Typical permitted combinations include up to two litres of wine, one litre of spirits with one litre of wine, or up to two litres of beer. Travellers need to check the applicable combination and their eligibility rather than treating liquor as part of the S$500 or S$100 shopping allowance.
Tobacco and cigarettes have no duty free concession and are always subject to duty and GST. Duty is a separate charge from GST, which is why the rules for these products require attention beyond the calculation for ordinary personal purchases.
Liquor above the applicable allowance must also be declared. Travellers should keep receipts and be ready to present the goods for checks, just as they would for other items requiring a declaration.
Declare before arrival or use the Red Channel
Travellers can declare and pay up to three days before arriving through the Customs@SG web application. All overseas purchases should be included in one submission. Completing the process before reaching the checkpoint allows the traveller to keep the declaration and payment receipt ready.
Once payment is confirmed, the traveller can leave through the Green Channel on arrival and show the digital receipt if asked. Keeping the payment confirmation with the purchase invoices makes any verification quicker.
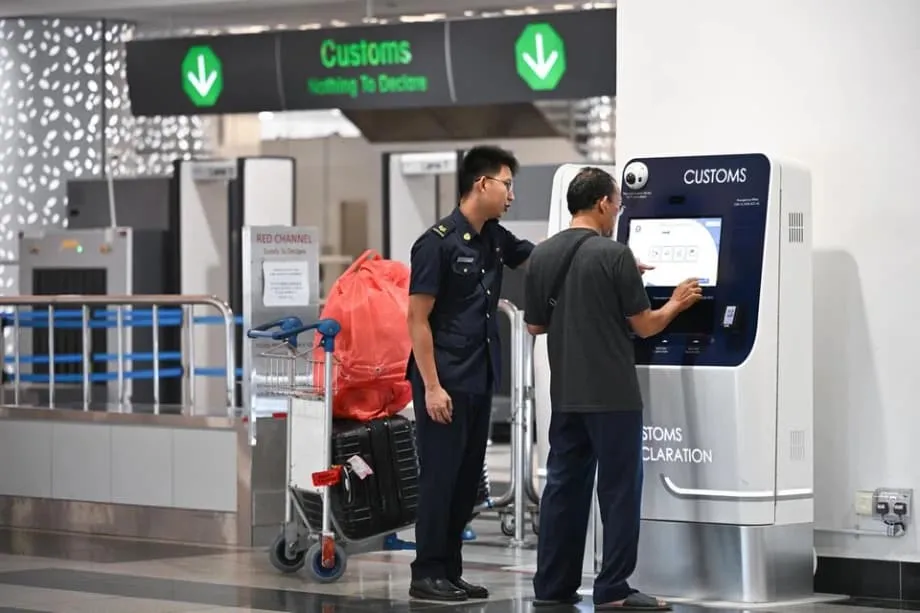
A traveller who has not declared in advance should approach the Red Channel or the Tax Payment Office at the checkpoint to declare and pay there. Receipts, invoices and the items themselves should be accessible for officers to check.
The Inland Revenue Authority of Singapore (IRAS) also provides guidance for travellers bringing goods into the country. Together with the Customs and Factually pages, it provides official information to check before a journey.
Travellers uncertain about an item's treatment should approach the Red Channel or the Tax Payment Office and ask. An accurate declaration avoids the risk of entering without declaring taxable goods and helps prevent delays caused by missing records.
What happens when goods are not declared?
Failure to declare taxable goods, or making an incorrect declaration, can result in a composition amount of up to 20 times the GST due, with a minimum of S$50. A composition amount is a payment used to settle an offence without proceeding to court.
Serious offences under the Customs Act and the GST Act can lead to court penalties. These include a fine of up to S$10,000 or an amount equal to the tax payable, whichever is greater, imprisonment for up to 12 months, or both.
Fraudulent evasion of GST can bring a fine of up to 20 times the amount of tax evaded, imprisonment for up to two years, or both. The possible cost therefore extends well beyond the GST that should have been paid at arrival.
Singapore Customs and IRAS reminded travellers of their obligations in a joint press statement in 2019. The two authorities said responsibility for a complete and accurate declaration rests with the person carrying the goods:
It is the responsibility of travellers to make an accurate and complete declaration of the dutiable and taxable items in their possession. Failure to declare or making an incorrect declaration constitutes an offence under the Customs Act and the GST Act.
Officers conduct selective checks at land, air and sea checkpoints. Enforcement drives often identify cases involving luxury goods, collectibles and liquor exceeding allowances. Keeping receipts and declaring early helps avoid both checkpoint delays and costly penalties.
Shopping sent home follows different rules
Goods imported into Singapore are subject to GST whether travellers carry them personally or they arrive by air or post. The personal relief described here applies to goods carried into Singapore during travel, rather than goods imported through shipping or delivery.
The low value goods regime means GST applies to many purchases from overseas sellers even when their value is relatively low. Travellers arranging delivery should keep order records and details of any GST collected at checkout, instead of applying the luggage allowance to the shipment.
A practical return journey begins with a complete shopping tally, accessible receipts and a check of the relevant allowances. Gifts and second hand purchases should be included, while documents for belongings owned before departure should be kept separately. Liquor and tobacco require their own checks.
Travellers expecting to exceed their relief can use Customs@SG before arrival, retain the payment receipt and pack goods requiring inspection where they are easy to reach. Those who need help can declare at the checkpoint. The essential task is the same in either case: give an accurate account of the taxable goods being brought into Singapore.
Key Points
- Singapore GST is 9 percent on the value of qualifying personal goods above a traveller's relief.
- Eligible travellers receive S$500 relief after at least 48 hours abroad, or S$100 after a shorter absence.
- Employment pass, work permit, student pass, dependant pass and long term pass holders, and transport crew members, receive no personal relief.
- Gifts, souvenirs, food and second hand purchases count toward the total. Using a purchase overseas does not remove it from that total.
- Belongings owned before departure are excluded with proof of prior ownership. Customs values goods without receipts using identical or similar items.
- Liquor and tobacco are excluded from ordinary personal GST relief. Liquor has separate conditional duty free concessions; tobacco has none.
- Declare all overseas purchases in one submission through Customs@SG up to three days before arrival, or declare at the Red Channel or Tax Payment Office.
- Failure to declare can bring a composition amount of up to 20 times the GST due, with a minimum of S$50. Serious offences can lead to court fines and imprisonment.
- Personal traveller relief applies to goods carried into Singapore, not purchases sent by shipping or delivery.