Apparel gains ground as cosmetics lose share
South Korean apparel exports to China rose from $375 million in 2020 to about $545 million in 2024, an increase of roughly 45 percent, according to Korea Customs Service data. As of October 22, 2025, that growth is drawing Korean fashion companies toward a market where their country's beauty brands are reassessing years of expansion.
Contents
- Apparel gains ground as cosmetics lose share
- Why younger shoppers are choosing Korean labels
- The labels building a Chinese presence
- Musinsa and Anta plan a larger rollout
- What local partnerships bring
- How social attention becomes a sale
- Beauty's retreat carries lessons for fashion
- Competition and political risk remain
- What would make the expansion last
- Key Points
Musinsa is preparing its first Musinsa Standard store in mainland China for mid December, backed by a joint venture with Anta Sports. Other labels, including Mardi Mercredi, Marithe Francois Girbaud and Matin Kim, are pursuing Chinese shoppers through distribution partnerships, regional licenses and planned store openings.
Young consumers are central to the push. Korean labels familiar from Seoul's fashionable districts and social media are finding an audience in China's largest cities with clean silhouettes, accessible prices and frequent appearances in celebrity and influencer content. Fashion is taking a larger role in Hallyu, the spread of Korean popular culture abroad.
Korean cosmetics present a different picture. Global exports reached a record during the first three quarters of 2025, yet the United States accounted for 19.6 percent of shipments, ahead of China's 18.6 percent. China represented nearly half of Korean cosmetics exports in 2021. Its share has therefore fallen to less than one fifth, even as Korean beauty products sell more widely around the world.
Beauty companies have responded by closing physical stores in China, concentrating more on online sales and redirecting resources toward North America and Europe. Fashion businesses are entering with those experiences in view, pairing stores with digital retail and seeking Chinese partners that already understand local shoppers.
The shift is changing what Korean companies need from their China operations. Cultural recognition can attract attention, but turning that attention into repeat purchases requires suitable products, dependable service and a retail network that connects a social media discovery with an actual sale.
Why younger shoppers are choosing Korean labels
China's Gen Z consumers are drawn to styles that feel international while remaining easy to adapt to local tastes. Korean streetwear, sportswear and refined basics occupy that space, combining restrained shapes with expressive details.
Frequent product releases keep collections moving. Playful logos appear alongside neat fits and subtle design touches, giving shoppers pieces they can mix with Chinese brands and luxury goods. That flexibility suits consumers who build an outfit across several price levels instead of buying everything from one label.
Korean pop stars help accelerate discovery. An item appearing in an idol's teaser image can prompt searches on Douyin and Xiaohongshu, bringing a garment into a much wider conversation before shoppers encounter it in a store.
Y3K, a futuristic style involving metallic tones and technology inspired clothing, began in Korea and has gained attention in Chinese social feeds. References to the 1990s and 2000s are also popular. Together, those trends give Korean brands several ways to connect with young shoppers whose tastes move quickly.
Earlier Korean fashion demand in China leaned heavily toward recognizable logos. The current wave combines visible branding with practical clothing: T shirts, trousers, outerwear and accessories that can become part of a daily wardrobe. Selling useful staples gives a label more opportunities for repeat purchases and makes it less dependent on one successful item.
Simple designs also provide room for collaborations. Limited graphics and color selections can make a small collection feel distinctive without creating an unnecessarily complicated inventory, the stock a retailer must buy, store and eventually sell.
The labels building a Chinese presence
Mardi Mercredi entered China in 2023 and now has around ten stores through a distribution partnership with Mist Holdings. The arrangement gives the label local support for running shops and handling retail operations.
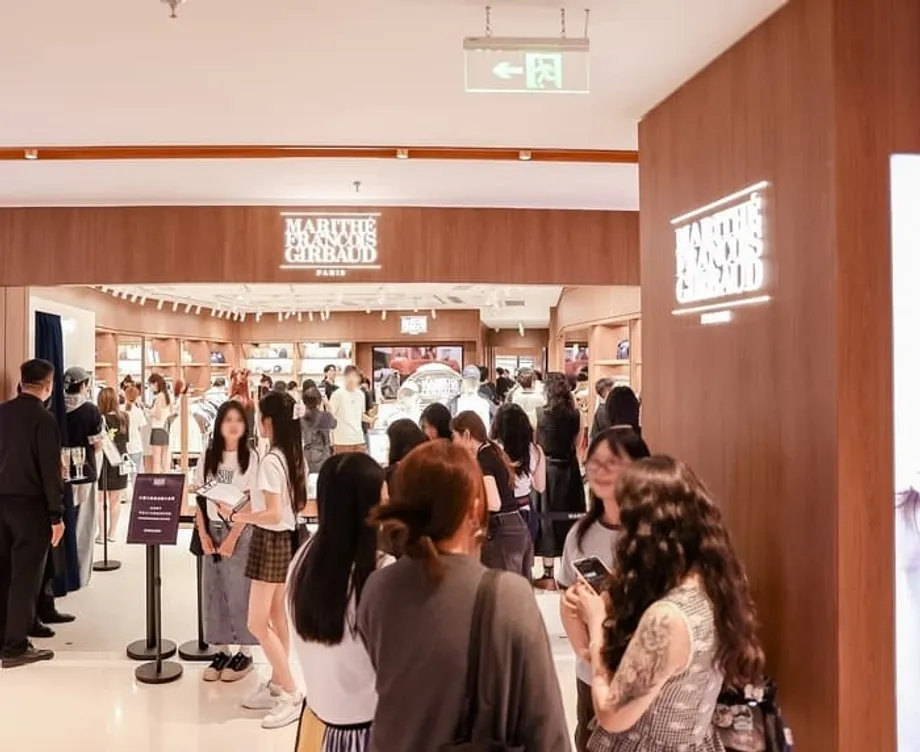
Marithe Francois Girbaud, operated by the Korean company Layer under a license covering Asia, opened its first Shanghai location in July. It plans further openings in major cities. The licensing arrangement allows Layer to operate the brand within the agreed region.
Matin Kim is preparing to enter mainland China after opening outlets in Japan, Hong Kong, Taiwan and Macao. Popular with Gen Z and millennial shoppers across Asia, the label has become a target for Korean retailers competing to secure its China distribution rights.
Matin Kim's annual revenue reached about 128.8 billion won. Operating profit rose to 38.7 billion won from 20.6 billion won, an increase of about 88 percent. Operating profit measures what a business earns from its main activities after operating expenses, before items such as financing costs and taxes.
Musinsa, Kolon FnC, E Land and Misto Holdings are among the companies treating China as a market too consequential to overlook. Their approaches combine prominent flagship stores, spaces selling selected brands and temporary pop ups designed to turn online interest into visits.
Shanghai's Huaihai Road and Anfu Road are important locations in that approach. They attract residents as well as domestic travelers who follow store openings on Xiaohongshu. A shop in a district people already visit for fashion can act as both a sales outlet and a visible introduction to a brand.
Musinsa and Anta plan a larger rollout
Musinsa, South Korea's leading fashion platform and the owner of Musinsa Standard, is entering China through a joint venture with Anta Sports. Musinsa holds 60 percent and management control, while Anta holds 40 percent and contributes its distribution reach and retail experience.
The first Musinsa Standard store in China is scheduled to open in mid December at Parkson Shopping Mall on Shanghai's Huaihai Road. Covering about 1,300 square meters, it will connect with a Tmall flagship so customers can move between online shopping and the physical store.
A multibrand Musinsa Store is also planned for Anfu Road, a neighborhood known for pop ups and retail focused on design. No opening date was given for that location. Musinsa's wider goal is more than 100 China stores by 2030 and over 1 trillion won in cumulative sales, meaning sales added together over the expansion period.
Chinese customers already account for part of Musinsa Standard's business in South Korea. In May, they represented 18.4 percent of purchases by foreign customers at its stores, giving the company a measure of interest before its mainland launch.
Anta brings experience managing large brand portfolios and one of China's strongest retail networks. Its contribution includes merchandising, logistics and operations that connect different shopping channels. The partnership also reflects the growing overlap between sportswear and lifestyle clothing, as athletic influences become part of everyday dress.
Wu Yonghua, co CEO of Anta Sports, said the partnership would combine fashion and sport to reach younger Chinese consumers:
By integrating sportswear with fashion forward design, we aim to better meet the preferences of China's younger generation. Leveraging our full value chain capabilities and proven Brand plus Retail operating model, Anta Sports will empower Musinsa China to introduce Musinsa Standard and Musinsa Store to the market.
Joonmo Park, CEO of Musinsa, described the venture as a way to combine the companies' capabilities, reach shoppers through different retail channels and support more Korean designers in China:
This partnership will combine Musinsa's experience in fashion with Anta's brand and retail management capabilities to tap into various retail channels and deliver differentiated brand experiences to Chinese consumers. We look forward to capturing the attention of young consumers in the dynamic Chinese market.
What local partnerships bring
Kolon Sport's experience offers a concrete example of growth through a Chinese partner. It established Kolon Sports China with Anta in 2017, and revenue in China rose from about 70.3 billion won in 2021 to 503.2 billion won in 2024. The later figure is roughly 7.2 times the earlier one.
The arrangement combines local store management, access to retail properties and marketing knowledge with Korean responsibility for brand identity and product development. For a company entering unfamiliar cities, those functions affect everything from where a shop opens to which products appear inside it.
Mardi Mercredi's distribution partnership and Layer's regional license offer other routes into the market. Such arrangements allow brands to expand without first building an entire network of their own, while learning how often customers return and how preferences differ between cities.
The key dates show how the current push developed:
- 2017: Kolon Sport established Kolon Sports China with Anta. Political friction following the deployment of a missile defense system in South Korea also affected Korean businesses.
- 2020: South Korean apparel exports to China totaled $375 million.
- 2021: China accounted for nearly half of Korean cosmetics exports, while Kolon Sport's China revenue was about 70.3 billion won.
- 2023: Mardi Mercredi entered China.
- 2024: Apparel exports to China reached about $545 million, and Kolon Sport's China revenue reached 503.2 billion won.
- July 2025: Marithe Francois Girbaud opened its first Shanghai location.
- Mid December 2025: Musinsa Standard's first China store is scheduled to open.
- 2030: Musinsa aims to have more than 100 China stores and over 1 trillion won in cumulative sales.
How social attention becomes a sale
Tmall and JD provide large online marketplaces, while WeChat supports customer communities, individual conversations and service. Xiaohongshu and Douyin help shoppers discover styles, compare reactions and judge whether an item fits the image they want.
Creators known as key opinion leaders, or KOLs, influence that process by introducing products and helping establish trust. Collaborations, short videos and limited releases can bring a label into view, but the next steps depend on Chinese language content, responsive customer support and fast fulfillment.
Korean companies can adapt experience gained at home, although China's platforms have their own pace and expectations. Local teams help brands respond to those differences, including the way shoppers use live streams and chat to ask questions before buying.
Fit, sizing and prices also need to suit Chinese customers. A garment that attracts interest online still has to work when it arrives, and a store must be able to provide the right sizes and replacements. Connecting online stock with physical shops makes that process easier for customers moving between the two.
Musinsa's use of data to identify trends and plan stock offers one way to manage rapid changes in demand. Buying too much of a fading style leaves a retailer with unsold goods and pressure to discount. Tracking demand and replenishing popular products can reduce that exposure.
Fashion companies therefore need several parts of the operation to work together: marketplace sales, social content, customer service, inventory and delivery. A popular post creates an opportunity; retail execution determines whether the customer completes a purchase and comes back.
Beauty's retreat carries lessons for fashion
Korean beauty companies encountered political friction, stronger Chinese competitors and changing consumer sentiment. Following the deployment of a missile defense system in South Korea in 2017, China informally restricted some Korean cultural content.
Chinese beauty brands also became more capable and faster at bringing products to market, in some cases moving from an idea to launch within a few months. Counterfeit products damaged trust in certain product lines, while the cost of promotional spending increased.
The change in export destinations illustrates how the business has shifted. In the first three quarters of 2025, the United States took 19.6 percent of Korean cosmetics shipments and China 18.6 percent, a gap of one percentage point. Korean beauty's global export record now sits alongside a much smaller dependence on China than in 2021.
Some major Korean beauty businesses have closed physical stores in China and moved to selling only online. One large household goods and beauty group recorded its first quarterly loss in about 20 years during the second quarter of 2025, showing the financial pressure behind changes to its business.
Some Korean beauty lines have recently shown signs of stabilization in China through Douyin live commerce and products relaunched for local customers. Live commerce combines a video presentation with the ability to buy during the broadcast, shortening the distance between seeing a product demonstrated and ordering it.
Fashion companies are taking practical lessons from that experience: use several sales channels, build communities within Chinese apps, protect consistent pricing and keep launch schedules flexible. Celebrity endorsements can attract attention, but dependable service, suitable fit and customer relationships give shoppers reasons to return after an endorsement campaign ends.
Competition and political risk remain
Chinese fashion and sports groups have nationwide networks, broad brand portfolios and strong positions in malls and on digital platforms. Many leading retailers are domestic, and pride in Chinese brands gives local competitors another source of support.
Korean labels must compete for both shelf space and attention in social feeds. Products need to suit local climates, sizes and color preferences, while prices must remain accessible enough to attract shoppers without weakening the brand's value.
Heavy discounting creates a particular challenge. It can move stock quickly, but repeated promotions can encourage customers to wait for a lower price. Retailers need stock to sell at a pace that matches demand without making markdowns their main selling tool.
Advertising, labeling and data rules also require attention. Intellectual property enforcement has improved compared with a decade ago, yet brands still need to monitor trademarks, similar looking products and marketplace listings.
Political conditions remain part of the calculation. A previous attempt by a major Korean casual label to expand in China fell short during a period of political friction. Companies in the current wave are using joint ventures, licensed operations and pilot stores to test demand while limiting their financial exposure.
China's extensive online retail market provides room to try different approaches. Physical stores add fitting, service and a place to experience the products directly. Combining the two reduces dependence on any single sales channel, while keeping each channel responsible for a different part of the customer relationship.
What would make the expansion last
Shanghai's opening crowds will provide visibility, but repeat purchases and the proportion of visitors who buy will give companies more useful measures of demand. Customer lifetime value, the amount a customer spends over the course of a relationship with a brand, helps distinguish a brief burst of interest from a durable business.
Core products need to sell steadily, with stock replenished at the right time and discounts kept under control. Live commerce that sells goods without large incentives would indicate that shoppers value the product itself. Collaborations with Chinese creators and brands also need to fit the label and local culture.
Chinese shoppers visiting Musinsa Standard in South Korea already provide a connection between the two markets. A customer who later finds familiar fit and quality in Shanghai could carry that relationship across borders and between online and physical stores.
Musinsa's December launch and its 2030 goals will put that approach into practice. Other Korean labels are testing related models, using licenses where a regional operator offers the right capabilities and retaining greater control where their operating approach is established.
The opportunity is concrete: apparel exports have grown, several labels are opening stores, and a major Chinese retail partner is supporting Musinsa's entry. Sustaining that growth will depend on turning cultural interest into clothing that customers choose, wear and buy again.
Key Points
- South Korean apparel exports to China rose about 45 percent, from $375 million in 2020 to roughly $545 million in 2024.
- The United States received 19.6 percent of Korean cosmetics exports in the first three quarters of 2025, ahead of China's 18.6 percent.
- Musinsa holds 60 percent of its China joint venture with Anta Sports, which holds 40 percent.
- The first Musinsa Standard store in China is scheduled for mid December in Shanghai, with more than 100 China stores targeted by 2030.
- Mardi Mercredi has around ten China stores, Marithe Francois Girbaud opened in Shanghai in July, and Matin Kim is preparing mainland entry.
- Kolon Sport's China revenue increased from about 70.3 billion won in 2021 to 503.2 billion won in 2024.
- Local partnerships, digital sales, suitable products and repeat purchases are central to the fashion expansion.