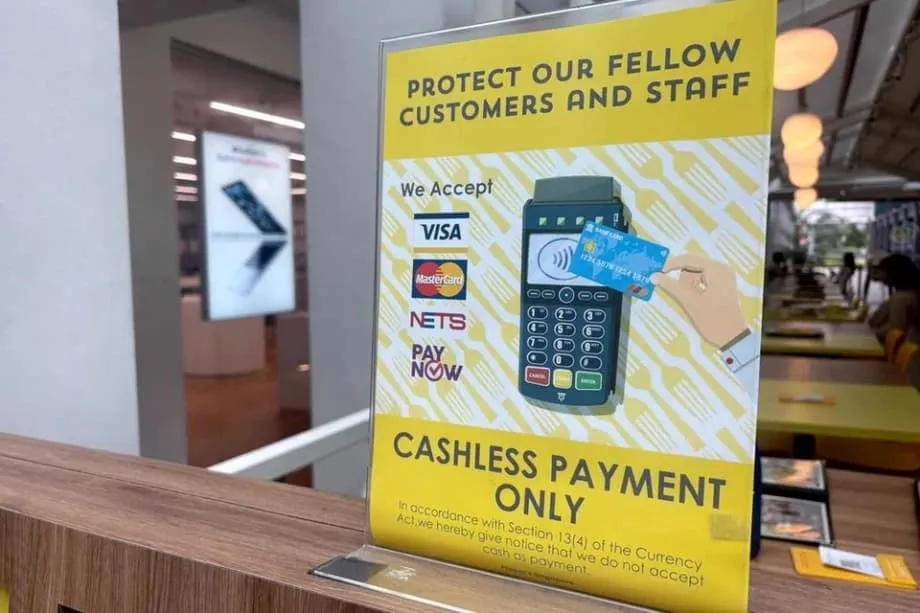
A faster checkout can leave some customers unable to pay
About one in seven shops checked across several central Singapore malls accepted only payments other than cash, reflecting a change that makes shopping easier for many people but leaves others unable to buy everyday items. Tea chains, bakeries and fast casual food kiosks are among the businesses moving entirely to cards, QR codes or mobile wallets.
Contents
- A faster checkout can leave some customers unable to pay
- How coins gave way to QR codes
- Why retailers want to stop handling cash
- Teenagers can have pocket money but no accepted card
- Seniors and workers face different barriers
- High adoption still leaves a place for cash
- What happens when a bank or network goes down?
- Can a Singapore shop refuse cash?
- What other countries show about keeping access open
- Payment options for students, seniors, workers and visitors
- What to Know
As of October 15, 2025, the spread of cashless only counters presents a practical problem for teenagers without their own cards, seniors who find digital payments difficult or risky, and some migrant workers and domestic helpers without suitable local accounts. Having enough money is no longer always enough to complete a purchase. Customers also need a payment method the shop accepts.
Singapore's shift accelerated during COVID-19, when hygiene and speed became priorities. Many retailers kept their new arrangements after pandemic restrictions ended. Years of investment in PayNow, the national SGQR standard and support for smaller merchants had already made digital payments easier to introduce.
Retailers see advantages in shorter queues, fewer mistakes with change and less work counting money or taking it to the bank. Customers who depend on notes and coins can instead face an embarrassing refusal at the counter, a search for another shop or a request for someone else to pay.
Cash remains part of daily life for a sizeable share of consumers, particularly for small purchases and budgeting. Singapore's experience therefore involves two changes happening at different speeds: businesses are reducing cash handling, while some customers still need or prefer it. Banking and network disruptions add another reason for shops and shoppers to keep alternatives ready.
How coins gave way to QR codes
Cash only signs were once familiar at coffee shops and small stalls. Today, QR stickers, contactless card readers and mobile wallets are standard at most counters. These tools let customers pay by scanning a code or tapping a card or phone instead of handing over notes and waiting for change.
Singapore launched its national QR standard, SGQR, in 2018. It brought multiple payment schemes together in one code, allowing merchants to accept different supported apps without displaying a separate code for each. That reduced clutter at the counter and simplified acceptance for businesses.
Banks also introduced instant transfers using a mobile number through PayNow. Payment providers competed on fees, while grants helped smaller businesses adopt terminals and QR readers. Together, those changes lowered the barriers for merchants that had previously hesitated to buy point of sale systems, the equipment used to record sales and take payments.
The change unfolded over several stages:
- Before the pandemic, cash only policies remained common at coffee shops and small stalls.
- In 2018, Singapore introduced SGQR to combine multiple payment schemes in a single code.
- During COVID-19, concerns about hygiene and the need for quick transactions accelerated digital adoption.
- By October 15, 2025, cashless only policies had become visible across food and retail outlets, although some branches continued accepting cash for particular customer groups.
Some global coffee outlets accept only cashless payments at selected Singapore branches while retaining cash at locations serving tourists or elderly regulars. Smaller chains have also gone fully digital except at outlets with many students who may not yet have cards. Those exceptions show how payment policies can vary even within the same business.
Why retailers want to stop handling cash
Store operators describe quicker checkout as a central benefit. Digital payments reduce the time spent calculating and handing over change, helping queues move during the lunchtime rush. Fewer calculations also mean fewer opportunities for mistakes.
Cash requires work beyond the sale itself. Shops need a cash float, meaning a supply of notes and coins for change. Staff must count takings at the end of the day and arrange bank deposits. Removing cash can eliminate those tasks and make reconciliation easier, allowing businesses to match payment records with recorded sales.
Less money in the drawer also reduces losses from theft. For food handlers, avoiding notes and coins became a hygiene selling point during the pandemic and remained attractive afterward.
Payment costs matter particularly to hawkers, kiosks and very small businesses operating on narrow margins. Accepting payments through QR codes often carries lower merchant charges than traditional card networks. The financial case therefore depends partly on which digital methods a business chooses, alongside the time and effort it saves handling cash.
A large portion of small businesses have reduced or removed cash handling at the counter. Owners cite faster checkout, easier reconciliation and lower risk. Customers, however, say they will go elsewhere when they cannot pay in their preferred way. A simpler routine for a shop can come with lost sales when its payment options do not match its customers.
Teenagers can have pocket money but no accepted card
Teenagers who receive pocket money in cash can find themselves excluded from shops they previously used. Students under 16 often do not have personal debit cards. A debit card lets someone pay using money held in an account, but access to an appropriate account and card is uneven among younger students.
Some teenagers can use school linked payment tools or youth wallets with parental approval. Those arrangements do not reach everyone or work at every merchant. Students describe being unable to buy a drink at a favourite cafe or purchase a cinema ticket with friends after payment policies changed.
Many teenagers say they intend to get their first bank card when they become eligible at 16. That still leaves a gap during the younger secondary school years, when students may be making independent purchases but remain dependent on cash or a parent's payment arrangements.
Seniors and workers face different barriers
Older residents who have used cash for decades can find a cashless only counter stressful. Setting up PayNow or adding a card to a phone wallet involves unfamiliar steps. Some seniors worry about scams and prefer the certainty of handing over notes and coins.
A queue can make the experience harder. Being told that cash is unacceptable may feel embarrassing, especially when other customers are waiting. Some seniors say they would return to shops that still take cash. Others want patient guidance so they can learn without the pressure of a busy counter.
Migrant workers and domestic helpers face a different mix of obstacles. Many migrant workers receive wages in bank accounts and can make QR payments. Some domestic helpers, however, do not have local debit cards, while others prefer cash to manage their spending and the money they send home.
Some customers ask strangers to make a digital payment and then reimburse them in cash. That arrangement can be awkward and is not always safe. Limited mobile data or an older phone can also make wallet apps and authentication steps difficult to use. Authentication is the process an app uses to check that the person making a payment is authorised to do so.
The common problem is access at the moment of purchase. A teenager may lack a card, a senior may lack confidence with an app, and a worker may lack a compatible account or reliable phone connection. Each can reach the same counter with money available but no straightforward way to pay.
High adoption still leaves a place for cash
Singapore has one of Southeast Asia's highest levels of cashless payment adoption. Most merchants, from large retailers to small businesses, accept at least one digital method. Cards remain the most common payment choice for many shoppers, while PayNow transfers and QR payments at stalls have become routine.
Survey findings show younger consumers adopting digital tools fastest, with some leaving home carrying only a phone. At the same time, a sizeable share of people continue to use cash for everyday purchases. For some, notes and coins make it easier to keep track of a spending limit.
The checks finding about one in seven shops accepting only cashless payments covered several central malls. Across the wider retail market, the growing availability of digital payments sits alongside continued consumer demand for cash. The friction is especially visible when a customer reaches a food court or mall outlet and discovers that the method they brought is no longer accepted.
What happens when a bank or network goes down?
Singapore has experienced several high profile banking disruptions in recent years. QR transfers, wallet top ups and some card transactions failed for hours. Merchants operating entirely without cash reported lost sales and frustrated queues, while shoppers relying on one app had to find another way to pay.
A cashless only shop becomes vulnerable when every accepted payment depends on a service that stops working. Keeping several payment routes, such as cards and PayNow QR, reduces dependence on a single provider. Different digital methods give staff and customers alternatives during a disruption.
Cash can provide another backup. A small float allows a shop to handle exceptions when electronic payments fail. Where practical, stored value options that can work offline may help with small purchases. These options hold money paid in advance, as transit linked cards do.
Food operators can also prepare a temporary manual system, recording orders and settling bills after services return. That requires clear procedures and prompt reconciliation so staff and customers agree on what is owed. Training staff to handle incidents calmly can help prevent confusion during a busy service period.
A more resilient payment setup can include:
- More than one digital route, such as cards alongside PayNow QR.
- A small cash float, with clear rules on when staff should use it.
- Stored value options that can work offline, where practical.
- A temporary process for recording orders and collecting payment once systems recover.
- Clear signs explaining accepted methods and arrangements during disruptions.
- Prompt reconciliation of exceptions and reviews of incident records to improve procedures.
Can a Singapore shop refuse cash?
Singapore retailers generally may choose which payment methods to accept, provided they inform customers. Notes and coins have legal tender status, meaning the central bank recognises them for settling debts. Private shops can still set payment conditions for purchases, which is why both cash only and cashless only signs exist.
Public services, including transport, operate under their own payment policies. Transport fares and top ups have moved steadily toward digital methods. Businesses in areas with many tourists tend to retain cash because visitors may not have access to local wallets.
Government agencies continue to support digital adoption while helping people who find it difficult. Grants have helped smaller businesses install terminals and accept QR payments. SGQR has simplified the process for merchants and customers.
Digital ambassadors and community centres run lessons for seniors on using banking apps and recognising scams. Schools and banks provide youth accounts and tools for tracking spending. These programmes aim to help people join the digital payment system as its use becomes more common.
Singapore has not adopted the approach used in some US cities, where shops must accept cash to avoid excluding residents without bank accounts. Its approach instead combines merchant choice with public education and support for digital access.
What other countries show about keeping access open
Sweden moved rapidly toward digital payments, then required banks to maintain access to cash services in each region. That response addressed the needs of rural communities and older residents who could otherwise struggle as cash use declined.
China's super apps made QR payments an everyday tool across age groups by connecting payments with services people routinely use. Japan has promoted digital salary payments and a national cashless programme, but adoption remains mixed. Many Japanese businesses prefer familiar routines and worry about system costs.
India's Unified Payments Interface, known as UPI, created a free, instant network that allows transfers between bank accounts. Its ability to work across participating services made a QR code and phone useful to small merchants and ordinary customers. The network grew to handle billions of transactions each month.
These experiences point to practical choices for Singapore: keep payment acceptance simple for small businesses, make digital access safe and affordable for households, and retain alternatives when technology fails or customers cannot use it. Access to cash services, familiar apps and low costs address different parts of the same everyday task of paying for something.
Payment options for students, seniors, workers and visitors
Teenagers can ask a parent or guardian about youth bank accounts that provide a debit card at age 16. Before then, a student wallet linked to a parent's account or a school programme may allow contactless payments in canteens and at selected merchants. A small amount of cash remains useful if an app fails or a shop accepts cash only.
Students using QR payments should check that the code belongs to the merchant and verify the payee's name before sending money. Those checks help them confirm where their payment is going.
Seniors can begin with one trusted banking app and one payment method, such as PayNow using a mobile number. Practising with a family member at a quiet time removes the pressure of learning in a queue. Strong passwords, transaction alerts and avoiding payment links from strangers can help make the process safer and easier to check.
Keeping some notes provides a backup for clinics, market stalls and other purchases. A senior who is not ready to pay by phone can ask staff for help or use a nearby shop that accepts cash while building confidence.
Migrant workers and domestic helpers can open a local bank account where possible and activate mobile banking alerts. For someone who does not want a credit card, a prepaid debit card may be an option, with an employer adding money through PayNow or a bank transfer. Transit stored value cards are widely accepted for travel and some small purchases and can be topped up at machines.
Workers sending money home can compare digital remittance fees and carefully confirm recipient details before making a transfer. Keeping everyday spending and remittance needs in mind helps them choose payment arrangements that suit both.
Tourists can carry some Singapore dollars for businesses that accept only cash or apply minimum spending rules to card payments. International cards are widely accepted at malls and attractions. Many stalls take QR payments, but customers usually need a compatible local wallet linked to a bank account.
A transit stored value card can cover public transport and some convenience purchases. Visitors who reach a cashless only shop without a suitable payment method can ask staff for directions to an ATM or another store that accepts cash.
What to Know
- Checks across several central Singapore malls found about one in seven shops accepting only cashless payments.
- Speed, hygiene, simpler accounting and reduced cash handling have encouraged retailers to go digital.
- SGQR, launched in 2018, and PayNow helped make digital acceptance easier for smaller businesses.
- Teenagers without cards, seniors uncomfortable with apps and some migrant workers and domestic helpers face barriers at cashless only counters.
- Cash remains useful for small purchases, budgeting and backup during payment disruptions.
- Retailers generally can choose accepted payment methods if customers are informed.
- Multiple digital methods, a cash float and clear incident procedures can help shops continue serving customers during outages.
- Youth payment tools, patient training, suitable accounts and stored value cards can help customers access more payment options.