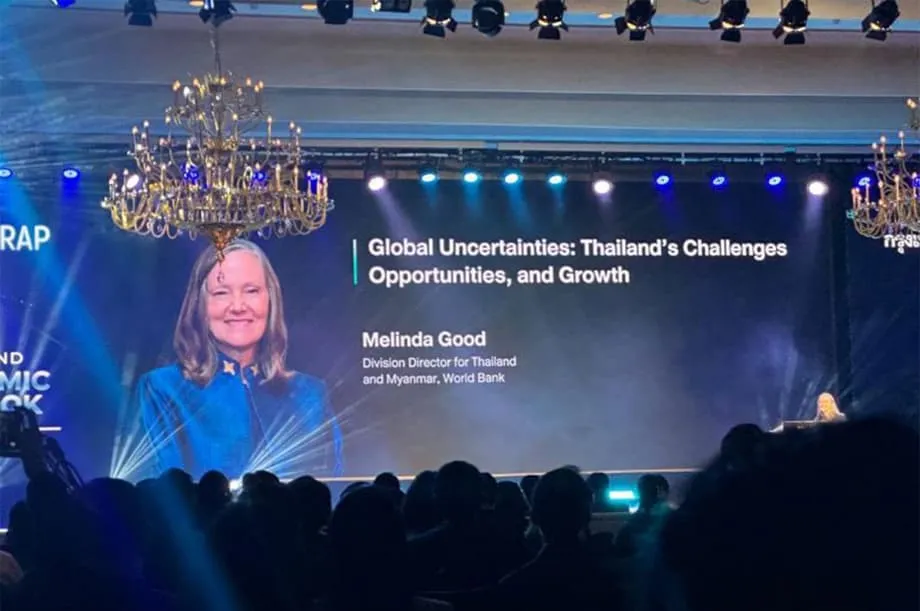
Thailand faces a choice over its next stage of growth
Thailand needs new engines of growth to reach high income status by 2037, the World Bank says, as economic expansion near 2 percent falls short of the roughly 5 percent pace often cited as necessary to achieve that ambition. Its prescription brings together greener production, digital businesses and more competitive services, supported by better skills and infrastructure.
Contents
- Thailand faces a choice over its next stage of growth
- Why the existing growth model is losing momentum
- A reform agenda linking workers, businesses and cities
- Digital connections need a workforce able to use them
- Helping startups and smaller firms compete
- Climate risks bring a large economic bill
- Cleaner production could become a larger export engine
- Opening services beyond traditional tourism
- Government plans meet limits on monetary support
- Trade pressures and the milestones ahead
- Key Points
The challenge, as of October 15, 2025, is to move beyond a model built on tourism, manufacturing with low production costs and steady trade. Those activities remain important, but the World Bank argues that they cannot carry the country far enough in an economy increasingly shaped by digital technology, knowledge and climate pressures.
Melinda Good, the World Bank's division director for Thailand and Myanmar, described why the country needs a different approach.
What got Thailand here will not get it there.
The institution identifies five promising sectors: digital services, advanced and green manufacturing, agribusiness under a renewed Kitchen of the World ambition, sustainable and wellness tourism, and the creative economy. Developing them requires more open markets, stronger competition, faster improvements in skills and investment that protects communities and businesses from floods and water shortages.
Bangkok will host the IMF and World Bank Annual Meetings in October 2026, bringing global investors and corporate leaders to Thailand. The gathering gives the country an opportunity to demonstrate progress on economic reform, cleaner energy and workforce development. The practical stakes extend beyond investment announcements: Thailand needs businesses that can produce more valuable goods and services, pay better wages and withstand disruption.
Why the existing growth model is losing momentum
Thailand's difficulties fit what economists call the middle income trap. Countries can grow quickly as they move out of poverty, then slow before reaching high income because productivity, innovation and workforce development fail to keep advancing. Productivity means how much workers and businesses produce with the resources they use.
Thailand's productivity growth has slowed, private investment has weakened and its population is aging. Fewer available workers make expansion harder, while an older population increases pressure on public finances. Learning outcomes trail regional leaders, research and development spending remains modest, and services are relatively closed compared with those in other Southeast Asian economies.
Financial conditions add to the strain. Bank credit growth has turned negative for the first time in many years, reflecting weak borrowing demand and tighter lending standards as bad debts rise. Analysts have lowered growth forecasts amid trade tensions and softer tourism flows. Rising nonperforming loans, meaning loans whose repayments are seriously overdue, also make banks more cautious.
The Bank of Thailand has argued that interest rates alone cannot resolve these problems. Deputy Governor Piti Disyatat described the limits of monetary policy and the committee's effort to avoid holding back activity.
Monetary policy can only do so much, and the committee aims to ensure it does not constrain growth.
The central bank and the World Bank share a central message: measures that support spending now need to be accompanied by changes that improve what the economy can produce over time. Lower borrowing costs and temporary stimulus have limited power to resolve weak skills, restricted competition or unreliable infrastructure.
A reform agenda linking workers, businesses and cities
The World Bank's Systematic Country Diagnostic Update for Thailand sets out five priorities: stronger human capital, a more competitive and innovative economy, growth in secondary cities, development that can withstand climate risks, and stronger fiscal institutions and public finance. Together, they aim to raise productivity, reduce inequality and improve resilience to shocks.
Human capital means the education, skills and health that enable people to work productively. The World Bank recommends higher education spending that is better targeted, curricula more closely connected to employers' needs and extensive retraining to close digital and technical gaps. Vocational courses linked to industry, short qualifications for working adults and incentives for companies to train employees form part of that agenda.
Better childcare, health care and elder care could also help more people enter or remain in paid work, particularly women. For an aging country, expanding participation in the workforce can ease pressure on employers while improving household incomes.
Secondary cities are another part of the plan. Better transport, dependable water and electricity, and investment plans designed around local needs could attract firms beyond established economic hubs. Stronger skills would help regions outside Bangkok compete for quality jobs rather than leaving the most valuable opportunities concentrated in the capital.
Those improvements depend on transparent, accountable public finance and coordination between central and local government. Stronger fiscal institutions, the rules and organisations that manage public money, can help deliver services, narrow regional gaps and encourage private investment. Flood and drought protection is especially important in the Eastern Economic Corridor, where water systems serve both industrial operations and surrounding communities.
Digital connections need a workforce able to use them
Thailand already has substantial digital infrastructure. Mobile broadband is widespread, PromptPay provides a popular instant payment system, and a national digital ID has improved access to services. Global cloud providers are investing in data centers, creating an opening for Thailand to become a regional services hub.
Skills are the main constraint. Only about 5 percent of Thais have intermediate digital skills, despite strong connectivity. The limited share of people with intermediate or advanced abilities makes it harder for businesses to adopt technology, use artificial intelligence and expand digital operations.
The World Bank's proposed response combines school reform with training for adults. Universities, technical colleges and private bootcamps could provide short qualifications that workers can build on over time. Relevant subjects include software, data analysis, design, cybersecurity, robotics maintenance and green technology.
Employers could expand pathways that let people earn while learning at work. Scholarships and stipends for workers changing direction during their careers could help people with lower incomes take part. Strong foundational learning and digital fluency would support automation and make Thailand more attractive to investors seeking dependable pools of talent.
The opportunity extends beyond technology companies. More capable workers could support precision manufacturing, agriculture that uses technology to respond to climate conditions, and services sold across borders, including cloud computing, data, design, gaming and health care.
Helping startups and smaller firms compete
Thailand's digital startups could attract up to $1.8 billion in venture capital annually if the business environment improves, the talent pool grows and policy supports innovation. Venture capital is investment in young companies seeking to expand. The estimate depends on changes that give businesses both the skills and the conditions needed to grow.
The World Bank calls for stronger competition rules, simpler business licensing and better access to finance for startups and small and medium enterprises. Public research funding and tax incentives for research and development could encourage companies to create more valuable products and improve production processes.
Investor protections, clearer regulation and capital market changes that support funds investing in young businesses would also help. Easier rules for stock options, which allow employees to obtain shares in their company, could support growing firms. Fair enforcement of competition rules would give new entrants a better chance to challenge established businesses.
Predictable rules on data, privacy and services traded across borders are important for digital exporters. A modern framework for cloud computing and data centers would support an area already attracting foreign direct investment. Combined with more open services trade, those changes could help Thai companies sell digital content, software and business services across ASEAN and beyond.
Climate risks bring a large economic bill
The World Bank's Country Climate and Development Report warns that floods, heat stress, water shortages and coastal erosion could reduce Thailand's GDP by 7 to 14 percent by 2050 without stronger adaptation. GDP measures the value of goods and services produced in an economy. Damage to farms, factories, infrastructure and workers' ability to operate in extreme heat can reduce that output.
Research points to agricultural production losses reaching several billion dollars and substantial risks to fisheries as hotter seas damage ecosystems. Cooling needs could cost $11 billion to $17 billion a year by the middle of the century. Major floods can remove several percentage points from annual GDP, while coastal erosion creates rising costs for cities and tourism.
Continued deforestation would worsen flooding and erosion while reducing natural capital, the forests, land and ecosystems that support economic activity. The World Bank's agenda therefore connects water management, land use and environmental protection with the country's growth ambitions.
Practical measures include early warning systems, strict enforcement of land use rules, reforestation and green infrastructure that manages stormwater. Better water and land management can reduce disaster losses and increase farm yields. A focused adaptation programme could cut damage and increase national wealth, with adaptation spending potentially running at about 1.6 percent of GDP.
The Eastern Economic Corridor illustrates the economic value of water security. Systems that keep households supplied and factories operating through dry periods and sudden storms also give investors greater confidence that production can continue. Climate resilience therefore belongs alongside transport, power and skills in Thailand's investment planning.
Cleaner production could become a larger export engine
Thailand already exports efficient air conditioners, participates in the global solar photovoltaic supply chain and is developing an electric vehicle production base. Green products nevertheless remain a small portion of total exports. The World Bank sees room to turn those existing strengths into a larger source of growth.
Lower trade barriers, adjusted tariffs, faster permits and stronger skills could help green exports reach about 23 percent of GDP by 2030 under supportive policies. That figure describes their potential value relative to the economy, rather than their share of all exports. The opportunity includes better jobs, stronger energy security and more firms developing climate technology.
Cleaner electricity and transport can reduce energy costs over time and improve air quality. Carbon pricing, which places a cost on emissions, and steady investment could support Thailand's path toward carbon neutrality by 2050 and net zero by 2065. Both goals involve balancing emissions with removals, with net zero extending across greenhouse gases.
Meeting adaptation and emissions reduction goals would require an estimated $219 billion over the next 25 years, equivalent to roughly 2.4 percent of cumulative GDP over that period. Public budgets, revenue from carbon pricing and private capital would all be needed. The spending covers both protection from climate damage and changes that reduce emissions.
Opening services beyond traditional tourism
Services are the fastest growing part of the global economy and include finance, health, education, logistics, cloud computing, content and business processes delivered digitally. Thailand's relatively closed services market limits opportunities to bring in capital, knowledge and competition that could improve quality and lower prices.
The World Bank advocates easing foreign ownership limits in selected activities, simplifying permits and negotiating trade agreements with deeper commitments on services. Practical changes include simpler licensing for professional services, predictable rules for data moving across borders, faster health and education investment approvals, and updated logistics and electronic commerce frameworks.
Thai entrepreneurs could then develop businesses for regional customers rather than mainly serving the domestic market. Potential beneficiaries include telemedicine, elderly care, digital design studios and financial technology, areas where Thailand already has talent and customers.
Melinda Good, the World Bank's division director for Thailand and Myanmar, described the opportunities across production and services.
Thailand must go green, go digital, become the Kitchen of the World, lead in digital services, and build high value service sectors.
Tourism remains part of that strategy, with a greater focus on quality, infrastructure and services. Health and wellness travel, along with ecological tourism connected to conservation, could attract visitors who spend more and support small businesses across the country. The creative economy is also among the five sectors identified for future growth.
Government plans meet limits on monetary support
Finance Minister Pichai Chunhavajira has outlined five pillars for reshaping Thailand's economy. They cover production in future industries such as electric vehicles and green energy, higher agricultural productivity through modern techniques, better tourism infrastructure and services, critical infrastructure including water management and logistics, and human capital development.
The fiscal framework allocates money to job creation and competitiveness programmes, with a planned budget deficit intended to support growth while keeping debt manageable. Public debt stands near 60 percent of GDP, a level authorities say can be stabilised through stronger growth.
Policymakers are preparing carbon standards and credit systems to guide the clean transition. They are also developing debt restructuring tools and targeted relief for small debtors, aiming to protect vulnerable households during economic change without delaying necessary restructuring.
The Bank of Thailand has lowered its policy rate in recent moves to 1.5 percent. Officials say further cuts would require a clear and material deterioration in the outlook or an unexpected shock. Soft inflation, shrinking credit and rising bad loans point to an economy needing immediate support alongside changes that raise productivity.
Deputy Governor Piti Disyatat also expressed the central bank's intention to avoid restraining activity.
The committee aims to ensure it does not constrain growth.
The government's investment agenda and the central bank's position address different parts of the problem. Interest rates affect financing conditions, while education, competition, infrastructure and services reform determine how much businesses can expand and improve their output.
Trade pressures and the milestones ahead
Trade tensions and tariffs imposed by major partners threaten exports and growth, with some scenarios pointing to weaker performance in the second half of 2025. Tourism has recovered unevenly across visitor markets, and Chinese arrivals may take time to regain their previous peaks.
Those pressures strengthen the case for a wider range of trade agreements, particularly agreements covering services, digital trade and investment. Predictable rules for data and digital services could help Thai firms expand regionally. Thailand's location in Southeast Asia remains an advantage, while the Eastern Economic Corridor could strengthen its role in advanced manufacturing and logistics if infrastructure and water security improve.
The main milestones stretch from the Bangkok meetings to the country's longer economic and climate goals:
- October 15, 2025: Thailand faces growth near 2 percent and calls for reforms to support its high income ambition.
- October 2026: Bangkok hosts the IMF and World Bank Annual Meetings.
- 2030: Supportive policies could help green exports reach about 23 percent of GDP.
- 2037: Thailand aims to achieve high income status.
- 2050: Thailand's carbon neutrality goal coincides with a horizon when climate damage could reduce GDP by 7 to 14 percent without stronger adaptation.
- 2065: Thailand's net zero target.
The proposals described do not come with a single implementation timetable. Progress would be visible in a rising share of green and advanced technology exports, more innovative small businesses, secondary cities attracting investment, and infrastructure that reduces losses from floods and droughts.
Warunthorn Puthong, a World Bank economist for Thailand, said achieving a better outcome requires participation beyond government and economic institutions.
A better future does not rely solely on the work of economists and policymakers, it requires collective effort from everyone.
For households, the intended results are higher wages, more resilient jobs and greater opportunities to work, including through childcare and family policies that help women join the workforce. For businesses, the priorities are capable employees, fairer competition, access to customers and dependable infrastructure. Delivering those changes would bring the 2037 ambition closer.
Key Points
- The World Bank urges Thailand to build growth around green production, digital activity and more competitive services to reach high income by 2037.
- Growth near 2 percent trails the roughly 5 percent pace often cited as needed for that ambition.
- Five priority sectors cover digital services, advanced and green manufacturing, agribusiness, sustainable and wellness tourism, and the creative economy.
- Only about 5 percent of Thais have intermediate digital skills; stronger skills and business conditions could help startups attract up to $1.8 billion annually.
- Without stronger adaptation, climate risks could reduce GDP by 7 to 14 percent by 2050.
- Climate adaptation and emissions reduction require an estimated $219 billion over 25 years, about 2.4 percent of cumulative GDP.
- The policy rate is 1.5 percent, while public debt is near 60 percent of GDP.
- Bangkok hosts the IMF and World Bank Annual Meetings in October 2026, offering an opportunity to demonstrate reform progress.