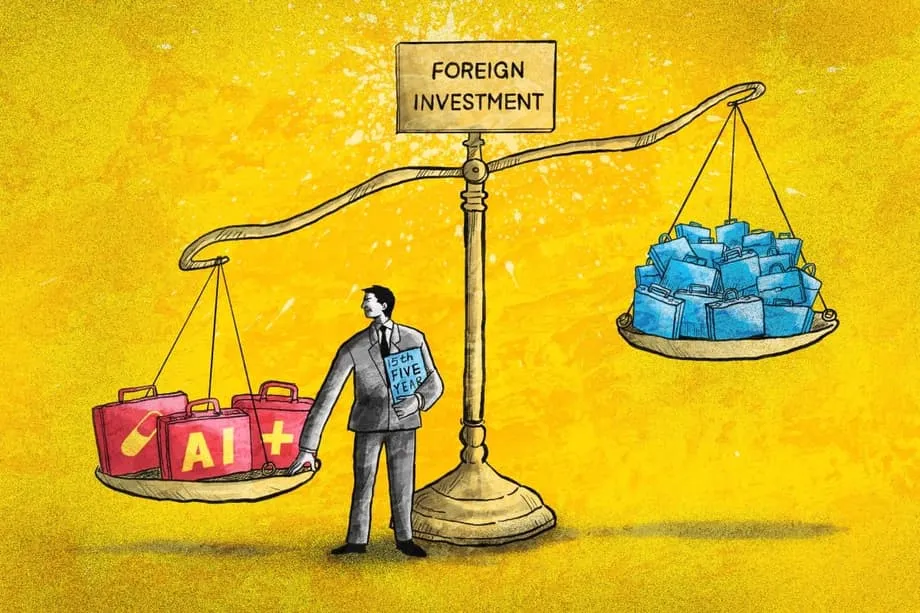
A more selective welcome for foreign investors
China's economic plan for 2026 to 2030 is taking shape around a more selective approach to foreign investment: projects that bring technology, strengthen supply chains and support strategic industries are gaining priority over the simple pursuit of more capital. As of October 15, 2025, the next five year blueprint is still being prepared, with Communist Party recommendations expected in late October and final adoption at the national legislature expected in March 2026.
Contents
- A more selective welcome for foreign investors
- What makes a foreign project attractive now?
- Technology priorities and the AI Plus push
- Security becomes central to economic planning
- Opening measures meet a weaker investment picture
- Why household spending matters
- Carbon goals reshape energy investment
- Investment opportunities beyond coastal hubs
- How the plan will be made
- What companies need to watch and prepare
- What to Know
Sun Xueguang, a veteran broker of deals across national borders and president of a Franco Chinese startup incubator, encountered that change during a recent meeting with local officials in the Yangtze River Delta near Shanghai. In previous years, foreign investors often received broad welcomes supported by tax breaks and quick approvals. This time, officials asked specifically for projects in pharmaceuticals, healthcare and artificial intelligence.
Their interest went beyond the amount a company would invest. They wanted to know how a project would fill gaps in local supply chains and help strategic industries develop. A supply chain connects the businesses, equipment and services needed to produce and deliver something. Completing one locally can make an industrial cluster more capable and competitive.
Sun described the change in the priorities of the officials he met:
The mentality is shifting from quantity to quality.
China's five year plans set targets and policy directions for the economy, society and the state. Ministries, provinces and cities use them to guide decisions, making the coming cycle important for international companies as well as domestic businesses. The emerging direction combines continued opening with greater attention to technology, economic resilience and security.
International policymakers are also watching the balance between production and spending. United States Treasury Secretary Scott Bessent has urged Beijing to make consumer demand a pillar of the next half decade. Foreign investors are looking for signs of how China will reconcile technological self reliance with its promise to remain open.
What makes a foreign project attractive now?
Local governments are asking whether a proposed investment brings capabilities their industries need. Their questions cover proprietary know how, gaps in regional supply chains, opportunities to modernize traditional businesses and the potential to establish new industrial clusters.
Pharmaceutical projects, for example, may be assessed for their contribution to local capacity to conduct biopharmaceutical trials. Manufacturing projects may be valued for smart production lines, while healthcare services can support another priority identified in Sun's meeting. Officials still want foreign capital and international expertise, but increasingly seek a direct connection between those resources and local industrial goals.
China has also reduced the negative list that restricts foreign investment. This list identifies sectors where foreign investors face limits or cannot enter. Nationwide, it has fallen to fewer than 30 items, and manufacturing entry is fully open. Service sector pilot programs have expanded access in places including Beijing, Shanghai, Hainan and Shenzhen.
Security and compliance reviews remain tighter in sensitive areas such as data, telecommunications and finance. The result is a clearer welcome for advanced manufacturing and applied technology alongside closer scrutiny of sensitive information and core technologies.
For multinational companies, the policy direction points toward incentives connected to research, worker training and the localization of supply chains. A project that contributes little to strategic goals may receive less policy support or face a longer review. Companies seeking support will increasingly need to explain what their investment adds to the surrounding economy, rather than relying on the size of the investment alone.
Technology priorities and the AI Plus push
Early discussions of the next plan place economic resilience, stronger domestic demand, and science and technology near the center of the agenda. Policymakers use the phrase new quality productive forces to describe innovation that raises productivity, meaning the economy can produce more or better goods and services with the resources it uses.
Traditional industries are expected to receive more digital tools and robotics. Advanced materials, biomanufacturing, clean energy equipment and artificial intelligence are among the newer areas being promoted as sources of growth.
AI Plus is a related policy theme. It means putting artificial intelligence to work across factories, logistics, healthcare, finance, research and public services. The ambition is to integrate AI into a very high share of manufacturing lines by 2030, linking technology development to changes in everyday production.
China Mobile offers an indication of the computing infrastructure behind that push. The state telecommunications group plans to use domestic chips for the country's largest AI computing network by 2028 and aims to expand its capacity to about 100 EFLOPS. EFLOPS is a measure of computing speed, expressed in quintillions of operations per second. The planned capacity would represent a large increase from its current level.
China Mobile Chairman Yang Jie described the role of AI at a recent conference before outlining the company's plan:
Human society has fully entered the 'AI Plus' era, with AI as the core engine of new productive forces.
China Mobile's approach connects industrial digitization with efforts to reduce dependence on foreign chip supplies. For foreign businesses, the same agenda creates opportunities to provide advanced products, conduct research locally and train workers, while domestic technology preferences shape access to critical systems.
Security becomes central to economic planning
Recent speeches by China's top leaders put national security at the center of economic planning. The stated direction is to align development with a broader security strategy, helping the country withstand external pressure and risks at home.
Semiconductors, industrial software, aerospace and energy systems are among the core technologies where policymakers want greater resilience. The goal is to strengthen those capabilities while maintaining steady growth across the wider economy.
The emerging approach concentrates resources in strategic technology sectors and seeks protection against external shocks. Its tools include targeted financing for priority industries, a larger role for capital markets in supporting industrial policy, and stronger risk controls in sensitive areas. Capital markets allow businesses to obtain funding through instruments such as shares and bonds.
Annual growth of around 4 to 5 percent is being discussed as sustainable when supported by stronger economic foundations, rather than surges driven by credit. That figure describes the approach under discussion; numerical targets and detailed tasks for the next plan have yet to be finalized.
Foreign companies experience this security focus through additional compliance checks, closer examination of data flows and stronger preferences for local content in critical systems. Industrial automation and clean power remain areas for cooperation, particularly where foreign products, research and training can raise productivity.
Opening measures meet a weaker investment picture
Commerce officials describe the current five year cycle as a period of reduced entry barriers, better protection of intellectual property and stronger national treatment for foreign firms. National treatment means treating foreign businesses on the same basis as domestic businesses under the applicable rules. Pilot free trade zones continue to test reforms in services.
Officials also point to the scale of China's consumer market. Retail sales are on track to exceed 50 trillion yuan in 2025. China has ranked first in online retail sales for more than a decade and remains the largest market for cars and home appliances.
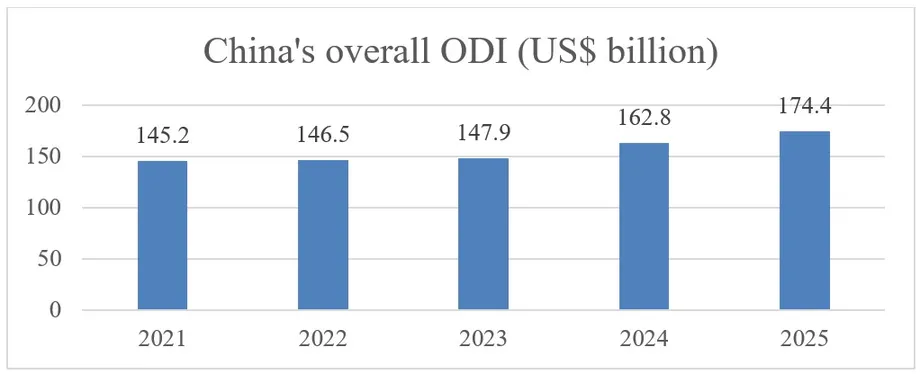
Actual use of foreign direct investment during the current plan period has reached more than $700 billion, according to commerce officials. More than 200,000 new enterprises funded by foreign investors have been registered. Many multinational companies have added regional headquarters and global research centers in Chinese cities.
Cooperation through regional trade agreements has grown, and China has offered zero tariff treatment to a wide range of products from least developed African countries. Together with changes to investment access, these measures form part of Beijing's continuing opening agenda.
The United Nations trade body, however, reported that foreign direct investment inflows into China fell in 2024 from recent peaks. The cumulative investment attracted during the current plan period and the decline in annual inflows describe different parts of the investment picture: China has received substantial capital over several years while facing a more difficult recent environment.
Many companies are rebalancing their supply chains. Restrictions on exports of advanced chips in the United States and Europe also affect technology transfer. Beijing's response is to continue opening priority areas while seeking technology, standards and lasting commitments that fit its industrial goals.
Why household spending matters
China's growth mix remains heavily dependent on manufacturing and exports, while consumption is soft relative to the economy's capacity to produce goods. The next plan's treatment of household demand will therefore matter to businesses selling into China as well as those using it as a production base.
Households remain cautious because of the weak property market, an uneven employment outlook in some segments and a tradition of saving for education, healthcare and retirement. Consumer prices fell compared with a year earlier in late summer. Leaders have discussed increasing consumption as a share of gross domestic product, the value of goods and services produced in the economy.
Economists within the policy system have called for stronger support for household spending over the next five years. Their proposals include childcare subsidies, better health coverage and pensions. Programs to trade in durable goods and subsidies for families with young children are already in place.
Large social transfers face budget constraints and ideological resistance. Officials prefer targeted programs and goals such as household incomes rising faster than GDP. That approach could increase spending power without a broad move toward what leaders call welfarism.
Bessent's call for consumer demand to become a pillar of the next half decade connects to this domestic debate. A stronger household market would help absorb more production within China, while the design of support measures will determine where additional spending power reaches consumers.
Carbon goals reshape energy investment
Green growth is expected to remain a central part of the next plan. China is preparing to shift its focus from controlling total energy use toward managing total carbon emissions, supported by better monitoring and market tools aimed at reaching the goal of peaking carbon emissions by 2030.
Energy use and carbon emissions measure different things. An energy target tracks how much energy is consumed; a carbon target tracks the emissions associated with activity. The planned shift puts greater attention on the environmental results of energy choices and industrial production.
Better monitoring of major emitters would support a more comprehensive carbon market. A carbon market uses tradable emissions allowances to place a cost on releasing carbon, giving businesses a financial reason to reduce emissions. The policy direction also supports renewables, energy storage and upgrades to electricity grids.
China already leads in solar and battery production. The next policy cycle is expected to deepen domestic deployment, make grids more flexible and support reductions in industrial carbon emissions. Grid flexibility means being able to balance electricity supply and demand as conditions change.
Foreign investment opportunities include clean power equipment, grid software, industrial energy management and materials associated with lower carbon emissions. Clear reporting of emissions across a product's lifecycle, strong local partnerships, and compliance with data and security rules will help shape access to government and corporate procurement.
Investment opportunities beyond coastal hubs
Rural revitalization is expected to remain another major priority. Its objectives include raising incomes, modernizing agriculture and expanding healthcare, education and other public services outside the largest cities.
Projects include farmland developed to higher standards, refrigerated supply chains, disaster prevention systems and digital infrastructure. Refrigerated logistics help keep food and other perishable products at suitable temperatures during storage and transport. These investments connect food production with distribution and services.
Food security remains central to the agenda. Demand for advanced seeds, smart irrigation, agricultural machinery and sensors reflects efforts to make farming more productive and reliable. Rural infrastructure and services also support more balanced growth between regions.
Foreign businesses may find opportunities beyond the major coastal centers through agricultural technology, rural healthcare and logistics partnerships. Training local workers and sharing know how can help projects secure support from county and prefecture programs. Their contribution to local capabilities will matter alongside their commercial value.
How the plan will be made
The Communist Party's Central Committee is expected to set recommendations for the next five year plan at a plenum in Beijing in late October. A plenum is a full meeting of the committee, where senior party leaders agree on major policy directions.
The National Development and Reform Commission then drafts the plan, adding numerical targets and detailed tasks across sectors and regions. Final adoption is expected at the annual legislative meetings in March 2026. The stages separate the setting of political priorities from the preparation and approval of the detailed economic blueprint.
- October 15, 2025: The next plan is being prepared, with investors watching its direction on technology, consumption and foreign investment.
- Late October 2025: A Central Committee plenum in Beijing is expected to agree on recommendations.
- Before adoption: Ministries and provinces are expected to test policies, release consultations and seek input from academics, industry groups and companies.
- March 2026: The national legislature is expected to adopt the final plan.
- 2026 to 2030: The plan will guide the next five year policy cycle.
- 2028: China Mobile plans to rely on domestic chips for the country's largest AI computing network.
- 2030: Broad AI integration in manufacturing and China's carbon peaking goal are major policy milestones.
Policy changes before adoption are expected to be incremental. Monetary authorities will continue targeted tools to ease credit for priority sectors, while fiscal policy will support disaster recovery, rural infrastructure and industrial upgrades. The emphasis is on continuity and testing rather than sweeping liberalization or a large stimulus.
What companies need to watch and prepare
Multinational companies face a more contested trade environment as they prepare for the coming cycle. Tariffs and trade remedies affect electric vehicles, batteries and solar components. Export controls on advanced chips and lithography tools, which are used in semiconductor manufacturing, limit some technology transfers.
Businesses planning investments in advanced technologies should prepare for long review periods and strict compliance checks. Projects handling personal information or critical data need arrangements for storing data locally, protocols for transfers across borders and plans for responding to incidents. Procurement in public facilities and critical infrastructure will prioritize trusted suppliers.
Companies can track the policy direction through several concrete sets of rules and programs:
- Changes to the negative list and the catalog encouraging foreign investment by sector and region.
- AI Plus funding and pilot programs, especially provincial programs connecting industrial upgrades with AI adoption.
- Rules moving from energy controls toward total carbon caps and related carbon market tools.
- New service pilots in free trade zones covering areas such as telecommunications, cloud services and healthcare.
- Government procurement rules detailing security and local content requirements for critical systems.
- Implementation rules for data transfers across borders and the scope of cybersecurity reviews.
Investment proposals will need to demonstrate how they strengthen a local supply chain, commit research budgets in China and manage data responsibly. Partnerships with universities and technical institutes can build the workforce officials want. Environmental performance and plans to meet carbon goals will also matter as the policy cycle puts greater attention on the energy transition.
Due diligence, local partnerships and transparent governance can help companies manage these requirements. The central change is a more selective relationship: foreign capital remains welcome, but its contribution to technology, productivity, security and local development increasingly shapes the support a project receives.
What to Know
- China's 2026 to 2030 plan is expected to prioritize foreign projects that strengthen supply chains, bring proprietary technology and support research.
- Officials in the Yangtze River Delta have sought projects in pharmaceuticals, healthcare and AI, reflecting a shift from investment quantity to quality.
- Manufacturing entry is fully open, and the nationwide negative list has fewer than 30 items, while sensitive sectors face closer scrutiny.
- Commerce officials report more than $700 billion in foreign investment during the current plan period; annual inflows fell in 2024 from recent peaks.
- AI Plus, green growth and rural revitalization are expected to be central priorities.
- Consumption support is expected to favor targeted measures and income growth rather than broad social transfers.
- Party recommendations are expected in late October 2025, followed by legislative adoption in March 2026.
- Data governance, cybersecurity, local capabilities and carbon reporting will shape investment and procurement opportunities.