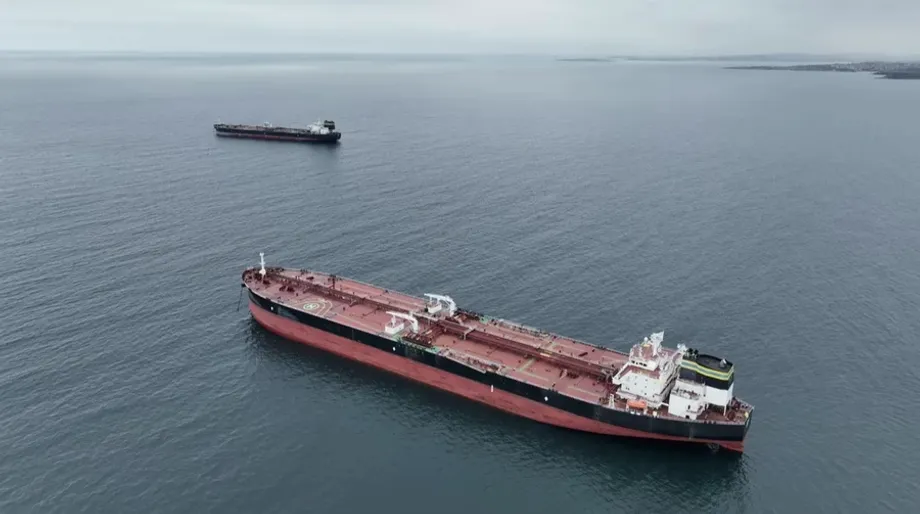
A $1.3 billion trade tests Taiwan's commitments
Taiwan became the world's largest buyer of Russian naphtha in the first half of 2025, purchasing about $1.3 billion of a petroleum product used to make plastics and chemicals. Average monthly purchases were nearly six times the monthly average in 2022, even as Taipei supported Ukraine and aligned itself with Western sanctions against Moscow.
Contents
- A $1.3 billion trade tests Taiwan's commitments
- Why naphtha matters to factories and chips
- How Russia's export map shifted
- Public companies withdrew as private buying grew
- Formosa's Mailiao complex is central to the trade
- How the price cap works and what the study alleges
- Taipei reviews controls and consults companies
- Supply choices carry security and diplomatic costs
- What to Know
A joint analysis by the Centre for Research on Energy and Clean Air and partner organizations puts the longer trade at 6.8 million tonnes worth about $4.9 billion between February 2022 and June 2025. Taiwan accounted for roughly 20 percent of Russia's naphtha exports over that period, making its factories an important destination for a product that lost buyers elsewhere after the invasion.
Taiwan has provided Ukraine with $50 million in bilateral aid. Yet its purchases of Russian energy since 2022 exceeded $11.2 billion. The study estimates that those energy purchases generated about $1.7 billion in Russian mineral extraction taxes, which it equates to the production cost of as many as 170,000 Gerbera drones used in attacks on Ukraine.
The tax estimate concerns Taiwan's Russian energy purchases, a broader category than naphtha alone. It illustrates why the debate extends beyond the price paid by petrochemical companies: energy sales also generate revenue for the Russian government.
Taiwan's dependence on imports makes supply decisions especially consequential. About 97 percent of its energy needs are met from overseas, while its petrochemical companies have faced a prolonged period of weak profit margins in Asia. Discounted Russian naphtha has helped relieve that pressure, creating a conflict between commercial savings and the island's diplomatic and security priorities.
Why naphtha matters to factories and chips
Naphtha is a liquid mixture of hydrocarbons produced when crude oil is refined. Petrochemical plants use it as feedstock, meaning the raw material they turn into other products. In equipment called steam crackers, naphtha is processed into chemical building blocks, including olefins such as ethylene and propylene and aromatics such as benzene and paraxylene.
Factories turn those chemicals into resins, films, solvents and specialty materials. They appear in smartphone casings, data center components, photoresists and packaging materials used in semiconductor factories. The connection with chips runs through this broad chemical supply chain: naphtha helps produce many inputs used by electronics manufacturers.
Taiwan's largest petrochemical complexes are configured primarily for naphtha. Some hubs elsewhere, including in the United States, use ethane obtained from natural gas. Changing a cracker to accept a different raw material can require years of work and enormous investment, so replacing naphtha itself is a much larger undertaking than changing the country supplying it.
Taiwanese buyers secure supplies through both term contracts, which cover deliveries over an agreed period, and spot cargoes bought for individual shipments. Discounted Russian supplies between 2023 and 2025 reduced costs during a steep downturn in global olefin margins, the gap between production costs and the money earned from selling those chemicals.
How Russia's export map shifted
European and South Korean demand for Russian naphtha dried up after the invasion. Previously, South Korea and the Amsterdam, Rotterdam and Antwerp trading region in Europe had been among its largest destinations. Sanctions and company policies on risk pushed that trade away, and Russia redirected cargoes toward Taiwan, China and India at favorable prices.
Russia exported about 397,000 barrels of naphtha per day in 2025, with around 74,000 barrels per day going to Taiwan, largely for the Mailiao petrochemical complex. Those figures put Taiwan's share at roughly 19 percent, close to one barrel in every five exported.
Ship tracking company Kpler estimates that Taiwan averaged about 75,000 barrels per day of Russian naphtha imports in 2025 to date, compared with about 71,000 in 2024. Separately, imports in the first half of 2025 grew about 44 percent from the first half of 2024. The annual averages and the comparison between the two first halves describe different periods.
South Korean refiners and petrochemical companies reduced Russian naphtha purchases to zero by July 2022 and diversified their supplies. Executives there acknowledge that giving up deeply discounted Russian cargoes hurt their cost economics, but say legal and reputational risks outweighed the savings.
Taiwan's coal trade moved in the opposite direction from naphtha. Russian coal purchases fell about 67 percent in early 2025 compared with the previous year, showing how differently individual parts of the island's energy trade have developed.
Public companies withdrew as private buying grew
Taiwan's government controlled companies pulled back from Russian energy after 2022. State businesses, including Taipower and Chinese Petroleum Corporation, commonly known as CPC, stopped buying Russian crude and light oil products, with the withdrawal completed across 2023 and into mid 2024.
Private businesses operated under different conditions. Taipei had not explicitly banned imports of Russian fossil fuels, leaving companies able to continue purchases while the government supported sanctions and expanded restrictions on sensitive exports to Russia.
Formosa Petrochemical moved sharply toward Russian supply. The study says Russian naphtha rose from about 9 percent of its purchases before the invasion to 90 percent in the first half of 2025; the company puts the share at about 85 percent in its internal figures for 2025 to date.
The gap between public and private purchasing lies at the center of the policy dispute. State companies had already withdrawn from Russian crude and light oil, while private buyers continued sourcing discounted feedstock without an explicit Taiwanese prohibition on those imports.
The main developments unfolded over more than three years:
- February 2022: Russia's full scale invasion prompted Taiwan to join sanctions and began the period covered by the study's cumulative naphtha figures.
- July 2022: South Korean buyers had reduced Russian naphtha purchases to zero.
- 2023 to mid 2024: Taiwan's state businesses completed their withdrawal from Russian crude and light oil products.
- January to June 2025: Taiwan bought about $1.3 billion of Russian naphtha and became its largest buyer worldwide.
- September 16, 2025: A tanker discharged diesel from the Vadinar refinery valued at $43.8 million, a shipment cited in the study's discussion of refined products.
- October 2025: Market data indicated that Formosa took no Russian naphtha for October deliveries because offers were limited.
Formosa's Mailiao complex is central to the trade
Formosa Petrochemical, Asia's largest single naphtha buyer, operates a sprawling complex at Mailiao on Taiwan's western coast. The study estimates that Mailiao alone accounted for roughly 96 percent of Taiwan's naphtha imports in the first half of 2025, placing the company at the center of scrutiny over Russian supplies.
Formosa disputes some of the study's figures and says the Russian share of its purchases reflects market conditions rather than a policy choice. It says it buys through open bidding and requires every seller to comply with sanctions rules and price caps.
The company has also said it is considering reducing Russian volumes to limit business risk. Formosa described how it would respond to tighter international restrictions or a new prohibition from Taipei:
Should international rules tighten further, or should our government issue new prohibitions, the company will comply immediately and fully support all relevant measures.
Market data on October deliveries already pointed to a pause in Russian purchases, although limited offers were the stated reason. Cargo flows can change quickly when price differences between markets shift or sellers reach contract limits. A pause caused by the availability of cargoes therefore has a different commercial explanation from a decision to stop sourcing from Russia.
The study identifies Novatek, a Russian producer under United States sanctions, as the source of about 72 percent of Russian naphtha arriving in Taiwan during the study period. That concentration adds another consideration for buyers assessing the legal, commercial and reputational risks of their supply arrangements.
How the price cap works and what the study alleges
The G7 and European partners created a price cap system for Russian oil and refined products to restrict Moscow's revenue while keeping supplies moving through global markets. Under the system, shipping, insurance and other critical services from participating countries can be used only when covered cargoes are bought at or below the relevant cap.
Naphtha falls into the lower value refined products category, capped at $45 per barrel. Higher value products, including diesel and gasoline, have a $100 cap. Traders and carriers typically provide attestations, written assurances that the cargo was purchased within the limit.
The study alleges that about 88 percent of Russian naphtha cargoes bound for Taiwan traveled on vessels owned or insured in jurisdictions participating in the price cap system, even when trade data suggested effective prices above $45 per barrel. Its concern is the combination of those services and prices it estimates exceeded the threshold.
The study also cites transactions involving other refined products, including the September 16 discharge of diesel from the Vadinar refinery valued at $43.8 million. Analysts discussing those cases argue that they reveal a gap between sanctions rules and trading practices.
Compliance depends on several connected arrangements: purchase documents, assurances from traders, freight practices and insurance contracts. A failure can involve deliberate conduct or inadequate documentation. Companies operating in participating jurisdictions face legal and reputational exposure when those arrangements fail.
Hsin Hsuan Sun, a director at Taiwan's Environmental Rights Foundation and a coauthor of the study, argued that the savings from Russian feedstock conflict with Taiwan's wider interests:
Taiwan should not be financing the Kremlin's war machine.
Taipei reviews controls and consults companies
Taiwan's Ministry of Economic Affairs says it has tightened export controls on sensitive goods sent to Russia and is discussing compliance and risk with domestic companies. It has also indicated that it is reviewing control measures as international sanctions develop.
The ministry described its intended response to expanding restrictions:
As international sanctions continue to expand, the ministry will further review relevant control measures and engage with domestic companies on compliance, while continuing to work with international partners to demonstrate its firm resolve to oppose aggression and uphold the international order.
The Ministry of Foreign Affairs and the Ministry of Economic Affairs say Taiwan has expanded controls on sensitive high technology exports to Russia and that state companies no longer import Russian crude or light oil products. Regulators are examining the absence of import controls on light oil while talking with businesses about compliance.
Economy Minister Kung Ming hsin said in October that private refiners were willing to stop buying Russian naphtha if the European Union requested it. He said the government had consulted Brussels and industry and would respect EU and G7 norms.
As of October 11, 2025, no date had been given for a new Taiwanese import prohibition. The minister's position and Formosa's pledge leave open the possibility of a rapid change if formal restrictions arrive in 2026, while current discussions focus on compliance and possible controls.
Supply choices carry security and diplomatic costs
Taiwan faces military pressure from China, which claims the island as its territory, while Moscow maintains close ties with Beijing. Reliance on Russian energy has therefore prompted concern that a country closely connected to China's leadership could gain influence over an essential industrial supply during a crisis.
Analysts worry that an interruption in Russian shipments would put immediate pressure on petrochemical and electronics production. Taiwan's heavy dependence on imported energy makes reliable access to replacement cargoes especially important.
China has used economic coercion against countries in Asia and Europe. If Russia reduced deliveries because of pressure from Beijing or for strategic reasons, Taiwanese buyers would need replacement feedstock in the spot market. A scramble for supplies could raise costs for plastic resins and chemical inputs used throughout Taiwan's exports, including components for the semiconductor industry.
Democratic partners have pressed for stricter enforcement of sanctions on Russian fossil fuels. Nongovernmental organizations warn that greater dependence on Russian cargoes could weaken Taiwan's standing with the United States, the European Union and other allies at a time when Taipei seeks closer security and trade cooperation.
Puma Shen, a legislator from the Democratic Progressive Party, said Taiwan's commercial decisions should match its foreign policy commitments:
Taiwan's trade and economic actions must align with our democratic partners, or we risk damaging our international reputation.
For manufacturers, a change in sourcing would bring a direct cost calculation. Industry groups say equivalent volumes would need to come from the Middle East, Southeast Asia and the United States at acceptable prices. Higher feedstock costs would affect petrochemical margins and could flow into packaging, automotive parts and electronics.
South Korea's experience provides a concrete comparison: its companies replaced Russian naphtha while accepting weaker cost economics. Taiwan's private buyers now face the same balance between inexpensive raw materials, dependable supply and the risks attached to continued Russian purchases.
What to Know
- Taiwan bought about $1.3 billion of Russian naphtha in the first half of 2025, becoming its largest buyer worldwide.
- Purchases from February 2022 through June 2025 totaled 6.8 million tonnes worth about $4.9 billion, roughly 20 percent of Russia's exports of the product.
- The study estimates that Taiwan's Russian energy purchases generated $1.7 billion in mineral extraction taxes for Moscow.
- State businesses stopped buying Russian crude and light oil, while private buyers increased their reliance on Russian naphtha.
- The study puts Formosa's Russian share at 90 percent in the first half of 2025; Formosa gives a figure of about 85 percent for 2025 to date.
- Novatek supplied about 72 percent of the Russian naphtha arriving in Taiwan during the study period.
- The study alleges that 88 percent of cargoes used vessels owned or insured in price cap jurisdictions despite estimated prices above the $45 limit.
- Formosa promises to comply with new prohibitions, and Economy Minister Kung Ming hsin says private refiners are willing to stop purchases if the EU requests it.
- South Korea ended Russian naphtha purchases by July 2022, while Taiwan's Russian coal purchases fell about 67 percent in early 2025.