Brands turn online as store costs climb
Southeast Asia's ecommerce market reached about $145.2 billion in 2024, yet branded goods generated less than 30 percent of sales on marketplace platforms. As of September 20, 2025, that gap is becoming a major opportunity for brands facing rising retail rents, store fit out expenses and labor costs.
Contents
- Brands turn online as store costs climb
- A larger market after the pandemic surge
- Three platforms shape the online shelf
- Video and payments reshape buying habits
- Delivery quality becomes a competitive advantage
- Local warehouses change cross border selling
- Chinese beauty brands win younger shoppers
- Appliance competition moves onto marketplaces
- Brands need connected stores and regular content
- Advertising must lead to profitable orders
- Six markets require different approaches
- Costs and platform rules can squeeze growth
- Highlights
Prime shopping districts across the region have become more expensive places to operate. Physical stores still give brands visibility and help shoppers trust their products, but maintaining those stores is putting more pressure on budgets. Brand owners are directing more attention and spending toward online channels, where they can reach larger audiences, test product ranges faster and track the return on their spending in real time.
Marketplace operators have their own financial pressures. Customer numbers and orders surged during the pandemic, but profits did not always follow. Heavy spending on discounts and other subsidies reduced margins, while expensive deliveries weighed on earnings. Platforms are now concentrating on sustainable unit economics, meaning whether the money earned from each order can cover the costs of serving it.
Brands want a stable place to build awareness, turn interest into purchases and keep customers returning. A business built around repeated discounts can make that difficult. The shift toward healthier platform finances creates room for stronger products, service and customer relationships to play a larger role.
Industry estimates put brands at under 30 percent of Southeast Asia's platform gross merchandise value in 2024, compared with more than half in China. Gross merchandise value, or GMV, is the total value of goods sold. Growing use of digital wallets, product discovery through creators and better delivery coverage across cities and islands are helping brands reach that market.
A larger market after the pandemic surge
Southeast Asian ecommerce grew fivefold between 2016 and 2021. Over that period, online purchases increased from about 5 percent of total retail sales to roughly 20 percent. Growth has since moderated, but it is taking place from a much larger base, with online shopping established as a consumer habit.
The region's approximately $145.2 billion in ecommerce GMV in 2024 included marketplace platforms and sales through other channels. Platforms accounted for about $128.4 billion, up roughly 12 percent from the previous year as operators reduced their dependence on heavy subsidies and pursued healthier returns.
Non platform channels generated an estimated $16.8 billion. These include brand websites, retailers selling multiple brands online, social commerce and purchases arranged through messaging services. Together, those channels represented about 11.6 percent of total ecommerce GMV, using the $16.8 billion and $145.2 billion estimates.
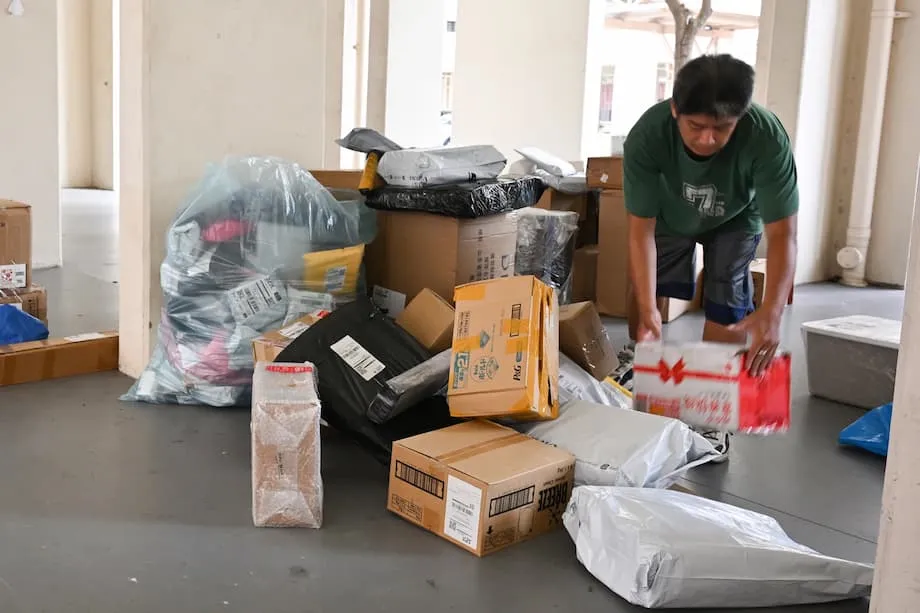
Parcel traffic shows the size of the delivery operation supporting this market. About 43.6 million packages were shipped each day in 2024, approaching volumes seen in much larger markets. The region's six largest economies generate most ecommerce activity, with Indonesia remaining the largest by scale.
Industry projections point to GMV potentially reaching around $230 billion by the middle of this decade and moving toward the high $300 billion to low $400 billion range by 2030 if current trends continue. Those forecasts describe a market with further room to expand as online retail reaches more consumers and categories.
Three platforms shape the online shelf
Shopee, TikTok Shop and Lazada now control the vast majority of platform GMV in Southeast Asia and handle most parcel volume. Their size gives them the resources to invest in logistics, fraud prevention, product recommendation systems and tools for sellers.
Shopee remains the leader in many markets. TikTok Shop has expanded quickly through short videos and live shopping, while Lazada has focused on better quality branded products alongside improvements in monetization and technology.
Smaller platforms face difficulty matching those investments. For brands, the concentration puts much of the region's shopping traffic within a small number of marketplaces, each with its own selling tools and operating priorities.
Apparel, cheaper electronics and accessories still account for a large share of online baskets. Beauty, home products and groceries are gaining ground. Platforms are giving brands more reasons to invest by prioritizing product quality, service guarantees and advertising tools that use shopping data.
Video and payments reshape buying habits
Marketplaces remain Southeast Asian shoppers' leading channel for discovering products, followed by social media and search. Video has become central to both finding products and deciding whether to buy them, while live shopping is an established part of the market.
Live commerce generated about $17.6 billion in 2024, equivalent to roughly 14 percent of platform GMV. When live selling is combined with other formats built around video, the share reaches about one fifth of platform sales.
A brand's online presence therefore extends beyond its marketplace storefront. Shoppers encounter products in feeds, watch demonstrations in streams and then visit a store page or another sales channel. Brands need to earn attention throughout that journey.
Payments are changing alongside discovery. Digital wallets and local online payment methods have gained share in every major market and lead checkout choices across the region. Credit cards rank higher among more affluent shoppers, while cash on delivery remains relevant in parts of Indonesia and Vietnam.
More payment options make mobile purchases easier, especially for people buying online for the first time. Cash on delivery still serves some customers, but it brings higher risks and costs for sellers. Checkout choice has become part of the service a brand provides.
Delivery quality becomes a competitive advantage
Southeast Asia's delivery networks must connect crowded megacities, rural provinces and island communities. Providers have invested in sorting centers, automation, route planning and different service levels to manage those distances while controlling costs.
Many logistics companies now handle the full journey from warehouse to doorstep, together with returns processing and support after a sale. For brands, that makes delivery part of the customer experience rather than simply a transport expense.
Surveys show that only a minority of consumers are fully satisfied with delivery services, while a large majority say they would pay somewhat more for reliable delivery that arrives on time. Speed matters, but dependability also gives sellers a way to compete.
Furniture, appliances and other bulky products need specialized handling and delivery appointments. Returns are rising, particularly in apparel and electronics, making a clear and smooth returns process an important reason for shoppers to choose one seller over another.
Local warehouses change cross border selling
More sellers and brands are moving away from sending individual parcels directly from factories to overseas customers. Instead, they ship goods in bulk to warehouses in the destination market and dispatch orders from closer to the buyer.
This business to business to consumer model, often called B2B2C, can shorten delivery times, improve compliance with local rules and help sellers handle busy periods without running out of stock. It also makes larger products more practical to sell online when local delivery and service are available.
Platforms are bringing more logistics operations in house to gain control over speed and cost. Independent delivery companies continue expanding across countries, using regional sponsor models and automation to improve efficiency, but many face narrow margins and pressure to lower prices.
Courier selection has also attracted regulatory attention in some markets. Competition authorities have examined platform practices to keep competition fair, while debate over minimum delivery fees reflects concern about the economics of a maturing delivery industry.
Chinese beauty brands win younger shoppers
Chinese entrants, local brands and global companies are reshaping competition in beauty and home appliances. Chinese businesses bring large manufacturing operations, aggressive prices and selling methods developed on their domestic platforms. Local and international rivals compete through quality, deeper distribution and premium positioning.
In Indonesia, a group of leading Chinese color cosmetics labels increased their market share from low single digits in 2019 to the mid teens by 2024. Creator marketing, livestream selling and low prices have helped them gain ground, especially in mass market color cosmetics.
Many products sell for $2 to $5, a range closely matched to the spending power of Gen Z consumers in markets such as Indonesia and Thailand. Some brands offer hundreds of stock keeping units in each marketplace store. A stock keeping unit identifies a particular product variation, such as a different shade or size.
Customer to manufacturer models let companies use local feedback to develop new shades or textures quickly. That response helps speed up product innovation and makes the online shelf more dynamic, while competitors seek to hold customers through quality, service and stronger brand identities.
Appliance competition moves onto marketplaces
Chinese appliance makers have increased their share across several product categories over the past decade, with strong gains in vacuum cleaners, washing machines and microwave ovens. Competitive prices and frequent product updates have helped them take space from Japanese and South Korean incumbents.
Localized operations, assembly within the region and faster cross border logistics have improved delivery and service after purchase. Those changes matter for products that are costly to transport, may need installation and require repairs if something goes wrong.
Local brands are responding by focusing on durability, energy efficiency and service. They are also investing more in online content that explains products and in installation support, helping customers assess larger purchases without relying entirely on a store visit.
Beauty and appliances illustrate different demands within the same online market. Cosmetics businesses can respond rapidly with new shades and affordable choices. Appliance sellers also need the delivery, installation and service arrangements that make a larger purchase convenient.
Brands need connected stores and regular content
Opening a marketplace shop is only one part of reaching Southeast Asian consumers. Shoppers discover, compare and buy across mobile services, social media, marketplaces and brand websites. Brands need content, advertising and retail operations to work together while keeping costs and service standards under control.
Marketplaces still attract most shopper attention, but other channels are growing. Combining a strong marketplace presence with an easy to use brand website lets companies serve impulse buyers as well as loyal customers who return directly.
Accurate inventory information, consistent pricing and coordinated customer service help shoppers move between channels without encountering conflicting answers. A product advertised in a video also needs to be available when the viewer reaches the checkout.
Video's roughly 20 percent share of platform sales supports regular programming rather than occasional promotional events. Brands are investing in short tutorials, creator partnerships and scheduled live shows that can become part of shoppers' weekly routines.
Clear product stories, bundles available for a limited period and visible information about quick fulfillment can help turn viewers into buyers. Brands are also spreading spending across more content platforms and different groups of creators, with attention to authenticity and community.
Advertising must lead to profitable orders
Advertising costs on major social and search channels have risen in many markets. Brands are responding by making greater use of first party data, meaning information collected through their own customer interactions, to improve targeting and measurement.
Advertising tools within Shopee, Lazada and TikTok give brands access to people already browsing or considering purchases. Ads placed within these shopping environments are often called retail media. Brands are also developing content specifically for the platforms where it will appear.
New solutions centered on marketplaces promise to connect advertising and content with completed purchases inside those platforms without extra tracking tags. That process, known as attribution, helps a seller understand which activity contributed to a sale and decide where to spend more.
AI systems are increasingly used to improve product listings, advertising bids, creative variations and customer service scripts. These tools sit alongside the practical work of keeping products available, answering customers and fulfilling orders reliably.
Discount festivals can lift sales quickly, but repeated promotions can reduce margins and teach customers to wait for the next price cut. Brands are balancing advertising aimed at immediate purchases with consistent storytelling, cultural relevance and recognizable brand assets that help people remember them.
Service remains part of that calculation. Clear return windows, tracking customers can access themselves and proactive delivery updates can reduce customer losses and encourage repeat purchases. Holding imported stock in local warehouses can also shorten waits and simplify compliance.
Six markets require different approaches
Indonesia contributed about 44 percent of Southeast Asia's platform GMV in 2024. Growth slowed compared with earlier years, but its absolute scale remained unmatched. TikTok Shop completed its integration with Tokopedia, live commerce continued to grow and social discovery remained strong. Beyond Java, logistics investment and localized content are opening new areas of demand. Digital wallets are gaining ground, although cash still serves some orders.
Thailand was among the fastest growing markets in 2024, with platform GMV increasing by more than 20 percent from the previous year. Live shopping is mainstream, and shoppers have a wide selection of products arriving from China. Beauty, fashion and home products benefit from creator networks and options for delivery the next day in major cities.
Malaysia recorded annual gains near 20 percent. High digital wallet use makes checkout easier, and shoppers are comfortable moving between marketplaces and brand websites. Online groceries, health and beauty products have steady momentum, supported by improvements in temperature controlled transport and the final stage of delivery to customers.
Vietnam's platform GMV reached around $16 billion in 2024, with healthy growth in double digits. Its role as a manufacturing hub supports faster regional supply chains. Shoppers are heavily engaged with social and short video commerce, while logistics infrastructure is expanding beyond the largest urban centers.
The Philippines continues to gain online shoppers as smartphone use deepens. Its island geography makes delivery complicated and costly, but logistics networks are expanding and parcel volumes are high. Beauty, small electronics and household essentials are popular categories, with creators playing an outsized role in product discovery.
Singapore has a small population but high GMV per person. Shoppers expect premium service, narrow delivery windows and easy returns, and purchases from overseas are common. Brands use Singapore as a regional base for data, operations and testing new shopping experiences. Retail rents are among the region's highest, pushing even premium brands to invest more online.
Costs and platform rules can squeeze growth
Platform concentration creates operational risks for brands and delivery partners. As marketplaces change seller policies or bring logistics in house, businesses can face sudden changes in visibility or parcel volume. Regulatory examinations of courier choice and fairness show how closely competition and delivery arrangements are connected.
Delivery fees leave many couriers with thin margins, while higher media costs add pressure for brands. Businesses that depend heavily on discounts and subsidized shipping may earn less if those costs rise further.
Returns processing, fraud and customer abuse can also reduce profits. Payment preferences remain fragmented in some countries, meaning sellers need different checkout options to avoid losing purchases. Supply chains are diversifying across Southeast Asia, but dependence on one sourcing country or lengthy cross border routes can cause delays during disruptions.
Brands are responding by diversifying supply, building flexible fulfillment operations and developing local talent. The opportunity is substantial, but profitable growth depends on connecting product demand with affordable advertising, reliable payment, delivery and service.
Highlights
- Rising rents, fit out expenses and labor costs are pushing Southeast Asian brands to invest more in online channels.
- Ecommerce GMV reached about $145.2 billion in 2024, including $128.4 billion on platforms and $16.8 billion through other channels.
- Brands generated under 30 percent of platform GMV, compared with more than half in China.
- Shopee, TikTok Shop and Lazada control the vast majority of platform sales.
- Live commerce generated about $17.6 billion; live and other video formats together accounted for roughly one fifth of platform GMV.
- Daily parcel shipments reached about 43.6 million, while local warehousing is helping sellers shorten delivery times.
- Indonesia represented about 44 percent of platform GMV; Thailand and Malaysia recorded strong growth in 2024.
- Chinese brands gained ground in beauty and appliances as local and global rivals competed on quality, service and premium positioning.
- Digital wallets are growing, but cash on delivery still matters in parts of Indonesia and Vietnam.
- Platform policies, advertising costs, narrow delivery margins, returns and payment fragmentation remain risks to profitable growth.