Growth of 2.1% sharpens the central bank's dilemma
The Philippine economy grew just 2.1% in the third quarter of 2026, leaving the Bangko Sentral ng Pilipinas (BSP) to weigh a pause in interest rate increases even as October inflation reached 7.8%. Its next decision, scheduled for December 17, will determine whether borrowing costs rise again after four consecutive increases.
Contents
- Growth of 2.1% sharpens the central bank's dilemma
- How far has growth fallen?
- Households spend more pesos but get less growth
- Energy prices are spreading pressure beyond fuel
- Rice and weak investment deepen the slowdown
- Why weak output could persuade the BSP to wait
- Why other economists still expect higher rates
- Forecasts point to a slow and uneven recovery
- The dates shaping the next decision
- Key Points
The Philippine Statistics Authority (PSA) released the growth figures on November 9. They showed a fifth consecutive quarter of slowing expansion and the weakest growth outside the pandemic years since 2009. Household spending lost momentum, agriculture contracted and investment fell again.
The BSP raised its benchmark policy rate by 50 basis points to 5.5% on October 22, bringing increases since April to 125 basis points. A basis point is one hundredth of a percentage point, so the October move added half a percentage point to the rate that helps guide borrowing costs across the economy.
Capital Economics Senior Asia Economist Gareth Leather believes the growth slump supports a pause and suggests the tightening cycle may already be over. HSBC, ING and Bank of the Philippine Islands expect another smaller increase in December, while Bank of America and Citi foresee rates reaching 6% in early 2027.
For households, the choice involves two pressures already squeezing their budgets: expensive essentials and costly credit. For businesses, another increase would add to financing costs while customers are buying less than stronger spending figures in pesos might suggest.
How far has growth fallen?
Philippine GDP growth has slowed from 5.5% in the second quarter of 2025 to 2.1% a year and a quarter later. GDP measures the value of goods and services produced within the country, with growth figures adjusted to remove the effect of changing prices.
The latest PSA release revised second quarter growth in 2026 to 2.4%, from the previously published 2.3%. Third quarter growth was also down from a revised 4% in the same period of 2025, making the latest pace little more than half its level a year earlier.
Growth averaged 2.5% during the first nine months of 2026, below the government's annual target of 3.5% to 4.5%. Economy, Planning and Development Secretary Arsenio Balisacan said expansion of about 6.3% in the final quarter would be needed just to reach the bottom of that range.
Balisacan described that requirement as:
very, very challenging.
Bank of America expects growth of only 2.6% in the fourth quarter. The gap between that forecast and the government's required 6.3% illustrates why even a modest recovery would leave the annual target difficult to reach.
Households spend more pesos but get less growth
Household consumption grew 2.4% in the third quarter, down from 2.9% in the preceding quarter. HSBC described it as the weakest expansion outside the pandemic since 2010. Spending on transportation fell 5.3%, while consumption of food and nonalcoholic beverages increased only 1.6%.
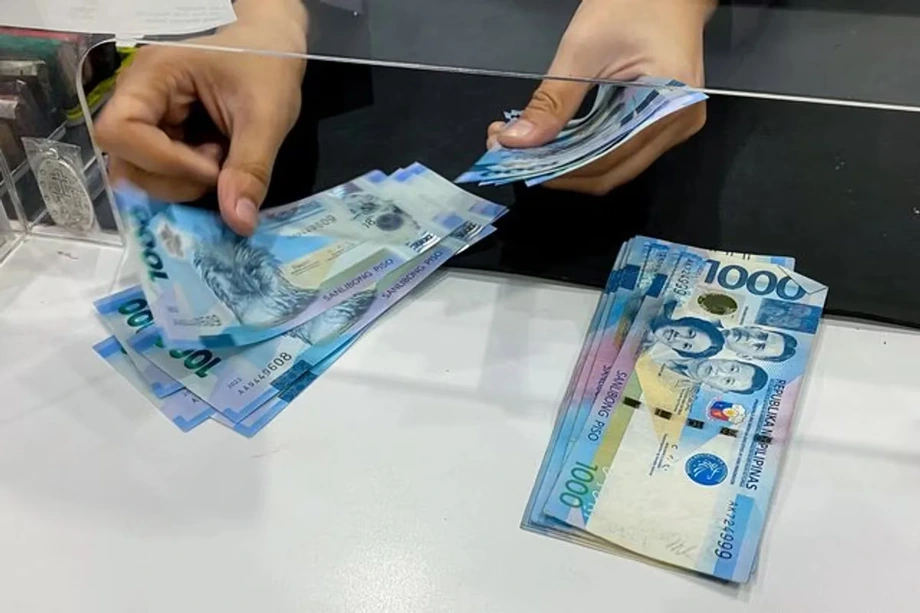
Consumer spending measured in current pesos rose 8.5%, according to the economic commentary accompanying the GDP figures. The much smaller 2.4% increase after adjusting for prices shows why bigger household bills can coexist with weak economic activity: much of the extra money buys the same goods and services at higher prices.
October inflation was particularly painful for poorer families. The PSA recorded inflation of 9.5% among the bottom 30% of households by income, compared with 7.8% nationally. Their average inflation rate for 2026 through October reached 6.8%.
Balisacan said he did not expect consumer spending to recover strongly soon because earlier inflation was still affecting purchasing decisions. He also warned that November inflation would remain challenging. That makes the next consumer price release important to the December policy debate.
Energy prices are spreading pressure beyond fuel
October inflation rose from 7.2% in September and 1.7% a year earlier, the PSA announced on November 5. Average inflation for January through October reached 5.6%, above the BSP target range of 2% to 4%.
Transport inflation accelerated to 20.1%, from 14.6% in September, as fare increases introduced in late September took fuller effect. Gasoline prices rose 51.1% from a year earlier and diesel prices 62.4%. Electricity inflation reached 14.5%, adding pressure to household budgets and business operating costs.
ING's October inflation assessment said fuel and electricity added around 70 basis points, or 0.7 percentage points, to headline inflation, while easing food inflation excluding rice provided some relief. October's 7.8% reading exceeded the 7.6% market consensus but remained within the BSP forecast range.
Core inflation, which excludes selected food and energy items whose prices swing sharply, rose to 5.4%. The PSA put September core inflation at 4.7%, while ING used 4.8% in its comparison. ING said October marked a sixth consecutive month above the central bank's target range, with transport fares, restaurants and hotels contributing to the pressure.
BSP Governor Eli M. Remolona Jr. explained the October rate increase by pointing to several forces expected to keep pushing up prices:
We took this decisive action because we forecast that inflation will accelerate further in the coming months due to oil prices, transport fares, and the potential effects of El Niño on food prices,
Higher interest rates can restrain borrowing and spending, reducing the room for businesses to keep raising prices. They cannot produce more rice or lower world oil prices, which makes the balance harder when inflation begins with disrupted supplies.
Rice and weak investment deepen the slowdown
Food inflation eased to 6.1% in October from 6.7% in September, helped by slower price increases for vegetables and seafood. Rice remained a major exception: its price rose 20.7% from a year earlier and contributed 1.4 percentage points to headline inflation.
National Statistician Dennis Mapa linked rice pressure partly to lower palay production in the third quarter and El Niño. Agriculture contracted 4.8%, with palay output falling 17.8%, corn production declining 17.4%, and fishing and aquaculture shrinking 8.5%.
Construction also contracted 4%. Within investment spending, government construction fell 15.1%, while gross capital formation, a broad measure of investment, declined 0.2%. That was its fifth consecutive quarterly contraction, although less severe than the previous quarter's 8.8% fall.
HSBC economist Aris Dacanay linked a persistent confidence shock to investigations into flood control projects and curtailed infrastructure disbursements. Balisacan said agencies had become cautious about acting on projects because officials feared becoming caught up in infrastructure scandals.
Exports grew 8.6% and government consumption increased 6.8%, providing support without overcoming weak domestic demand. Net foreign direct investment inflows totaled $4.07 billion in the first seven months of 2026, down 23.9% from a year earlier, adding another constraint on investment.
Why weak output could persuade the BSP to wait
Remolona has said a sufficiently negative output gap would make further tightening less likely. The output gap compares what an economy actually produces with what it could sustainably produce using its workers, factories and other resources. A negative gap signals spare capacity and weaker pressure from demand.
The governor made those remarks before the third quarter GDP release, when he expected growth might improve from the previously published second quarter figure of 2.3%. Instead, the latest figures showed another slowdown, even after that earlier quarter was revised upward.
Leather attributes the weakness partly to inflation and higher interest rates depressing consumer spending. Pantheon Macroeconomics also sees a December hold as possible, although it says November consumer price inflation would have to be much softer than expected.
Deutsche Bank expects a December pause followed by a quarter point increase in February 2027. In its assessment, the large October move brought forward some tightening in anticipation of persistent inflation next year.
A pause would leave the benchmark rate at 5.5%, keeping existing restraint in place while the BSP assesses its effects. Remolona has said the central bank is not ready to begin cutting rates, with inflation expected to stay above its 3% target midpoint over the next two years.
Why other economists still expect higher rates
HSBC's Dacanay expects a 25 basis point increase in December to 5.75%, which he believes would end the tightening cycle. HSBC says weak growth makes another 50 basis point move less likely, but persistent inflation and wage growth running at roughly the same pace as inflation still support a smaller increase.
ING also expects a quarter point move. Its assessment says the October increase probably anticipated much of the inflation surge, while easing oil prices, a weaker US dollar and soft growth could give the BSP room to move less aggressively.
BPI lead economist Emilio Neri Jr. warns that stopping too early could allow inflation to become more entrenched and make recovery harder. Before the October decision, former BSP deputy governor Diwa Guinigundo and economist Wilhelmina Manalac had supported a half point increase for similar reasons.
Bank of America and Citi expect quarter point increases in December and early 2027, taking the policy rate to 6%. Citi sees price pressure spreading into early next year and considers energy inflation a greater risk for broad price increases than food pressure associated with El Niño.
The peso adds another consideration because a weaker currency raises the local cost of imported fuel and other goods. It reached P64.17 per dollar on October 27, after closing at P63.361 on October 20. Remolona says the BSP intervenes to reduce large currency swings rather than defend a particular exchange rate.
Forecasts point to a slow and uneven recovery
The BSP forecasts average inflation of 6.1% in 2026, 6% in 2027 and 3.3% in 2028. Its 2027 estimate was raised from 5.4%, showing concern that price pressure will persist well beyond the current year. Average inflation in 2025 was 1.7%.
Deutsche Bank expects lower inflation than the BSP, at 5.7% in 2026 and 4.2% in 2027, but still sees a possible further increase in rates. It believes the strongest inflation effects of El Niño could shift into the first quarter of 2027. January inflation data will be available before the February policy meeting.
Bank of America forecasts inflation of 6% at the end of 2026 and 5.2% at the end of 2027, reflecting continued exposure to imported oil shocks. It expects GDP growth of 2.5% in 2026 and 3.5% in 2027.
Pantheon cut its growth forecasts to 2.4% for 2026, from 2.8%, and to 3% for 2027, from 4%. Deutsche Bank lowered its projections to 2.9% and 5%, respectively. HSBC projects 3.2% and 4.8%, while warning that the weak GDP result creates risks of lower growth.
Government spending is central to the expected recovery. The BSP anticipates a pickup in the fourth quarter or the first quarter of 2027 as spending accelerates. HSBC has urged faster implementation of infrastructure projects financed from abroad and lower food import barriers to support activity and ease prices.
The dates shaping the next decision
The December 17 meeting will bring together evidence of weaker output, stubborn core inflation and changing energy costs. The November inflation reading is the next major price indicator identified by economists, although no release date was specified.
- April 2026: The BSP began raising rates as energy shocks linked to the Middle East war pushed inflation higher.
- October 22: The Monetary Board raised the policy rate by 50 basis points to 5.5%.
- October 27: The peso reached P64.17 per dollar.
- November 5: The PSA announced October inflation of 7.8%.
- November 9: The PSA reported third quarter GDP growth of 2.1%.
- December 17: The BSP holds its final scheduled policy meeting of 2026.
- February 2027: Several banks expect another rate increase, with January inflation available for consideration.
The immediate choice is whether to hold at 5.5% or add another quarter point. The growth slump strengthens the case for waiting, while rising core prices give the BSP a reason to keep restraining demand. Households and businesses face continued pressure under either option until price increases ease and spending recovers.
Key Points
- Philippine GDP grew 2.1% in the third quarter, marking a fifth consecutive slowdown.
- Growth averaged 2.5% through September, below the government's annual target of 3.5% to 4.5%.
- October inflation reached 7.8%, while core inflation rose to 5.4%.
- The BSP policy rate stands at 5.5% after increases totaling 125 basis points since April.
- Economists are divided between a December pause and a quarter point increase.
- The next scheduled policy decision is December 17, with some banks expecting further tightening in February 2027.