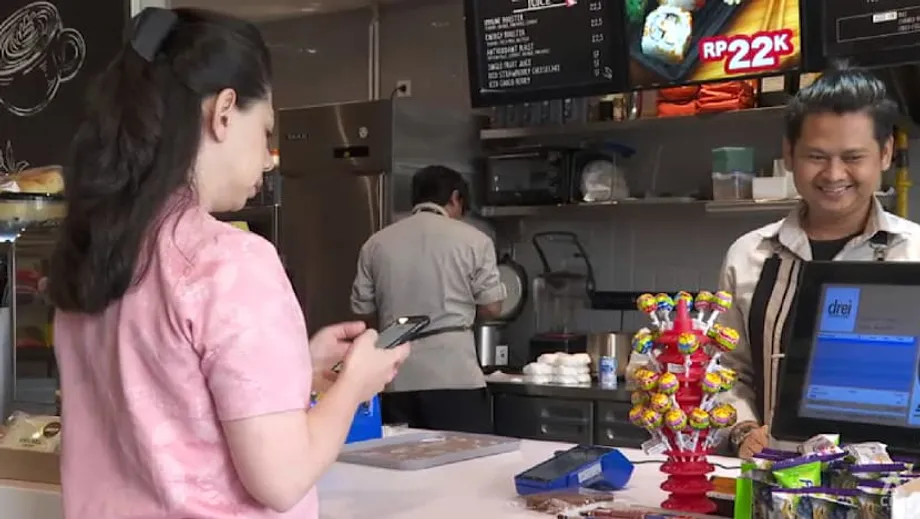
Billions of payments, one shared code
Indonesia's QR payment system handled more than 6 billion transactions in 2024 and has an estimated 57 million users. From a bowl of soto to a department store purchase, the same payment standard now connects millions of everyday purchases to banks and digital wallets.
Contents
- Billions of payments, one shared code
- How a scan replaced a patchwork of payment codes
- Why the price matters to small businesses
- How policy and the pandemic helped establish a habit
- Why QRIS became part of a trade dispute
- Travelers take familiar payment apps overseas
- Japan launches while China tests a connection
- Fraud protection and reliability face a larger test
- What Indonesia shares with India and China
- How far can regional payment links reach?
- What to watch for the rest of 2025
- At a Glance
Quick Response Code Indonesian Standard, known as QRIS, rolled out nationally in 2020. Its central promise was simple: a merchant could display one QR code, and customers could pay through any participating banking app or electronic wallet. Businesses no longer needed a different code for every provider.
By September 20, 2025, that domestic transformation had become an international story. Indonesia had connected QR payments with Malaysia, Thailand and Singapore, launched an initial stage of acceptance in Japan, and begun testing a link with China. The United States had also identified QRIS as a trade barrier, bringing an everyday checkout tool into a debate about foreign market access and national control of payment infrastructure.
The stakes reach beyond convenience. Small businesses can accept digital payments without expensive terminals, travelers can use familiar apps overseas, and more retail spending can move through domestic systems. Banks and payment companies must also keep the service reliable, protect customers against fraud, and fund infrastructure capable of handling rapidly growing traffic.
How a scan replaced a patchwork of payment codes
Before QRIS, a shop might display several QR codes, each belonging to a different bank or wallet. A customer needed to find the code that matched their app. Bank Indonesia and payment industry participants replaced that fragmented arrangement with a common standard.
A customer now opens a participating app, scans the merchant's QRIS code, checks the amount and authorizes payment. Licensed switching providers and participating banks handle the routing and settlement behind the scenes. Switching means directing the payment between providers; settlement is the process that delivers the money to the merchant's account.
QRIS follows international QR specifications while allowing domestic providers to work together. That ability, called interoperability, means competitors share a payment format even as they compete for customers. As more shops accept the code, it becomes more useful to consumers. As more consumers use it, more shops have a reason to join.
Many transactions have no minimum payment, and funds reach merchants quickly. A basic printed code can replace equipment that would otherwise make accepting digital payments expensive for a small seller. Customers can carry less cash, while merchants reduce the risks associated with handling it.
QRIS therefore changed the payment experience without requiring customers to abandon their preferred app. The common format, rather than a new scanning technology, was the key change. Once consumers could use one familiar process across many businesses, transaction volumes grew into the billions.
Why the price matters to small businesses
Card payments often require a terminal and carry a merchant discount rate of 2 to 3 percent. The merchant discount rate is the fee a business pays for accepting a payment. Most QRIS merchants face a much lower fee, near 0.3 percent, while micro merchants often pay zero.
For a warung owner or market seller working with thin margins, the difference affects how much remains from each sale. QRIS also offers settlement that can be faster than traditional card processes, helping businesses use their takings sooner. Many small sellers that previously preferred cash can accept digital payments with a printed code linked to a bank or wallet account.
Indonesia now has tens of millions of outlets accepting QRIS, the vast majority belonging to micro, small and medium enterprises, or MSMEs. The practical gains range from simpler reconciliation, which means matching sales with incoming payments, to less cash handling. The same setup can serve a fruit stand in Makassar or a batik shop in Solo.
Industry figures through 2024 showed annual transaction growth above 200 percent in several months, more than 50 million users and more than 33 million merchants. Those figures describe the scale already reached during that period; the broader user estimate stands at roughly 57 million.
Stable infrastructure, continuing education campaigns and growing smartphone ownership have supported that expansion. For tourist destinations, digital acceptance also makes it easier for local businesses to receive spending from regional visitors.
How policy and the pandemic helped establish a habit
Research examining the rollout during COVID-19 found that central bank policy and perceived pandemic risk both influenced people's intention to use QRIS. Clear rules and public education helped households and merchants try a payment method that reduced contact.
Survey research from that period identified the perceived influence of central bank policy and the desire to avoid health risks as the strongest motivations to try QRIS, beyond the usual factors affecting technology adoption. Bank Indonesia's communications helped build confidence in the system.
Merchant registration, simple payment steps and public explanations helped turn an initial experiment into a routine. As mobility recovered, the habit continued. A growing number of places to pay made the service increasingly convenient, encouraging further use.
QRIS also brings informal businesses closer to the formal financial system. Digital transaction records can help lenders assess small merchants that lack collateral or an established borrowing history. Extensions supporting QR transfers, cash deposits and cash withdrawals through agents help people living far from bank branches move and access money.
The experience shows how rules, communication and ease of use work together. A common technical standard gave providers a shared foundation, while policy and everyday familiarity helped persuade customers and sellers to use it.
Why QRIS became part of a trade dispute
The United States identified QRIS as a trade barrier in its 2025 National Trade Estimate. Its criticism concerned implementation that it said limited foreign firms' access and reduced transparency, alongside concerns about Indonesia's domestic card network, GPN.
The dispute developed amid threats of a 32 percent tariff on Indonesian goods. That tariff measure was later paused for talks. The American concerns centered on market access and governance, while Indonesian regulators pointed to participation under domestic rules and continuing connections with overseas payment systems.
For Indonesian officials and many economists, domestic payment processing also serves economic resilience. Keeping retail payments on local infrastructure can lower fees and safeguard transaction data. Where cross border payments settle in local currency pairs, the approach can also reduce exposure to currency swings.
Indonesian banks continue to issue and accept Visa and Mastercard, and those networks remain preferred for many international transactions. QRIS adds another payment route, with particular attractions for smaller purchases and merchants sensitive to acceptance costs.
Bank Indonesia Governor Perry Warjiyo described the balance between international standards and Indonesia's domestic priorities:
QRIS was built on international frameworks but tailored to Indonesia's needs, playing an important role in digitalisation, economic inclusion, and efficiency.
Regulators have signaled that international companies can participate if they meet the same public interest obligations as domestic firms. Indonesia's position combines greater control over payment infrastructure with cooperation abroad, reflecting a wider Southeast Asian effort to process more retail payments locally while connecting national systems for tourism and trade.
Travelers take familiar payment apps overseas
Indonesia's links with Malaysia, Thailand and Singapore allow Indonesian travelers to scan participating merchant codes abroad through their existing apps. Visitors from those countries can likewise use their own apps at participating businesses in Indonesia.
The attraction is a familiar payment process across a border. Merchants receive their local currency, and settlement takes place in the local currency pair without card conversion. For a small business serving tourists, the connection can bring new customers without requiring another device or a pricing change.
Data from border cities suggests young Malaysian visitors in places such as Batam are already adopting QR scanning as a default payment method. Wider acceptance could make everyday travel spending, student purchases and small transactions across borders more like paying at home.
The expansion has moved through several stages:
- 2020: QRIS rolled out nationally, bringing participating Indonesian banks and wallets under one QR payment standard.
- 2024: Transactions exceeded 6 billion, while industry figures during the year showed users above 50 million and merchants above 33 million.
- 2025: The United States identified QRIS as a trade barrier amid a wider tariff dispute and subsequent talks.
- August 2025: Bank Indonesia and Japanese partners launched the first stage of QRIS acceptance in Japan.
- By September 20, 2025: Indonesia was testing a payment link with China alongside its established connections with Malaysia, Thailand and Singapore.
Japan launches while China tests a connection
Japan's initial launch allows Indonesian users to pay at selected merchants by scanning JPQR Global codes through domestic apps from major banks and electronic wallets. Bank Indonesia, Indonesia's payment system association and Japanese industry bodies are involved under regulatory oversight.
The plan is to increase merchant coverage and develop more payment flows in both directions. Greater acceptance would support tourism and small business commerce between Indonesia and Japan, extending the usefulness of apps that Indonesian customers already use at home.
China's connection remains a pilot. UnionPay International and Indonesian switching providers are leading tests that let selected users pay at participating merchants in each country through their home apps. Both central banks supervise the program.
Local currency settlement is a central feature: yuan in China and rupiah in Indonesia. Using those currencies reduces conversion steps and costs. The program is expected to expand after testing, but no date was given for a wider launch or for the planned expansion of Japan's coverage.
Bank Indonesia Deputy Governor Filianingsih Hendarta described preparations for the China connection:
Cooperation for QRIS expansion in China is progressing positively, with agreements signed to finalise business, technical and operational arrangements for a smooth implementation.
Further connectivity with markets such as India, Saudi Arabia and South Korea, together with broader coverage in Japan, could extend QR payments across much of Asia. Those ambitions depend on additional connections and acceptance, while the current projects focus on making the existing links work for consumers and businesses.
Fraud protection and reliability face a larger test
Indonesians report growing concern about scams, and only a small share say they feel immune to fraud. As QRIS processes more payments, banks and payment companies are working on stronger identity verification and fraud scoring that assesses risk as a transaction happens, sometimes using machine learning.
Shared fraud intelligence can help institutions recognize suspicious patterns that cross company boundaries. Central coordination matters because a risky transfer may need to be blocked or redirected before the money leaves the system.
A growing share of transactions also moves between different providers rather than staying inside one bank. More payments therefore depend on national switching and settlement infrastructure, increasing the importance of capacity management and cyber defense.
Redundancy, which provides backup systems when equipment fails, and stress testing, which checks performance under heavy demand, become more important as volumes rise. Customers and merchants also need clear ways to dispute a payment or resolve a problem.
Regulators have adjusted merchant discount rates to protect small sellers and updated rules as QRIS has become a routine checkout option. Low fees help businesses join and remain active, while the network still requires investment to support reliability and protection.
The framework for safer growth brings together clear compliance rules, cybersecurity that keeps pace with threats, accessible consumer protection, coordination across borders, and cooperation among banks, financial technology companies and law enforcement. Those measures help preserve the speed of payment while protecting users as services become more complex.
What Indonesia shares with India and China
India's Unified Payments Interface, or UPI, offers a comparison with Indonesia's approach. A model led by the regulator requires competing apps and banks to work together. QRIS similarly made interoperability central, replacing separate provider formats with a common payment standard.
China developed along a different route. Private super apps led its early growth before regulators moved to standardize payments and direct more traffic through national infrastructure. Indonesia's model draws from both experiences, prioritizing inclusion and cost while retaining ways to connect with international partners.
QRIS sits alongside other parts of Indonesia's payment system. Domestic retail bank transfers use infrastructure including BI-FAST. Work on a digital rupiah also continues for wholesale uses, meaning transactions within the financial system, to modernize core settlement.
The aim is to connect these systems so each can serve the transactions it handles best. QRIS focuses on accessible retail payments, while other infrastructure supports bank transfers and settlement. Common standards and clear governance allow new services to develop without sending consumers back to a confusing collection of incompatible payment formats.
How far can regional payment links reach?
Some strategists see QRIS as a model for countries seeking greater financial autonomy. Global card networks and the SWIFT messaging network occupy central positions in international payments, and global platforms will remain important for large transactions. Connected national QR systems offer another route for smaller consumer purchases.
A group of countries linking its QR standards could route tourism and small merchant spending through domestic infrastructure, with settlement in local currencies. That approach can reduce costs and foreign exchange friction while keeping more transaction data local.
The concept fits with Asian projects connecting fast payment systems and experiments involving digital currency settlement between central banks. Indonesia's experience points to three practical requirements: standards that work across providers, central bank leadership, and companies willing to share rules while competing on service.
Reciprocal connections matter because travelers and businesses benefit most when payments can move in both directions. A broader regional network would complement the global systems that continue to carry wholesale finance, while giving consumers and smaller merchants more options.
What to watch for the rest of 2025
Japan's merchant coverage and China's pilot are immediate measures of QRIS's international progress. Their scale, the development of payment flows in both directions, and the share of transactions settled in local currency pairs will show how much practical use the connections provide.
United States trade discussions could influence foreign access rules and the willingness of other countries to connect. Within Indonesia, another priority is narrowing adoption gaps between Java's dense merchant network and provinces farther east in the archipelago.
Peak travel periods will test fraud controls, dispute handling and service reliability. The financial balance also matters: merchant fees must remain attractive to small sellers while supporting the national switching and settlement infrastructure as volumes grow toward tens of billions of transactions.
QRIS has already made a common payment code part of daily commerce. Its next stage brings that domestic model into contact with overseas merchants, foreign regulators and a larger set of operational demands.
At a Glance
- QRIS rolled out nationally in 2020 and processed more than 6 billion transactions in 2024, with users now estimated at roughly 57 million.
- A shared QR code lets participating banking apps and wallets pay the same merchant, reducing the need for separate codes and costly terminals.
- Most merchants face fees near 0.3 percent, while micro merchants often pay zero, compared with typical card fees of 2 to 3 percent.
- Indonesia has payment links with Malaysia, Thailand and Singapore, initial acceptance in Japan, and a supervised pilot with China.
- The United States identified QRIS as a trade barrier in 2025; Indonesia supports international participation under domestic rules.
- Small business inclusion, fraud protection, reliable infrastructure and wider regional acceptance remain central to QRIS's expansion.