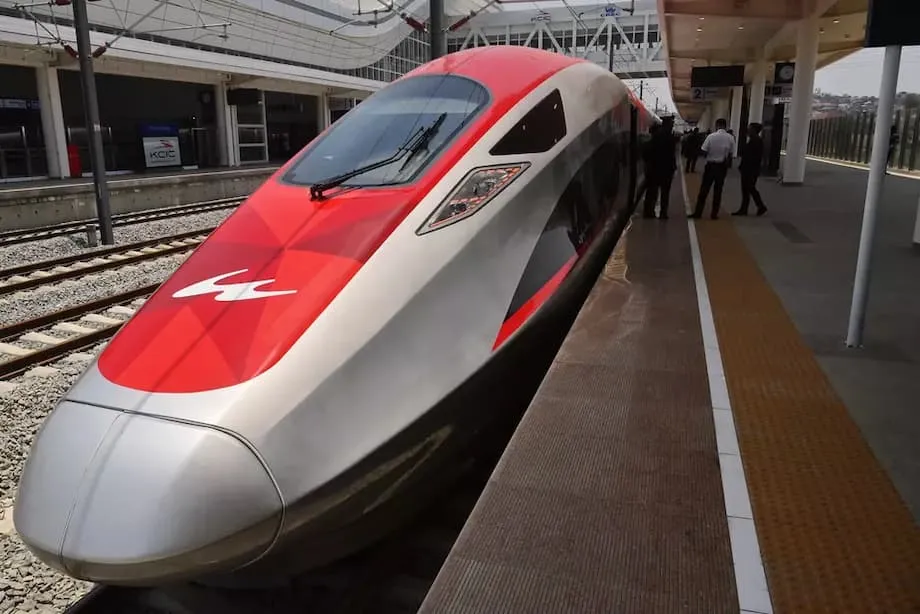
A popular railway faces a growing financial strain
Indonesia is preparing to reopen negotiations with China over the loans behind Whoosh, the Jakarta to Bandung high speed railway, as state railway operator Kereta Api Indonesia (KAI) faces mounting pressure from the project. As of September 16, 2025, State Owned Enterprises Minister Erick Thohir is seeking a solution that protects KAI's wider services while keeping the flagship railway running.
Contents
- A popular railway faces a growing financial strain
- How construction costs became a debt burden
- Who owns the railway and carries the exposure?
- Why more passengers have not closed the gap
- What separating tracks from train operations could change
- Danantara's review and KAI's warning
- What could change in negotiations with China?
- Connections and fares will shape revenue growth
- Why the Surabaya extension depends on a financial reset
- Protecting public services and the state budget
- What to Know
The scale of the problem is substantial. Whoosh cost about 119.6 trillion rupiah, or 7.3 billion dollars, with 75 percent financed by the China Development Bank. Its original loans carried annual interest near 2 percent, while an additional loan covering construction cost overruns carried a higher rate of 3.4 percent. KAI recorded 1.24 trillion rupiah in losses linked to the line in the first half of 2025.
Passengers have continued to use the service in growing numbers. Whoosh carried 2.9 million people in the first half of 2025, about 10 percent more than a year earlier. Since operations began in October 2023, it has reduced the 142 kilometer journey between Jakarta and Bandung to about 45 minutes, changing travel patterns across West Java.
Erick has proposed separating responsibility for running trains from responsibility for infrastructure. Under that option, KAI would concentrate on operations while the state took responsibility for assets such as tracks and stations. Indonesia's sovereign investment arm, Danantara, is also working with KAI on restructuring options. The government says the planned extension to Surabaya will not receive approval until the existing debt is on a sustainable footing.
How construction costs became a debt burden
Whoosh's financing combines shareholder investment with a large bank loan. Shareholders supplied a quarter of the funding, known as equity, while the China Development Bank provided the remaining three quarters through a senior loan to project operator PT Kereta Cepat Indonesia China (KCIC). A senior loan has priority for repayment over lower ranking financial claims.
The original annual interest rate of about 2 percent appeared manageable when the construction budget was smaller and the timetable tighter. Even a relatively low interest rate, however, produces a large bill when it applies to borrowing worth billions of dollars.
The pandemic disrupted supply chains, and lockdowns slowed work. Land acquisition also took longer than expected. Indonesia and China agreed that another 18 trillion rupiah, about 1.2 billion dollars, was needed to finish the railway. The additional borrowing came at 3.4 percent interest, raising both the amount owed and the combined cost of borrowing while the operating teams were still dealing with early service problems.
The main financial and operating milestones are:
- During construction, pandemic disruption and land acquisition delays helped push costs up by about 18 trillion rupiah, or 1.2 billion dollars.
- In October 2023, Whoosh began operations between Jakarta and Bandung.
- In 2024, the companies in the Indonesian shareholder consortium posted losses of around 4.2 trillion rupiah.
- In the first half of 2025, Whoosh carried 2.9 million passengers, while KAI recorded 1.24 trillion rupiah in losses linked to the line.
- As of September 16, 2025, Indonesia was preparing renewed loan talks, with Danantara's assessment still under way.
Who owns the railway and carries the exposure?
KCIC is a joint venture between Indonesian and Chinese investors. Pilar Sinergi BUMN Indonesia (PSBI), the Indonesian shareholder vehicle, owns 60 percent. The Chinese consortium Beijing Yawan HSR owns the remaining 40 percent.
PSBI is controlled by state companies including KAI, construction company Wijaya Karya, toll road operator Jasa Marga and plantation company Perkebunan Nusantara VIII. KAI holds the largest domestic stake in KCIC through that consortium, making the railway's financial performance a concern for Indonesia's broader state enterprise sector.
The loan and ownership arrangements connect several businesses to the same project. KCIC receives the senior financing, while PSBI and Beijing Yawan HSR supply shareholder capital. Losses and additional funding requirements therefore put pressure on companies whose responsibilities extend beyond the high speed railway.
KAI's losses linked to Whoosh in the first half of 2025 were lower than in the same period of 2024, but the 1.24 trillion rupiah total remained a heavy drag. PSBI companies' losses of around 4.2 trillion rupiah in 2024 added to concern about the strain on businesses that provide essential public services.
Why more passengers have not closed the gap
Whoosh's passenger growth has been steady, but current demand remains below the original forecasts cited by officials and lawmakers. Some projections assumed 50,000 to 76,000 passengers a day during the early period of stable operations. Legislative briefings put actual occupancy closer to 40 to 50 percent of the pessimistic scenario.
Ticket sales are estimated at around 1.5 trillion rupiah a year for now. KAI reportedly faces close to 2 trillion rupiah in annual interest payments related to the project. Comparing those figures puts estimated ticket revenue about 500 billion rupiah below the interest bill, before allowing for the full cost of operating and maintaining the railway or repaying the borrowed principal.
Principal is the original amount borrowed. Amortization means paying that amount back in scheduled installments. Whoosh needs enough cash for those repayments as well as interest, maintenance and daily operations. Its present ticket income covers part of its expenses and maintenance, but falls short of meeting the full financing burden.
New railways also need time to build regular demand. Passenger numbers depend on fares, reliability and how easily people can reach stations or complete the final part of their journey. Whoosh has demonstrated the appeal of fast intercity rail, but the financial costs of construction arrived before ridership reached the levels once expected.
What separating tracks from train operations could change
Erick's proposed model would leave KAI responsible for trains, timetables and service quality, while the state assumed responsibility for core infrastructure, including tracks, power systems and stations. The aim is to reduce the burden of assets designed to last for decades and the borrowing used to build them on KAI's balance sheet.
A balance sheet records what a company owns and owes. Moving infrastructure to a public owner could change where the associated assets and debt sit. KAI could then pay a track access charge or concession fee, essentially a negotiated payment for using the railway, while concentrating management attention on revenue and service.
The proposal also seeks to reduce interest costs at the operating company and remove depreciation charges for infrastructure that KAI would no longer own. Depreciation is the accounting expense that spreads an asset's cost over its useful life. A public owner could use borrowing with a longer repayment period, better matching the lifespan of tracks and stations.
Many railway systems separate infrastructure ownership from train operations. A public infrastructure owner can pursue financing backed by the state, multilateral loans, local bonds or a mix of funding sources with a lower coupon, meaning the interest paid on a bond. The access fee can reflect both the railway's commercial prospects and its public value through faster journeys and stronger links between cities.
Indonesia would likely need oversight to ensure that any access fee encouraged efficient operations while recognizing those wider benefits. The asset split remains an option under discussion; no final financing agreement, fee arrangement or completion date for the restructuring has been announced.
Danantara's review and KAI's warning
Danantara has made Whoosh a priority and is working with KAI on restructuring KCIC's debt and adjusting the distribution of shareholder exposure. Its mandate gives it flexibility to bring in fresh capital, refinance parts of the loan or arrange a structure that lowers the immediate cash burden on KAI and other PSBI companies.
Dony Oskaria, Danantara's operations chief, confirmed that the assessment was active and moving forward. He said the assessment process was ongoing and would be completed soon, with the intended solution to be included in the fund's formal work plan for the year.
Bobby Rasyidin, KAI's new president director, has warned lawmakers that the project's finances require action. At a parliamentary hearing, he described the KCIC issue as resembling a time bomb, with the debt load straining KAI's performance unless restructuring moves ahead. He stressed close coordination with Danantara to protect KAI's broader operations.
Indonesia has also injected 1.8 trillion rupiah into KAI in 2025. Officials say that money is earmarked for expanding commuter rail in Greater Jakarta, rather than refinancing Whoosh. Protecting those separate responsibilities is central to the restructuring effort: KAI must continue serving other passengers while addressing its exposure to the high speed project.
What could change in negotiations with China?
Indonesia could seek a lower interest rate, a longer loan maturity, a grace period on principal repayments or a combination of those measures. A lower rate reduces the cost of borrowing. A longer maturity spreads repayment over more years, while a grace period postpones scheduled principal payments as passenger revenue develops.
Government to government talks could prepare the ground for formal changes to the China Development Bank's loan terms. Danantara could also coordinate refinancing of part of the existing loan, potentially using domestic bonds or funding shared with multilateral institutions. Asset separation would create another route for financing infrastructure over a longer period.
Each measure addresses a different part of the cash pressure. Reduced interest would lower the recurring financing bill; a longer repayment schedule or grace period would ease immediate demands. Combining them could give the operating company more time to build revenue while maintaining service.
Whoosh also carries diplomatic weight. It is Southeast Asia's first true high speed rail service, a prominent project within China's Belt and Road initiative and a symbol of closer ties between Indonesia and China. It is often discussed in high level meetings. That visibility can support goodwill for changes to the financing, while requiring both sides to consider the political signal of interest reductions or changes in how partners share risk.
Connections and fares will shape revenue growth
Whoosh's roughly 45 minute journey is a fraction of the time needed to travel by car on congested highways. The service supports business travel, tourism and regional integration across Java, while increasing demand for feeder trains that connect passengers to the high speed line.
Passengers can use a short shuttle connection to Bandung city station. At Jakarta's Halim terminal, connections include the Jakarta LRT and other services. Better links between these networks could strengthen demand by making the whole journey easier, rather than improving only the time spent on the high speed train.
In Jakarta, reliable connections with the LRT, bus rapid transit and commuter rail could make Halim more accessible. In Bandung, direct links to the city center could shorten travel from a passenger's starting point to the final destination. Integrated tickets or discounts for combined journeys are possible ways to make transfers more convenient.
Pricing offers another tool. Dynamic fares change according to demand, the time of day or the day of the week. Promotional prices have already introduced more riders to Whoosh. Work with tourism boards, universities and conferences could help fill trains during quieter periods.
Stations and nearby land also offer potential income from shops, parking, advertising and joint development. Turning station areas into places for business and leisure could bring in revenue without raising base fares too quickly. Even with those opportunities and continued passenger growth, management still needs a debt arrangement suited to the pace at which the railway's income develops.
Why the Surabaya extension depends on a financial reset
President Prabowo Subianto has expressed support for extending Whoosh east to Surabaya. Erick has said the government will not approve the extension until the existing railway's debt is stabilized. The larger route would increase the project's scale and possible benefits, while also expanding the financing challenge.
The government is preparing a refreshed regulatory framework for the extension. It is expected to address land acquisition timelines, contract management and the role of private investors alongside state participants. Lessons from the first phase include making land acquisition more predictable, coordinating designs with other transport projects earlier and matching construction schedules to realistic passenger growth.
Before construction proceeds further east, officials need clarity about who owns the assets, who pays access charges and how financial risks are shared. Those decisions would establish the business model for the current railway and provide a basis for financing a larger corridor.
A second phase would likely involve construction in stages, realistic assumptions about the growth of ridership and a mix of funding sources that spreads risk over time. A wider corridor would also increase the importance of coordinating with freight and conventional passenger services. Planners would need connections and timetables that reduce conflicts and improve capacity across Java's railway network.
Protecting public services and the state budget
Indonesia has already supported the railway through policy backing for KCIC and capital injections into related companies. Restructuring is intended to keep Whoosh's financial problems from weakening KAI and other state businesses. Any transfer of infrastructure or debt to the state would also require careful management of the resulting public financial burden.
Officials and commentators have pointed to the experience of countries that struggled with large external debts linked to infrastructure. Indonesia has a large domestic market, an operational railway with growing passenger use and financing options through Danantara and other mechanisms. Those advantages give it several ways to pursue a solution.
The central task is to match debt payments to realistic cash flow while keeping trains running, fares reasonable and KAI's core business protected. Moving obligations between organizations needs to be accompanied by terms that genuinely reduce financial pressure. A combination of revised loans, infrastructure financing and stronger revenue could give the service time to develop without squeezing passengers or other railway operations.
Whoosh's popularity and its debt burden now form two parts of the same policy decision. Indonesia wants to preserve the faster travel that passengers already use while putting the cost of building that railway on a repayment schedule its operators can manage. The outcome will also shape whether, and under what financial model, the service can expand toward Surabaya.
What to Know
- Indonesia is preparing to renegotiate Whoosh's loans with China to ease pressure on KAI.
- The project cost about 119.6 trillion rupiah, or 7.3 billion dollars, with 75 percent financed by the China Development Bank.
- Original loans carried interest near 2 percent; the loan for construction overruns carried 3.4 percent.
- Whoosh carried 2.9 million passengers in the first half of 2025, about 10 percent more than a year earlier.
- KAI recorded 1.24 trillion rupiah in losses linked to the railway during that period.
- One proposed model would leave KAI running trains while the state assumed responsibility for tracks, power systems and stations.
- Danantara is assessing restructuring options, including changes to borrowing terms and shareholder exposure.
- KAI's 1.8 trillion rupiah capital injection in 2025 is allocated to Greater Jakarta commuter rail, rather than Whoosh refinancing.
- The government says approval for the Surabaya extension depends on stabilizing the existing project's debt.