A smaller deficit, but a substantial debt bill
Malaysia reduced new government borrowing from RM100 billion in 2022 to RM76.8 billion in 2024, while setting a fiscal deficit target of 3.8% of gross domestic product for 2025. The improvement comes with a substantial debt burden: federal government debt reached RM1.17 trillion at the end of 2023, equivalent to 64.3% of GDP.
Contents
- A smaller deficit, but a substantial debt bill
- What is driving the spending gap?
- Why Malaysia borrows mainly in ringgit
- Legal limits and the test of sustainability
- Interest payments and inflation put pressure on budgets
- Tax changes seek a broader revenue base
- Subsidy savings alongside social support
- Growth forecasts expose the difficulty of the targets
- PETRONAS provides a buffer as pension costs rise
- Reforms must turn borrowing into lasting value
- The Bottom Line
Including government guarantees and other liabilities, that figure rose to RM1.53 trillion, or 84% of GDP. These obligations make the government's effort to narrow the gap between spending and revenue more than an accounting exercise. Interest payments, pensions, public services and development projects all compete for money from the same budget.
As of August 30, 2025, Malaysia's approach combines borrowing mainly in ringgit, changes to taxes and subsidies, and continued investment in education, healthcare and infrastructure. Prime Minister Anwar Ibrahim and Treasury officials have stressed that debt remains within legal limits and that the government is committed to reducing both the deficit and the debt ratio.
The central challenge is to keep borrowing manageable while supporting economic growth. Money borrowed for productive projects can help businesses expand and people find work. Projects that deliver weak returns leave future budgets carrying the repayment costs without a matching increase in national income.
What is driving the spending gap?
Malaysia recorded a fiscal deficit of RM91.4 billion in 2023, equal to 5% of GDP, down from 5.6% in 2022. The deficit was projected to narrow to 4.1% in 2024, followed by the target of 3.8% in 2025. GDP measures the value of goods and services produced by an economy; expressing the deficit as a share of GDP helps show its size relative to the country's resources.
Government revenue is sufficient to cover operating expenses, including salaries, pensions and subsidies. The shortfall arises from development spending on infrastructure, energy and other projects intended to deliver benefits over many years. Current revenue cannot fund all of that investment, so borrowing fills the gap.
Borrowing for development can be sound fiscal policy when the investment produces enough economic value to justify its cost. A government still spends more than it receives when it runs a deficit, however, and the money borrowed must be serviced and eventually repaid.
The fiscal timetable shows the intended pace of adjustment:
- 2022: The deficit stood at 5.6% of GDP, and new borrowing amounted to RM100 billion.
- 2023: The deficit fell to 5% of GDP, or RM91.4 billion, and the Public Finance and Fiscal Responsibility Act 2023 was enacted.
- 2024: The deficit was projected at 4.1% of GDP, while new borrowing declined to RM76.8 billion.
- 2025: The government targeted a deficit of 3.8% of GDP.
- 2026: The government aimed to bring the deficit down to 3% of GDP.
The deficit narrowed for three consecutive years. New borrowing fell by RM23.2 billion between 2022 and 2024, a reduction of 23.2%, although continued deficits still add to the debt stock.
Why Malaysia borrows mainly in ringgit
Domestic debt accounted for 97.5% of government debt at the end of 2023, amounting to RM1.14 trillion. Offshore loans represented the remaining 2.5%, or RM29.8 billion. Malaysia therefore finances almost all its borrowing in its own currency.
Borrowing in ringgit reduces exposure to exchange rate changes. When a government owes money in a foreign currency, a fall in the value of its own currency makes that debt more expensive to repay. Malaysia's borrowing strategy also helps reduce vulnerability to sudden capital outflows that can destabilize economies with large foreign debt burdens.
Domestic borrowing brings a different concern. The government draws heavily on the local bond market, where it raises money by selling debt securities to investors. Private companies also need financing, and a government absorbing a large share of domestic credit can put upward pressure on borrowing costs.
Economists call this effect crowding out: government demand for funds can leave businesses facing more expensive loans or fewer financing opportunities. Academic studies and international experience identify persistent deficits and heavy domestic borrowing as possible causes. In Malaysia, concern centers on whether government borrowing limits private sector expansion, entrepreneurship and job creation.
Legal limits and the test of sustainability
Malaysia's statutory debt, comprising Malaysian Government Securities, Investment Issues and Islamic Treasury Bills, remained below the legal ceiling of 65% of GDP. The government's broader objective is to bring the debt ratio down to 60% over the medium term.
The Public Finance and Fiscal Responsibility Act 2023 provides the framework for that effort. It requires parliamentary approval for adjustments to fiscal targets and mandates that the overall debt level stay below 60% of GDP in the medium term. The framework is intended to give investors and credit rating agencies confidence that the government will maintain fiscal discipline.
Debt sustainability means being able to meet repayment and interest obligations while continuing to support economic activity and social stability. The size of the debt matters, but so do the cost of borrowing, the strength of growth and the results of the spending financed by loans.
Malaysian Rating Corporation Bhd (MARC), a credit rating company, assessed the deficit target and explained how economic growth can reduce the debt ratio:
Malaysia's fiscal deficit target of three per cent by 2026 remains challenging but achievable... Higher economic growth relative to borrowing costs would lead to passive deleveraging, naturally lowering the debt-to-GDP ratio.
Passive deleveraging means the economy grows faster than the burden of debt, causing debt to shrink relative to GDP. Malaysia's growth rate exceeded its borrowing costs in most years, helping keep debt manageable. Slower growth in 2023 turned that difference negative, underlining how much the fiscal position depends on economic expansion.
Interest payments and inflation put pressure on budgets
Higher debt brings larger interest payments, leaving less money available for essential services and development. Even when borrowing is mostly domestic, repayment costs can reduce the government's flexibility to respond to a global downturn, a commodity price shock or another crisis.
Businesses can also feel the effects through the credit market. If government borrowing raises interest rates, firms may postpone investment or struggle to secure affordable funding. That can slow business formation, expansion and hiring, weakening the growth that helps support public finances.
Research also indicates that fiscal deficits can contribute to inflation, particularly when financed through domestic borrowing. Malaysia kept inflation relatively low at 1.8% in 2024, but continued deficit spending carries a risk of higher prices, especially if political instability or external shocks weaken confidence in fiscal management.
Inflation reduces what households can buy with the same amount of money. For the government, rising prices can also make the delivery of services and development projects more expensive, adding another source of pressure to the budget.
The International Monetary Fund (IMF) has warned that high public debt, slow growth and rising interest rates pose risks to financial stability worldwide. Countries with little room in their budgets can find it harder to support their economies during downturns. Excessive debt can also increase vulnerability to capital outflows and currency depreciation. Malaysia's reliance on domestic borrowing reduces some of these risks, while leaving a limited margin for fiscal mistakes.
Tax changes seek a broader revenue base
Malaysia has expanded the Sales and Services Tax (SST) and is considering further tax reforms to broaden its revenue base. The aim is to collect enough income to support spending while reducing dependence on borrowing.
Reintroducing the Goods and Services Tax (GST) could generate more revenue, but officials have chosen a more targeted approach to avoid placing too much pressure on consumers. Their focus is on taxing goods and services considered nonessential while exempting basic necessities.
Tax compliance and stronger enforcement have also helped improve collection. Federal government revenue rose by 3% compared with a year earlier in the first quarter of 2025, driven by higher sales and service tax receipts and stronger individual income tax collection.
That increase supports the deficit reduction effort because more revenue allows the government to finance a larger share of spending without new debt. Sustained improvements depend on both the tax system and the economy: households and businesses need sufficient income and activity to generate reliable receipts.
Subsidy savings alongside social support
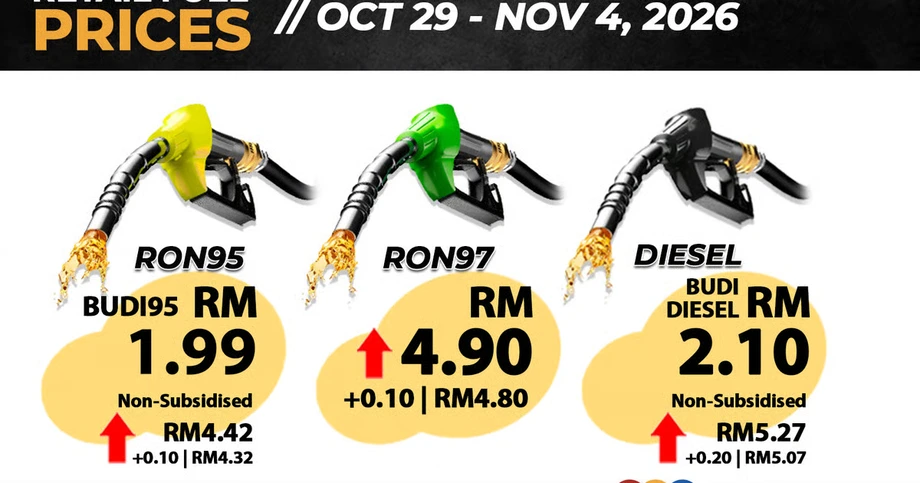
The government has retargeted subsidies, particularly for diesel, and optimized grants to statutory bodies. These changes have helped reduce total federal expenditure and shrink the deficit.
Retargeting subsidies means directing assistance toward intended recipients rather than providing the same support broadly. Malaysia has paired its spending adjustments with continued assistance through Sumbangan Tunai Rahmah (STR) and Sumbangan Asas Rahmah (Sara), which support vulnerable groups.
Education and healthcare allocations have increased despite the effort to restrain borrowing. The Education Ministry's budget rose to RM74 billion in 2025, while the Health Ministry received RM45 billion. Those allocations are intended to improve public services and infrastructure and support future growth.
The budget strategy therefore involves several choices at once: collecting more revenue, reducing less efficient spending, maintaining help for people who need it, and funding services that contribute to development. The quality of those decisions matters because smaller deficits achieved alongside productive investment offer a stronger foundation than borrowing reductions alone.
Growth forecasts expose the difficulty of the targets
Malaysia's economy grew by 5.1% in 2024, exceeding expectations. Private consumption, investment and trade were key drivers, supported by low inflation and a declining unemployment rate.
The growth projection for 2025 was 4.5% to 5.5%. The IMF lowered its forecast for Malaysia to 4.1%, citing the effects of US tariffs and global economic uncertainty. Weaker external demand, geopolitical tensions and disruptions to global trade remain risks to economic activity.
Slower growth makes deficit reduction harder in two ways. It can weaken tax collection as business activity and incomes grow less quickly, and it makes the economy a smaller base against which debt and the deficit are measured. Strong growth helps the same fiscal burden become more manageable relative to national output.
The government aims to reach a deficit of 3% of GDP by 2026 while bringing the debt ratio below 60% over the medium term. No specific year was given for reaching the debt target. If revenue falls short or unexpected spending increases, officials may need to adjust their plans or find additional sources of income.
The 2025 and 2026 targets consequently depend on continued policy discipline as well as economic conditions. The fall in new borrowing offers evidence of progress, while the weaker IMF growth forecast shows why maintaining that progress may become more difficult.
PETRONAS provides a buffer as pension costs rise
Malaysia's fiscal position benefits from contingent assets, including the financial strength of PETRONAS and sizeable sovereign wealth funds. PETRONAS contributed RM85.7 billion to government revenue in 2023, and liquid assets exceeded RM220 billion, equivalent to 12% of GDP.
Liquid assets are resources that can be turned into cash relatively readily. These financial resources provide a buffer against fiscal shocks and help reassure investors about Malaysia's ability to manage its obligations.
Government guarantees and other contingent liabilities create risks on the other side of the balance sheet. A guarantee is a promise that the government will cover an obligation if the borrower cannot meet it. Such commitments can become demands on public money when financial difficulties arise.
Pension obligations add a longer lasting spending pressure. Payments are rising rapidly, and the existing fund is insufficient to cover future obligations. The government has begun enrolling new public sector recruits in the Employees Provident Fund rather than traditional pension schemes, although further reforms may be needed to make those commitments sustainable.
Malaysia therefore needs to consider both its financial buffers and the obligations that could require future spending. PETRONAS and sovereign wealth resources strengthen its position, while guarantees and pension commitments help explain why the broader liabilities figure exceeds government debt alone.
Reforms must turn borrowing into lasting value
The IMF and other international organizations have praised Malaysia's fiscal reforms for supporting growth, social protection and macroeconomic stability. The Fiscal Responsibility Act, together with work on governance, digitalization and climate resilience, is intended to improve debt management and the gradual reduction of deficits.
Economists discussing Malaysia's debt and fiscal reforms offered a positive assessment of the country's economic foundations in a fiscal reform assessment:
Malaysia's sizable national debt does not pose a threat to the country's long-term prosperity, thanks to its strong economic fundamentals and prudent fiscal management.
The practical test is whether spending financed through borrowing improves productivity, competitiveness and employment enough to justify its cost. Investments that generate returns exceeding borrowing costs can strengthen the economy. Weak investments leave future generations with repayment obligations and fewer budget choices.
Malaysia's experience also offers lessons for other emerging economies managing similar pressures. Credible fiscal rules, productive investment, stronger revenue collection and careful spending can support stability and growth. High debt can become harder to manage quickly when growth weakens or an external shock hits.
For Malaysia, the task is concrete: maintain essential services and support for vulnerable households, make development spending count, and keep reducing the need for new borrowing. Domestic financing and substantial financial assets provide protection, but sustained growth and disciplined budget decisions remain central to meeting the government's targets.
The Bottom Line
- Malaysia's deficit fell from 5.6% of GDP in 2022 to 5% in 2023, with a projected 4.1% for 2024 and a target of 3.8% for 2025.
- New borrowing declined from RM100 billion in 2022 to RM76.8 billion in 2024.
- Government debt reached RM1.17 trillion at the end of 2023; guarantees and other liabilities brought the broader figure to RM1.53 trillion.
- Domestic debt represented 97.5% of government debt, reducing currency risk while increasing reliance on local financing.
- Tax changes, stronger collection and targeted subsidies support deficit reduction, alongside social assistance and larger education and health allocations.
- The government aims for a deficit of 3% of GDP by 2026 and a debt ratio below 60% over the medium term.
- PETRONAS and financial assets provide a buffer, while pension costs, guarantees and weaker growth remain fiscal risks.