September 1 deadline brings informal insurance deals into focus
China will explicitly prohibit agreements allowing employers and workers to opt out of mandatory social insurance payments from September 1, placing new pressure on businesses and employees who have exchanged future benefits for more cash today. Announced by the Supreme People's Court, the change targets arrangements that have allowed companies to avoid contributions, including contracts in which workers waive their right to coverage.
Contents
- September 1 deadline brings informal insurance deals into focus
- What workers and employers must pay for
- Why contribution enforcement is becoming urgent
- Small firms face a difficult cost calculation
- Household registration shapes access to benefits
- Medical insurance integration offers evidence of gains
- Health reforms can bring gains and extra expenses
- Fairness and trust influence participation
- Retirement changes confront a growing elderly population
- Healthcare coordination is part of the same reform effort
- Who bears the cost of stronger protection?
- Key Points
As of August 29, 2025, the approaching deadline presents a difficult choice for many of China's lowest paid workers. For years, millions have preferred higher take-home pay to contributions toward pensions, medical coverage and other benefits. The court has declared that employers offering cash incentives instead of mandatory insurance are violating the law.
China's welfare system already covers more than one billion people, but an aging population is increasing the need for dependable funding. The government's stated goal is to strengthen the system's financial sustainability and protect people as they grow older. Collecting contributions that businesses and workers have avoided is part of that effort.
Small businesses and households face a more immediate calculation: how much money will remain after contributions are paid? Business owners warn that higher employment costs could lead to lower wages, fewer jobs or closures. Workers who already struggle to meet daily expenses may receive better protection while having less money available each month.
September's change therefore connects two problems operating on different clocks. Families and employers must balance their budgets now, while pension and healthcare systems must prepare for a much larger elderly population over the coming decades.
What workers and employers must pay for
Social insurance in China covers five main areas: pensions, medical insurance, unemployment insurance, work injury insurance and maternity insurance. Together, these programs provide income or help with expenses when a person retires, becomes ill, loses a job, suffers an injury at work or needs maternity benefits.
Employers and employees both contribute. Rates vary by city, but typical contributions are described as about 10% of gross income for workers and 25% for employers, levels that are high by international standards. Another estimate puts employees' contributions at nearly 12% of their monthly salary. Workers' actual deductions depend on the applicable local rules.
Gross income means earnings before deductions. A worker's contribution reduces the money they receive, while the employer's contribution adds to the cost of employing that person. This explains why a cash payment in place of insurance can appeal to both sides, even though it leaves the worker without the protection those contributions would finance.
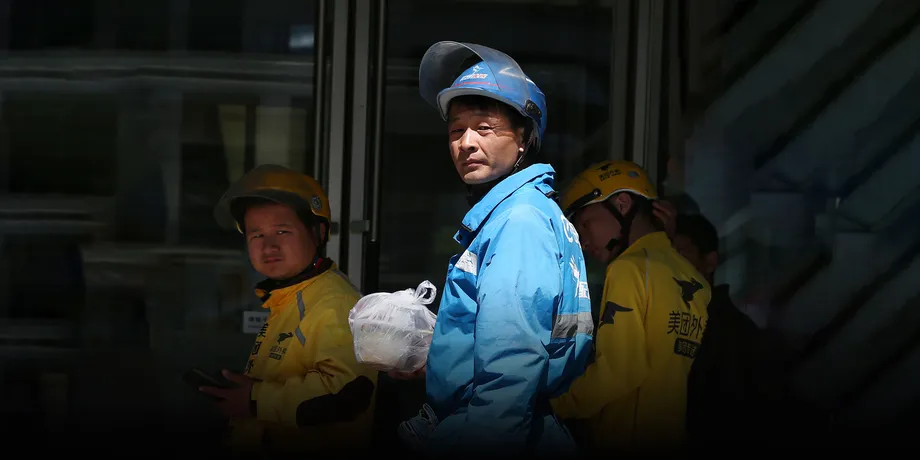
Minimum contribution rules make the burden especially heavy for some low earners. Contributions can be calculated using a minimum salary amount even when the worker earns less than that amount. The worker then pays insurance contributions based on a figure above their actual earnings, so the deduction takes a larger share of their income.
Urban employees generally receive more comprehensive benefits than rural residents and workers in informal employment. At the end of 2023, the average monthly pension for a retired urban employee was 3,700 yuan, compared with 223 yuan for rural residents. Using those figures, the urban employee pension was about 16.6 times the rural amount, illustrating how different retirement protection can be across the system.
Why contribution enforcement is becoming urgent
China had around 310 million people over the age of 60 in 2024, about 22% of its population. By 2050, that number is projected to exceed 500 million. A shrinking workforce must support a growing population of retirees, increasing pressure on pension payments and healthcare spending.
Years of lax enforcement have allowed informal agreements between companies and workers to bypass social insurance payments. A 2024 survey by IndexBox found that only 28.4% of more than 6,000 firms fully complied with social insurance rules. Official data puts the number of employees contributing to the urban pension scheme at 387 million, about half the workforce.
The system's coverage of more than one billion people includes different forms of protection, while the 387 million figure concerns employees paying into the urban pension scheme. For financing, the number of people making contributions matters alongside the number receiving or entitled to benefits.
The Supreme People's Court's ruling aims to close gaps in enforcement, replenish depleted pension coffers and support a stronger welfare system as China moves toward an economy driven more by consumption. Better protection can reduce the financial uncertainty households face, although contributions also reduce the cash workers have available immediately.
Businesses are confronting the deadline while many are still recovering from the economic shocks of the COVID-19 pandemic and ongoing trade tensions. Some factories affected by higher U.S. tariffs have already dismissed full-time employees and rehired them as day laborers to avoid insurance payments. That response shows how changes in employment arrangements can complicate efforts to collect contributions.
Small firms face a difficult cost calculation
Societe Generale estimates that full compliance with social insurance obligations could cost firms and consumers about 1% of GDP. GDP measures the value of goods and services produced by an economy, so the estimate describes a potentially substantial cost across businesses and households.
Small companies operating with narrow profit margins may struggle to absorb the additional expense. A restaurant owner interviewed by IndexBox said the new costs would consume most of his annual profit before tax, leaving the business in a fragile financial position.
An analyst quoted by Reuters described the pressure facing small companies as a threat to their survival:
This could be a matter of life or death for many small firms.
Employers worried about higher labor costs may reduce wages, dismiss workers or close their businesses. Others may hire people without recording the employment formally. Moving jobs into the informal sector would make it harder to expand the pool of contributors and improve protection for vulnerable workers.
Low income employees face a trade-off of their own. Mandatory contributions mean less take-home pay now, but offer security during illness, unemployment and retirement. Minimum contribution rules make that exchange particularly demanding for workers whose wages fall below the salary amount used to calculate payments.
September's enforcement change has no specified outcome for how many businesses will close or how many jobs will be lost. Those concerns are possible responses to higher costs, while the immediate requirement is that employers and employees cannot use an informal waiver to avoid mandatory insurance.
Household registration shapes access to benefits
China's hukou system, established in 1958, ties household registration to a particular place. It was designed to control labor mobility and guarantee basic welfare for urban residents. Because benefits are connected to registration, rural migrants working in cities often lack access to the same social insurance programs as urban residents.
A worker can therefore move to a city for employment without gaining the same welfare access as someone registered there. The gap between urban and rural pensions is one visible part of a wider divide involving registration, employment status and the insurance programs available to different groups.
Chongqing and other cities have eased hukou restrictions, allowing millions of rural migrants to obtain urban registration and access better social protection. Studies show that these reforms can strengthen rural households' ability to withstand financial difficulties, increase incomes and improve access to formal financial services.
Migrant workers and employees in informal jobs still face uneven coverage. Complex rules create barriers to universal participation, so stronger contribution enforcement sits alongside a separate task: making benefits easier to access for people who live and work away from their registered home.
Medical insurance integration offers evidence of gains
Research published in Frontiers found that integrating Urban-Rural Resident Medical Insurance (URRMI) improved employment quality for rural migrants working in cities. The medical insurance integration study identified gains in wages, social protection coverage and job stability.
URRMI brings urban and rural resident medical insurance arrangements together. For workers moving between rural areas and cities, integration addresses differences in protection that can accompany their place of registration or residence.
The strongest effects appeared among older workers and in regions where primary industries accounted for a high share of employment. Primary industries include activities such as agriculture that obtain products directly from natural resources.
The findings suggest that further integration could help narrow gaps in social insurance coverage between urban and rural populations. They also show why collecting more contributions is only one part of reform: the organization of benefits can affect workers' employment security and the protection they receive.
Health reforms can bring gains and extra expenses
A study published in BMC Public Health found that participation in rural pension and medical insurance programs was modestly associated with better health outcomes for certain age and income groups. The rural insurance health study found limited effects across the population studied, with benefits varying between groups.
Another study examining Diagnosis Related Groups (DRGs) payment reform found that drug expenses for elderly patients fell while their out-of-pocket costs increased. DRGs are a way of organizing hospital payments around categories of treatment, rather than paying separately for every item of care.
Elderly patients in that study faced a shift in the financial burden from public insurance to individuals. Out-of-pocket costs are the expenses patients pay themselves. Lower spending on medicines within the payment system can therefore coincide with a larger personal bill, depending on how coverage and hospital payments are arranged.
Research from the National Bureau of Economic Research provides an international comparison. Social security reforms in other countries have generally increased labor force participation among older workers by reducing the implicit tax on working at older ages. That term describes how pension rules can make continued employment financially less rewarding.
The effectiveness of those reforms depends on benefit levels, the structure of the system and the economic setting. Together, the research points to a practical concern for China: participation, payment rules and the value of benefits all affect what workers and retirees receive from reform.
Fairness and trust influence participation
A recent study found that perceptions of fairness in both opportunities and outcomes increased individuals' sense of social security. Political trust played a mediating role, meaning that confidence in institutions helped connect perceptions of fairness with a stronger feeling of protection.
Urban residents were particularly sensitive to perceived inequities in the distribution of resources. Rural residents were more influenced by tangible disparities and community cohesion, or the strength of relationships and mutual support within their communities.
The study's policy recommendations included regular fairness audits, stronger channels for public feedback and action to close resource gaps, especially in rural areas. Fairness audits would examine whether rules and resources serve different groups equitably, while feedback mechanisms would give people a way to raise problems with the system.
Public confidence matters when workers are asked to accept lower take-home pay in exchange for future protection. Trust is already fragile among some young people who fear they will contribute for years and receive little in return. Improving transparency and addressing unequal access are therefore connected to the practical task of sustaining participation.
Retirement changes confront a growing elderly population
China's pension system has expanded to cover more than one billion people, but it faces financial and demographic challenges. Its statutory retirement age is among the lowest in the world. Beginning in January 2025, retirement ages are gradually rising toward 63 for men and 55 to 58 for women.
The Chinese Academy of Social Sciences projects that the basic pension system for employees could run out of funds by 2035 if current trends continue. That conditional projection adds urgency to efforts to collect contributions and adjust retirement rules.
The main dates connecting contribution enforcement and demographic pressure are:
- January 2025: Gradual increases in statutory retirement ages begin.
- August 29, 2025: Workers and employers approach the September enforcement deadline.
- September 1, 2025: The prohibition on informal social insurance opt-outs takes effect.
- 2035: The Chinese Academy of Social Sciences projects possible depletion of the basic employee pension system's funds if current trends continue.
- 2050: China's population over 60 is projected to exceed 500 million.
Reform tasks identified by experts include supporting financial sustainability through retirement age changes, improving financing and fund management, expanding coverage for flexible workers and migrants, removing hukou restrictions and developing private pension schemes.
The system remains fragmented and lacks national coordination. Policymakers must balance economic growth, the money entering and leaving insurance funds, and the level of protection provided. Increasing contribution rates raises costs for workers and employers, while reducing benefits leaves recipients with less support.
Chinese families have traditionally played a major role in caring for older relatives, often substituting for government support in old age. Smaller families and an aging population increase pressure on formal social security programs. Future reforms must account for how public benefits and support from relatives work together.
Healthcare coordination is part of the same reform effort
China's insurance changes sit within a broader effort to coordinate medical care, medical insurance and pharmaceuticals. Known as the three-medicals linkage, this strategy has been a government priority since 2014, with the aims of improving efficiency, reducing costs and expanding coverage.
The approach connects decisions that otherwise may be made separately: how hospitals provide treatment, how insurance pays for it and how medicines are supplied. Successful local approaches, including the Sanming model, have demonstrated the potential for cost savings and better balance between insurance fund income and spending.
Limited coordination across sectors remains a problem. Persistent urban and rural disparities, gaps in health information systems and the need to develop the healthcare workforce also affect how well the approach works.
Comparative studies of healthcare reforms in developing countries, including China, Mexico and Vietnam, show that social health insurance can improve financial protection for poorer people. Results depend on policy design, local conditions and rigorous evaluation.
Those studies also identify the importance of improving the supply of healthcare. Better quality services and greater availability of treatment are as important as expanding insurance coverage. A person needs both help paying a medical bill and access to suitable care.
Who bears the cost of stronger protection?
China's immediate challenge is to broaden the contributor base without placing an unbearable burden on workers and small firms. Stronger funding supports the welfare system and the transition toward an economy driven by consumption, while higher deductions and employment costs can squeeze household spending and business budgets.
Experts suggest several ways to soften the transition: greater government subsidies for low income workers and small businesses, broader unemployment benefits and social assistance, and better fund management and transparency. Other proposals include national coordination of fragmented systems, continued hukou reform to improve migrant access, and private pension schemes with voluntary participation.
Government subsidies would shift part of the immediate cost away from households and employers. Expanded unemployment benefits and assistance would support people who lose income, while clearer fund management could help contributors understand how their payments are used.
A policy adviser described the central decision behind those proposals:
The core challenge of welfare reform is deciding who pays for it.
The September 1 prohibition strengthens the requirement to contribute. Its longer term success will depend on how much of the financial burden the government shoulders, how effectively the rules are implemented and how policy responds to changing economic and demographic conditions. Workers need reliable benefits, and businesses need a workable way to finance them.
Key Points
- China will prohibit informal agreements waiving mandatory social insurance contributions from September 1, 2025.
- Typical contribution estimates are about 10% of gross income for workers and 25% for employers, with employee deductions also described as nearly 12% of salary.
- Minimum contribution rules can place a heavier proportional burden on workers earning the least.
- A 2024 survey found only 28.4% of more than 6,000 firms fully complied with social insurance rules.
- Average monthly pensions at the end of 2023 were 3,700 yuan for retired urban employees and 223 yuan for rural residents.
- China had around 310 million people over 60 in 2024, with more than 500 million projected by 2050.
- Small firms face higher costs, while workers face lower immediate pay in exchange for insurance protection.
- Hukou reform, insurance integration, government support and better fund management are among the measures proposed to improve access and financial sustainability.