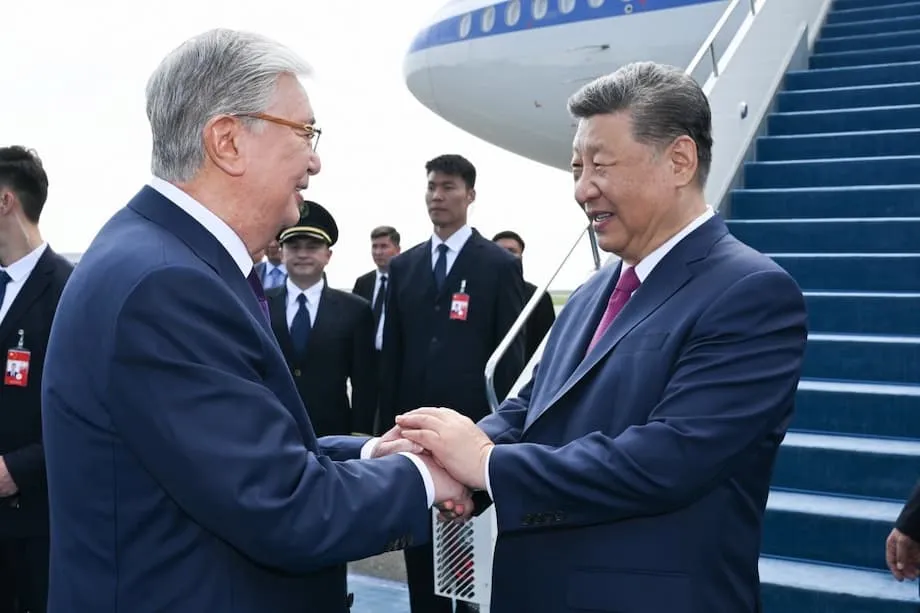
Kazakhstan leads a record investment surge
China's Belt and Road Initiative recorded $124 billion in investments and construction contracts worldwide in the first half of 2025, with Central Asia emerging as a major destination. Kazakhstan attracted $23 billion during those six months, including a $12 billion aluminum complex led by East Hope Group and $7.5 billion in copper projects.
Contents
- Kazakhstan leads a record investment surge
- Why Central Asia matters to Beijing
- Aluminum and copper anchor the resource strategy
- The BRI moves beyond transport
- Private companies and new financial connections
- The Astana summit strengthens political ties
- Railways, energy and agriculture bring local opportunities
- Debt and resource ownership remain sensitive
- Russia retains influence as Western partners seek a role
- Global supply chains meet local concerns
- Key Points
The figures show how the initiative is changing. Roads, railways and power plants remain part of China's overseas engagement, but securing industrial resources has become a larger priority. Across countries participating in the Belt and Road Initiative (BRI), metals and mining investment reached $24.9 billion in the first half of 2025, exceeding every previous full year since the initiative began.
Kazakhstan's aluminum and copper projects together account for $19.5 billion, about 85% of its $23 billion total. That concentration makes the country a focal point of China's efforts to secure materials for electric vehicles, renewable energy equipment and advanced manufacturing.
Central Asia's governments see opportunities to attract capital, modernize industries and expand trade. They also face concerns about debt, environmental damage and dependence on a powerful neighbor. China's growing economic presence is changing their relationships with Russia and Western partners, while giving the region a larger role in global resource markets.
As of August 28, 2025, the surge combines investments and construction contracts, bringing together industrial projects, infrastructure and diplomatic commitments. Its effects will depend on how those projects develop, how benefits reach local communities and how governments manage their financial and political relationships.
Why Central Asia matters to Beijing
Kazakhstan, Kyrgyzstan, Tajikistan, Turkmenistan and Uzbekistan occupy a crossroads between Europe and Asia. Their mineral resources, energy supplies and agricultural potential make them attractive partners for China, while their location creates opportunities for transport routes connecting markets across the continent.
China launched the BRI in 2013 in Astana, Kazakhstan's capital. The initiative initially concentrated on connections such as roads, railways and power plants. Its expansion into resource extraction, renewable energy and technology reflects the changing needs of China's economy and the countries receiving investment.
Chinese manufacturers need reliable supplies of industrial metals for manufacturing and green energy industries. Investments in neighboring countries offer a way to secure those supplies amid concerns about global market volatility, vulnerable supply chains and potential trade restrictions from the United States.
Central Asian countries have sought to diversify their partnerships since the collapse of the Soviet Union. Russia has remained influential through historical connections and security relationships, but governments in the region have welcomed other economic partners to reduce their reliance on Moscow.
Russia's continuing war in Ukraine has added urgency to that search. The war has strained Moscow's capacity to engage in Central Asia, creating room for China to expand its economic role. Geography, resources and changing diplomatic relationships therefore help explain why the region has become a priority.
Aluminum and copper anchor the resource strategy
Kazakhstan's $12 billion aluminum complex and $7.5 billion in copper projects place industrial metals at the center of the investment surge. Aluminum and copper are important materials for electric vehicles, renewable energy infrastructure and advanced manufacturing, all industries central to China's economic strategy.
China's $24.9 billion in metals and mining investment across BRI countries during the first half of 2025 shows that the shift extends beyond Kazakhstan. A six month total surpassing every earlier full year points to a much stronger emphasis on resources within the initiative.
Supply chains are the connected steps through which raw materials become finished products and reach customers. A disruption at the mining or processing stage can affect manufacturers farther along that chain. Investing directly in countries with substantial resources gives China a stronger position in arranging supplies.
The strategy also responds to concerns about potential restrictions on trade. The United States and its allies have been considering tighter export controls on critical minerals, while China seeks to reduce exposure to supply disruptions and strengthen its negotiating position in international trade.
Aluminum, copper and tungsten connect the Central Asian investment story to wider competition over materials. As demand grows, access to resources in the region could give China greater influence over mineral supplies and pricing, while supporting its own manufacturing and green energy goals.
The BRI moves beyond transport
The Green Finance & Development Center and Griffith Asia Institute describe a substantial change in the sectors receiving BRI engagement. Transport's share has fallen to its lowest level, at 7.2%, while energy, metals and mining, and technology have grown.
Energy accounted for 35% of BRI engagement in 2025, metals and mining for 20%, and technology for 13.3%. Technology and manufacturing investments more than doubled, reaching $23.2 billion in the first half of the year. Together, these figures show an initiative increasingly concerned with what countries produce, alongside how they move goods.
Chinese enterprises initially concentrated on major infrastructure projects such as airports, seaports, highways and power plants. Many were built by enterprises owned by the Chinese state, with the aim of improving trade connections and stimulating economic growth in partner countries.
Solar power, batteries for electric vehicles and hydrogen are now part of a more varied investment agenda. These activities connect energy production and industrial manufacturing with the raw materials needed to support them. Central Asia's resources and development needs fit several parts of that agenda.
Chinese overseas engagement has grown while foreign direct investment from other countries into emerging markets has declined. Foreign direct investment means putting money into business operations in another country. For governments seeking factories, energy projects or industrial development, the changing availability of investment affects which partners can help finance those plans.
Private companies and new financial connections
Private Chinese companies are playing a growing role in BRI investment, particularly in mining and technology. East Hope Group's leadership of the aluminum complex in Kazakhstan illustrates the scale of corporate participation in the region's industrial projects.
Jiaxin International Resources, a tungsten miner, provided another example in 2025 through its dual listing on the Hong Kong and Astana stock exchanges. A dual listing allows a company's shares to be traded on two exchanges, creating additional routes for raising capital and attracting investors.
The listing highlighted new financial mechanisms linking China and Central Asia, alongside the growing international use of the Chinese yuan. Financial relationships are developing alongside mines, factories and transport infrastructure, giving companies more ways to support their expansion.
Central Asian economies can benefit from those additional channels for investment. They also deepen the financial connections accompanying China's industrial presence, making the relationship broader than a series of construction contracts or government loans.
The Astana summit strengthens political ties
President Xi Jinping and the leaders of all five Central Asian republics signed the Treaty on Eternal Good-Neighbourliness, Friendship and Cooperation at the China–Central Asia Summit in Astana in June 2025. The agreement sought to deepen economic, political and infrastructure cooperation and strengthen mutual trust.
The summit also accelerated projects including the China-Kyrgyzstan-Uzbekistan Railway. Diplomatic commitments and transport development are moving together, bringing the region into closer economic contact with China while supporting Central Asian governments' efforts to expand their partnerships.
The main stages of that development span more than a decade:
- 2013: China launched the Belt and Road Initiative in Astana, initially concentrating on infrastructure and trade connections.
- First half of 2025: Global BRI investments and construction contracts reached $124 billion, with Kazakhstan attracting $23 billion.
- June 2025: China and the five Central Asian republics signed the friendship and cooperation treaty in Astana and accelerated regional projects.
- 2025: Jiaxin International Resources listed on the Hong Kong and Astana stock exchanges, adding another financial connection between China and Central Asia.
China's approach combines economic activity with diplomacy. Investment provides practical reasons for closer cooperation, while the treaty gives that cooperation a broader political framework. Central Asian governments, meanwhile, are seeking to use those relationships to attract development without surrendering their freedom to work with other partners.
Railways, energy and agriculture bring local opportunities
The China-Kyrgyzstan-Uzbekistan Railway is expected to support trade with Europe while bypassing Russia. For Central Asian states, an additional route means more choices about how goods reach foreign markets and less reliance on a single transit partner.
Railways and logistics hubs can also reduce trade costs and improve regional connections. When transport development accompanies mining and energy projects, it creates economic corridors linking resource production with processing, manufacturing and export markets across China, Central Asia and Europe.
Kazakhstan and Uzbekistan are receiving Chinese investment in solar and wind power plants, biomass facilities, and factories producing wind turbines and solar panels. Biomass facilities use material such as plant matter to produce energy. These projects extend the investment surge beyond extraction into electricity production and manufacturing.
Agricultural investment includes deep grain processing and irrigation. Processing grain into products with more value can expand the activity surrounding farming, while irrigation supports agricultural production. Such investment is intended to improve productivity and food security.
Major projects bring opportunities for employment, technology transfer and modernization in mining, energy and agriculture. Technology transfer means that equipment, production methods and knowledge move into the host economy. For local communities, the practical gains depend on how much work, training and business activity those projects create.
Debt and resource ownership remain sensitive
Kyrgyzstan and Tajikistan are already heavily indebted to China, and their external debt levels exceed 25% of gross domestic product. External debt is money owed to creditors abroad; gross domestic product (GDP) measures the value of goods and services produced in an economy. Comparing the two helps show the size of repayment obligations relative to economic activity.
Critics describe a risk of debt trap diplomacy, in which countries unable to repay loans could lose control over strategic assets. The concern centers on whether governments can meet financial commitments while retaining authority over infrastructure and resources important to their economies.
Large mining projects also raise concerns about environmental damage and resource sovereignty. Resource sovereignty means a country's ability to decide how its natural resources are used. Expanding foreign investment makes the terms governing extraction, financial returns and local control especially important.
Central Asian governments are pursuing what they call multivector foreign policies. In simple terms, they seek working relationships with several major powers at once, including China, Russia and Western partners. That approach is intended to preserve autonomy while attracting investment and other benefits.
The same projects can offer economic opportunities and create financial pressure. Governments must balance the jobs, infrastructure and technology they seek against repayment demands, environmental costs and the possibility of becoming increasingly dependent on one partner.
Russia retains influence as Western partners seek a role
Russia's war in Ukraine has weakened its capacity for regional engagement, giving China room to become Central Asia's dominant economic partner. Moscow still retains substantial influence through security alliances, historical ties and cultural connections, even as Chinese capital expands across the region.
China has avoided direct confrontation with Russia, presenting its regional activity through economic cooperation and mutual benefit. Its investments nevertheless increase its influence by connecting Central Asian industries, infrastructure and financial arrangements more closely with Chinese businesses and markets.
The United States and the European Union have increased diplomatic engagement through efforts including the C5+1 summit and new trade initiatives. Western partners provide alternative investment opportunities and support for governance reforms, although their influence remains limited compared with that of China and Russia.
Chinese engagement is difficult for Western partners to match in scale and speed. Central Asian leaders are using the competition among outside powers to attract investment, seek concessions and maintain independence, rather than relying exclusively on one relationship.
Multivector diplomacy is therefore a practical response to the region's changing balance of power. New transport routes can broaden trading options, while relationships with several investors and governments can give Central Asian states more room to pursue their own priorities.
Global supply chains meet local concerns
China's investments in aluminum, copper and tungsten place Central Asia closer to the center of supply chains serving electric vehicles, renewable energy and advanced manufacturing. Access to those materials supports China's domestic economic goals and could reshape competition with Western and Russian interests in global resource markets.
Mining, energy and transport projects can reinforce one another. A mine needs power and ways to move its output; factories need reliable materials and connections to customers. Building those activities together can create new corridors of trade and production across the Eurasian continent.
Central Asian publics have also expressed skepticism about China's intentions. Concerns include sovereignty, environmental degradation and cultural erosion. Protests against Chinese projects in countries including Kyrgyzstan reflect demands for transparency and benefits that reach local communities.
Environmental and social standards are becoming more important as China and host governments seek projects that are sustainable and useful to local people. The Green Finance & Development Center recommends concentrating on financially sustainable projects, supporting partner countries facing debt problems and increasing international cooperation.
The longer trajectory remains dependent on global economic conditions, the war in Ukraine and changing relationships among China, Russia and the West. Central Asia's resources and location make it a continuing arena for competition and cooperation, but public acceptance and the management of projects will shape what its countries gain from the investment surge.
Key Points
- BRI investments and construction contracts reached a record $124 billion worldwide in the first half of 2025.
- Kazakhstan attracted $23 billion, including a $12 billion aluminum complex led by East Hope Group and $7.5 billion in copper projects.
- Metals and mining investment across BRI countries reached $24.9 billion, exceeding every previous full year.
- Energy, mining and technology gained prominence as transport's share of BRI engagement fell to 7.2%.
- China and the five Central Asian republics signed a friendship and cooperation treaty in Astana in June 2025.
- The China-Kyrgyzstan-Uzbekistan Railway is expected to support trade with Europe while bypassing Russia.
- Central Asian governments seek jobs, technology and new trade routes while managing debt, environmental concerns and dependence on China.
- Russia retains security and cultural influence, while Western engagement gives the region additional diplomatic and investment options.