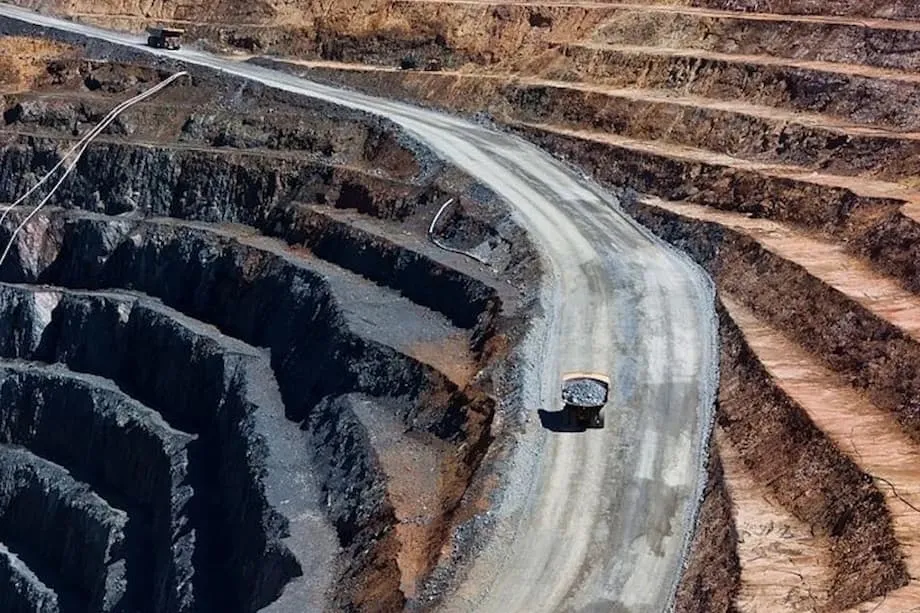
A Mine Closure Shows the Stakes of China's New Rules
CATL's Jianxiawo lithium mine suspended operations on August 9, 2025, after its permit expired during a regional audit in Yichun, Jiangxi. The shutdown at a major source of supply for the battery giant helped send lithium carbonate futures on the Guangzhou Futures Exchange up 8% in a single day, reaching their upper price limit.
Contents
- A Mine Closure Shows the Stakes of China's New Rules
- How the Lithium Boom Exposed Gaps in Oversight
- What Changed Under the Mineral Resources Law?
- Falling Prices Put Pressure on Producers
- Why Yichun Became the Focus of Enforcement
- How the Shutdown Moved Global Markets
- Technology Restrictions Extend Control Beyond Mining
- What Green Mine Requirements Mean Locally
- What Changes for Battery and Vehicle Manufacturers?
- The Bottom Line
The closure brought the consequences of China's mining overhaul into sharp focus. Changes to the Mineral Resources Law took effect in July 2025, tightening control over how lithium deposits are classified, how mining rights are approved and how operators meet environmental and safety requirements.
China, the world's largest producer and processor of lithium, is trying to address several problems at once: illegal extraction, excess production capacity, destructive price competition and environmental damage. Its decisions also affect the supply of materials used in electric vehicles, renewable energy storage and advanced manufacturing around the world.
As of August 25, the central issue is how far enforcement will reduce supply while companies update permits and meet the new requirements. A shutdown can lift prices quickly, but the government's wider objective is to put a rapidly expanded industry under tighter strategic control.
How the Lithium Boom Exposed Gaps in Oversight
China's lithium industry expanded rapidly from the late 2010s, supported by the country's push into electric vehicles and storage for renewable energy. By 2022, China accounted for about 36% of global lithium supply and dominated the processing and refining of lithium chemicals needed for batteries.
Mining provides the raw material, while processing turns it into chemicals that battery manufacturers can use. China's strength across both stages gives its mining decisions a reach far beyond the communities where the ore is extracted.
Yichun, known as China's lithium capital, became a prominent example of the costs of rapid growth. Environmental degradation, excess capacity and unlicensed or noncompliant operations accompanied the expansion. In early 2023, authorities uncovered widespread unauthorized lithium extraction there, linked to environmental damage and transport accidents.
Central regulators intervened, shutting illegal mines and exposing weaknesses in local oversight. Provincial and prefectural governments had previously held substantial authority to approve mining rights. That arrangement allowed inconsistent enforcement and loopholes, creating room for extraction to expand faster than regulatory supervision.
Beijing's response has moved the industry toward a more unified approach to critical minerals. The shift changes who makes key decisions and requires operators to account more precisely for the minerals they extract.
What Changed Under the Mineral Resources Law?
The revised Mineral Resources Law, effective in July 2025, designates lithium as an independent, strategic mineral for the first time. That classification places lithium more directly within national decisions about the security of essential industrial supplies.
Approval authority for mining rights involving strategic minerals is centralized under the Ministry of Natural Resources. Mines previously registered under other mineral categories must be reclassified, closing a gap between the mineral named on a permit and the mineral actually being extracted.
The new framework sets a minimum lithium oxide content of 0.4% for deposits to qualify as lithium orebodies. Lithium oxide, written as Li2O, is a measure used to describe the lithium content of ore. The threshold therefore helps determine whether a deposit qualifies for the lithium mining category.
Operators also face stronger environmental and safety requirements, including compliance with green mine criteria. Together, the changes aim to reduce local favoritism, close regulatory gaps and leave mining to qualified operators that meet the rules.
For a company, this means that having a mine and customers is only part of the task. Its mineral classification, mining rights, resource documentation and operating standards must also satisfy the revised framework.
Falling Prices Put Pressure on Producers
Lithium prices reached record highs in late 2022 before reversing sharply. By the end of 2023, they had fallen by nearly 90% as new supply grew faster than demand. A fall of that size left prices at roughly one tenth of their earlier level.
Smaller mines and operations with higher costs were especially exposed. When the price received for lithium falls below the cost of producing it, continued operation loses money. In Jiangxi, about 30% of capacity using lithium mica sat idle during the first half of 2025 because profit margins were negative.
Authorities viewed this race to the bottom as a threat to the industry's longer term health. Their supply reforms included encouraging consolidation, cutting excess capacity, banning sales below cost, adding lithium to a price stabilization list and coordinating local shutdowns to ease oversupply.
By mid 2025, the state planner and several ministries were using the term anti-involution for lithium and batteries. In this setting, it means trying to end repetitive, destructive competition in which companies keep expanding or cutting prices without building a healthier industry.
The Lithium Branch of the China Nonferrous Metals Industry Association urged the entire supply chain to resist "vicious competition" and focus on healthy development. The policy direction was shifting from unchecked expansion toward growth shaped more closely by production quality, financial viability and regulatory compliance.
Why Yichun Became the Focus of Enforcement
Yichun's rich lepidolite deposits and integrated battery industry made it a central location for the regulatory push. Lepidolite is a lithium bearing mica, connecting the area's mineral resources directly to its battery manufacturing activity.
In mid 2025, the Yichun Natural Resources Bureau flagged eight mines for licensing inconsistencies. Operators were required to update reserve reports and undergo compliance audits. Reserve reports document the mineral resources a mine expects to extract, making them part of the basis for licensing decisions.
The problems included mismatches between licensed mining rights and the minerals being extracted, mining boundary violations, inadequate documentation and discrepancies in production reporting. Each issue concerned whether actual operations matched the permissions and records held by regulators.
Companies were required to rectify permits and submit renewal applications, a process expected to take several months. For operators, that creates a period in which administrative work can affect the timing and continuity of production.
CATL's Jianxiawo suspension on August 9 showed how a permit problem at a major mine could quickly become a market event. Its permit expired amid the regional audit, interrupting an important source of supply for the battery company.
How the Shutdown Moved Global Markets
Lithium carbonate futures on the Guangzhou Futures Exchange rose 8% in a single day after the CATL suspension, hitting the exchange's upper price limit. The lithium futures surge reflected expectations that tighter supply could lift prices.
Futures are contracts tied to delivery or settlement at a later date. Their prices respond to expectations about future availability, which helps explain why a mining interruption can move the market before its full effect on physical supply becomes clear.
Shares of global lithium producers also rallied as investors anticipated tighter supply. Producers outside the affected area could benefit from higher prices, while battery manufacturers and other buyers faced greater uncertainty over material costs.
Analysts warned that up to 17% of global lithium supply could be at risk if further closures occurred. That estimate depended on additional shutdowns. Large scale closures were considered unlikely in the short term because of strategic considerations, including lithium's importance to the battery supply chain.
The important dates show how the policy and market developments unfolded:
- Early 2023: Authorities uncovered widespread unauthorized lithium extraction in Yichun, and central regulators shut illegal mines.
- First half of 2025: About 30% of Jiangxi's lithium mica capacity was idle because of negative margins.
- Mid 2025: Yichun's Natural Resources Bureau flagged eight mines for licensing inconsistencies.
- July 2025: The revised Mineral Resources Law took effect, and new restrictions on exports of battery related technologies were issued.
- August 9, 2025: CATL's Jianxiawo mine suspended operations after its permit expired during a regional audit.
Technology Restrictions Extend Control Beyond Mining
China's strategy also reaches into the knowledge needed to process minerals and manufacture battery materials. In July 2025, the Ministry of Commerce and Ministry of Technology issued new export restrictions covering key technologies.
The restrictions include lithium carbonate and lithium hydroxide processing, cathode material preparation and gallium extraction. Lithium carbonate and hydroxide are chemicals used in the battery supply chain. Cathode materials form a central part of a battery's internal system for storing and releasing energy.
Exports of restricted technologies require prior approval. Companies involved in joint ventures or technical service agreements consequently face additional compliance costs and longer timelines when transferring covered expertise.
Mining approvals govern access to deposits, while technology restrictions govern the transfer of particular production methods. Together, they give China greater control over the upstream and middle stages of the battery supply chain, from raw materials to their preparation for manufacturing.
The approach also raises entry barriers and filters out speculative or obsolete capacity. China aims to reduce domestic oversupply, stabilize prices and retain operators with advanced technology and acceptable environmental practices. It mirrors earlier reforms in steel and coal, where government intervention addressed excess capacity and financial risk.
What Green Mine Requirements Mean Locally
Environmental protection is a central part of the revised mining framework. Green mine criteria require companies to conduct environmental impact assessments, restore damaged areas, establish restoration funds and prepare closure plans.
An environmental impact assessment examines the likely effects of a project. Restoration funding and closure planning address what happens to the site after extraction ends, making the condition of the land part of the operator's responsibilities.
Companies must also adopt advanced technologies to reduce ecological damage. Environmental harm can bring administrative, civil and criminal liability, and operations that fail to comply risk suspension or closure.
China's sustainability push is intended to bring mining practices closer to international standards and strengthen the global credibility of its supply chain. For mining regions, the same requirements can mean higher operating costs and slower project development.
Smaller mines with higher costs may be forced out, bringing possible job losses and economic disruption in some communities. Local governments that previously had incentives to pursue rapid growth now face pressure to prioritize longer term competitiveness and environmental stewardship.
The balance is practical as well as political: tighter supervision aims to improve environmental outcomes and industry quality, while the cost of meeting those standards can reshape employment and business activity around individual mines.
What Changes for Battery and Vehicle Manufacturers?
Automakers and electronics manufacturers are exposed to China's regulatory decisions because of the country's dominance in lithium processing and rare earths. Restrictions and licensing requirements can affect the availability of inputs, the cost of production and the timing of industrial projects.
Original equipment manufacturers, often shortened to OEMs, are companies that make finished products such as vehicles or electronic devices. Recent export licensing requirements have prompted manufacturers worldwide to diversify supply chains, invest in alternative technologies and seek critical mineral sources outside China.
Building those alternatives is costly and takes time. China's processing capabilities remain unmatched in the near term, so finding a new mineral deposit alone does not replace the facilities and expertise needed to turn ore into usable battery chemicals.
China's reforms are expected to accelerate consolidation as smaller, noncompliant or expensive operations leave the market. Larger companies with stronger technology and the resources to meet environmental requirements are better placed to remain.
Authorities aim for a more stable and transparent market with fewer cycles of rapid expansion followed by collapsing prices. Centralized licensing and technology controls also strengthen China's hold on strategic minerals, while giving overseas manufacturers more reason to diversify.
The wider outcome depends on how China balances intervention with innovation, manages local economic costs and navigates geopolitical tensions. As of August 25, no date had been given for Jianxiawo's restart. Permit corrections and renewals were expected to take several months, leaving the timing of restored output central to the industry's immediate outlook.
The Bottom Line
- China's revised Mineral Resources Law took effect in July 2025, classifying lithium as an independent strategic mineral and centralizing approval of strategic mineral mining rights.
- The framework sets a minimum lithium oxide content of 0.4% for lithium orebodies and requires reclassification of mines registered under other minerals.
- Yichun authorities flagged eight mines for licensing inconsistencies in mid 2025.
- CATL's Jianxiawo mine suspended operations on August 9 after its permit expired; lithium carbonate futures subsequently rose 8% in one day.
- Prices had fallen nearly 90% by the end of 2023 from their late 2022 highs, and about 30% of Jiangxi's lithium mica capacity was idle in the first half of 2025.
- July technology export restrictions require approval for covered processing and production methods.
- Stricter environmental rules and consolidation may improve industry standards while raising costs and disrupting some local jobs.
- Global manufacturers are seeking alternative supply chains, but China's processing capacity remains critical in the near term.