A January Deadline for Millions of Businesses
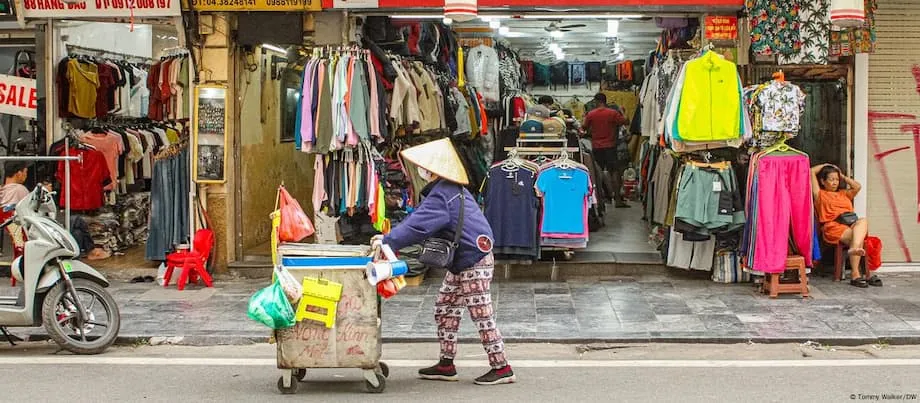
Vietnam plans to end its longstanding lump sum tax system in January 2026, moving registered businesses, regardless of size, to a system based on formal tax declarations. For roughly 2 million household businesses, the change means replacing taxes calculated from estimated sales with bookkeeping, detailed records and regular filings. Only about 6,000 had adopted the declaration system by early 2025.
Contents
- A January Deadline for Millions of Businesses
- Why Vietnam Wants More Revenue
- From Estimated Sales to Recorded Sales
- VAT Relief Comes With New Requirements
- Corporate Tax Rules Tighten Around Incentives
- Consumption Taxes Target Health and the Environment
- Digital Tax Administration and a Promise to Halve Costs
- Small Shops Face Costs and Uncertainty
- The Reform Timetable
- Private Enterprise, Investment and Climate Pressures
- The Essentials
As of August 19, 2025, the transition is approaching while many small businesses are still recovering from the COVID-19 pandemic and facing uncertainty over global trade, including recent US tariffs on Vietnamese goods. Shop owners face the prospect of higher tax bills, spending on cash registers and accounting software, and training themselves and their employees.
The reform reaches beyond small shops. Changes to value-added tax (VAT), corporate income tax, special consumption tax and personal income tax form part of a wider effort to modernize the economy, increase government revenue and support Vietnam's ambition of becoming Asia's next tiger economy by 2045.
Vietnam's leaders want a fairer, more transparent tax system that supports private enterprise and finances infrastructure and social needs. They also promise to make compliance cheaper and faster. The immediate challenge is to introduce more demanding record keeping while helping businesses with limited money, staff and accounting experience manage the transition.
The scale is substantial: about 6,000 businesses using declarations amounts to roughly 0.3% of the approximately 2 million household businesses described in the reform. Moving the rest toward formal reporting will require administrative support on a much larger scale than the existing system.
Why Vietnam Wants More Revenue
Vietnam's economy has changed dramatically since the 1980s. Once among the world's poorest countries, it has become a major manufacturing economy and lifted millions of people out of poverty. Its export driven growth now faces pressure from an aging population, climate risks and global trade headwinds.
The Communist Party's Resolution 68, passed in May 2025, places private enterprise at the center of the response. It describes private businesses as the "most important driving force" of the economy, aiming to give local firms a more prominent position than state owned and foreign corporations.
Resolution 68 promises deregulation, better access to capital, protection for property rights and fair competition. It also calls for a substantial increase in tax revenue to pay for infrastructure, social security and measures to adapt to climate change. Businesses are therefore being asked to operate within a more formal tax system as the government promises them greater support.
Vietnam collected tax revenue equivalent to 16.8% of gross domestic product (GDP) in 2023, below the Asia-Pacific average of 19.5% and the OECD average of 33%. GDP measures the value of goods and services produced in an economy. Comparing tax revenue with GDP shows how much of that economic activity the government collects through taxation.
Vietnam's figure was 2.7 percentage points below the Asia-Pacific average. Its tax share has slipped in recent years, while public debt is capped and spending needs are increasing. Infrastructure spending alone is rising nearly 40% to $36 billion in 2025.
The government sees tax reform as a way to fund those commitments and reduce corruption in tax offices where decisions have often been opaque. Its task is to collect revenue more consistently while preserving the businesses expected to drive future growth.
From Estimated Sales to Recorded Sales
Most household businesses have traditionally paid tax through a simplified lump sum arrangement. Local tax officials estimated revenue, often through informal negotiations, and used that estimate to determine the amount payable. The method was easy to use but vulnerable to underreporting, favoritism and corruption.
From January 2026, registered businesses must instead use declarations supported by detailed accounting, formal bookkeeping and regular tax filings. In simple terms, businesses will need to record their activity and submit the information used to calculate their tax obligations.
The government argues that the change will make competition fairer, ensure businesses pay their share and help build a modern private sector. More consistent records could reduce the scope for different businesses to receive different treatment through negotiations with local officials.
For shop owners, the practical adjustment reaches into daily operations. They must keep detailed sales records, learn invoice procedures and understand how to file returns and pay VAT. Cash registers and accounting software become new expenses, while training takes time away from running the business.
The transition also changes the relationship between businesses and tax authorities. Owners accustomed to an agreed payment will face more detailed reporting and greater visibility of their transactions. Some fear that this scrutiny will bring more audits and penalties in a system where corruption and rent seeking have long been concerns.
VAT Relief Comes With New Requirements
Vietnam's National Assembly has extended a reduction of two percentage points in VAT for most goods and services until the end of 2026. The measure lowers the standard rate from 10% to 8%. First introduced in 2024, it is intended to support businesses, encourage consumption and cushion the economy against global uncertainty.
VAT is a tax on consumption collected through the production and sale of goods and services. Businesses can generally claim credits for eligible VAT paid on their purchases, reducing the amount they must pass to the government.
The extension is estimated to reduce state revenue by more than $1 billion. Authorities expect the lower rate to help stabilize production, protect jobs and improve living standards. It represents immediate tax relief within a broader reform intended to strengthen revenue collection.
New rules also require payments other than cash for all purchases used to claim VAT credits. The aim is to prevent fake invoices and make tax claims easier to verify. Businesses seeking credits will therefore need to consider both their invoices and how they pay suppliers.
For household businesses, the annual revenue threshold for VAT and personal income tax liability has been doubled to VND 200 million, about $8,000, from 2026. Only those earning above that threshold will be taxed. The higher threshold is intended to protect the smallest businesses while bringing larger businesses into more consistent reporting.
E-commerce platforms must also withhold taxes before transferring payments to sellers. Withholding means collecting the tax from a payment before the recipient receives the balance. The policy aims to give online and offline businesses fairer treatment, rather than allowing different sales channels to produce different tax outcomes.
Corporate Tax Rules Tighten Around Incentives
The amended Corporate Income Tax Law takes effect in January 2026 and retains the standard rate of 20%. Corporate income tax applies to company profits, while incentives reduce the tax payable by businesses that meet specified conditions.
The reform makes eligibility for those incentives stricter. Subsidiaries and affiliates of companies already receiving tax incentives will no longer qualify automatically. This is intended to curb the replication of tax breaks across companies within the same corporate group.
The law also strengthens measures against abuse and aligns Vietnam with OECD standards on base erosion and profit shifting (BEPS). The term describes arrangements that reduce a country's taxable profits or move profits to another jurisdiction.
Foreign investors and multinational companies must ensure their Vietnamese operations meet new economic substance requirements and that their transfer pricing arrangements are robust. Economic substance concerns the real business activity behind a company's structure. Transfer pricing concerns the prices charged when related companies trade with each other.
These requirements may lead companies to reconsider their group structures and tax planning. Vietnam expects greater transparency to help create a more competitive investment environment, while businesses will need to establish that their operations and transactions satisfy the revised rules.
Consumption Taxes Target Health and the Environment
Vietnam's updated Special Consumption Tax Law also takes effect from 2026. It expands the goods and services subject to the tax, covering cigarettes, alcohol, beer, certain vehicles, air conditioners and beverages sweetened with sugar.
Special consumption tax is an additional tax applied to selected products or services. In this reform, its purposes include encouraging healthier consumption, supporting environmental protection and improving tax management.
Higher rates are scheduled for products such as tobacco and alcohol. The law also provides exemptions for goods used in export production or disaster relief. Businesses will need to determine which classifications and exemptions apply to their activities.
The reform is intended to make the rules clearer through detailed classifications and advance notice of tax increases. Advance notice gives businesses time to plan for changes in costs, prices and production.
Alcohol and soft drink producers are among the industries that will need to adapt to higher taxes. Possible responses include changing product recipes or shifting toward healthier alternatives. For these businesses, the tax package affects decisions about what they sell as well as how they report and pay tax.
Digital Tax Administration and a Promise to Halve Costs
Vietnam's government aims to cut the time and cost of tax compliance by 50% in 2026 compared with 2024. It also wants all eligible administrative procedures to be available as fully online public services. These targets are intended to make the more formal tax system easier to use.
Digitization is already underway. More than 60% of tax procedures were available online, and nearly 90% of submissions were made electronically in 2024. Expanding online access is meant to reduce paperwork and visits to tax offices.
Personal tax administration is changing too. Tax codes will be replaced by personal identification numbers containing 12 digits. Tax records will be connected with population, social insurance, land use and banking data to help authorities identify risks and fraud.
The government is also moving toward declarations submitted once, reducing repeated requests for the same information. Linking databases is intended to let authorities use information already held elsewhere in the public administration.
Authorities are encouraging business feedback to refine procedures and remove unnecessary burdens. Training and support are being offered, although the scale of the transition means many small businesses will need help at the same time.
The two parts of the reform must work together: businesses are expected to provide better records, while the government promises simpler administration. Owners with little accounting experience or limited resources may still find the transition difficult even when procedures are available online.
Small Shops Face Costs and Uncertainty
Distressed shop owners have appeared in videos that spread widely online. Reports suggest that up to 80% of shops in some markets have closed in recent months. Officials dispute that tax changes alone explain those closures.
Many businesses are dealing with several pressures at once, including recovery from the pandemic and uncertainty surrounding international trade. New reporting requirements add another demand on money and time, particularly for owners who have no staff dedicated to accounting.
Small business owners face four immediate tasks:
- Buy cash registers and accounting software.
- Train themselves and employees in bookkeeping and tax compliance.
- Keep detailed sales records and file regular tax returns.
- Learn the procedures for issuing invoices and paying VAT.
Some owners worry that higher tax bills and administrative expenses could force them out of business. Others fear more frequent audits and penalties as digital records make their activity easier to examine. The concerns are especially acute where businesses have limited resources to correct mistakes or obtain advice.
The government's response combines the higher tax threshold, wider VAT exemptions and administrative support. Authorities hope to ease pressure on the smallest businesses while broadening the tax base among larger and more profitable firms.
Business representatives are calling for flexible application of regulations, consultation over penalties and further reductions in taxpayer burdens. Those requests focus on how the rules are applied during the transition, when unfamiliar procedures can create confusion and frustration.
The Reform Timetable
Vietnam's tax changes span several years, with some relief already in place and the main transition approaching in January 2026. The principal dates are:
- 2024: The VAT reduction from 10% to 8% was introduced. Nearly 90% of tax submissions were electronic, and 2024 became the comparison year for promised compliance savings.
- Early 2025: About 6,000 household businesses had adopted the declaration system.
- May 2025: The Communist Party passed Resolution 68, placing private enterprise at the center of its growth strategy.
- 2025: Infrastructure spending is rising nearly 40% to $36 billion.
- January 2026: The lump sum system ends, the amended Corporate Income Tax Law takes effect, and the updated Special Consumption Tax Law begins applying from 2026.
- 2026: The household business tax threshold rises to VND 200 million, and authorities aim to halve compliance time and costs compared with 2024.
- End of 2026: The extended VAT reduction is scheduled to expire.
The longer development targets extend beyond these tax deadlines. Vietnam aims to nurture at least 20 globally competitive private firms by 2030 and become an Asian tiger economy by 2045.
Private Enterprise, Investment and Climate Pressures
Vietnam's ambitions draw on the development paths of South Korea, Taiwan and Singapore. Reaching its 2045 goal requires investment in infrastructure, technology and human capital alongside tax modernization.
The government is investing heavily in high-speed rail, renewable energy and digital infrastructure. It is also expanding social protections and raising the retirement age as the population ages. These commitments help explain why authorities want a stronger and more dependable revenue base.
Climate change adds pressure to those spending needs. Typhoons and rising sea levels threaten growth and poverty reduction. The World Bank warns that Vietnam could lose up to 14.5% of GDP annually by 2050 without decisive action.
Private businesses are being offered easier loans, priority in government contracts and support for overseas expansion as Vietnam pursues its target of at least 20 globally competitive private firms by 2030. Institutional changes, including merging ministries and consolidating provinces, are intended to build stronger regional economies and reduce bureaucracy.
Vietnam is also aligning its tax system with international standards through the introduction of the global minimum tax, stricter transfer pricing rules and greater transparency. These changes are intended to reassure international investors and prevent the erosion of the tax base.
The government is learning from ASEAN neighbors, adopting incentives for research and development and supporting sectors such as semiconductors, artificial intelligence and green energy. The aim is to connect domestic business growth with investment in more advanced industries.
Effective implementation, transparent decisions and trust between authorities, businesses and citizens will determine whether the tax changes support that strategy. For small shop owners, the immediate measure of success will be more practical: whether they can meet the new requirements without losing the time and income needed to keep trading.
The Essentials
- Vietnam will abolish lump sum taxation in January 2026 and require registered businesses to use formal declarations.
- About 2 million household businesses face the transition; roughly 6,000 had adopted declarations by early 2025.
- The VAT rate for most goods and services remains at 8% until the end of 2026.
- The household business threshold for VAT and personal income tax rises to VND 200 million a year in 2026.
- Corporate income tax stays at 20%, with tighter incentive eligibility and stronger measures against abuse.
- Special consumption tax changes cover selected products, including tobacco, alcohol and beverages sweetened with sugar.
- Authorities aim to halve compliance time and costs in 2026 compared with 2024 and put all eligible procedures online.
- The reforms support Vietnam's goals of stronger private enterprise, higher revenue and development into an Asian tiger economy by 2045.