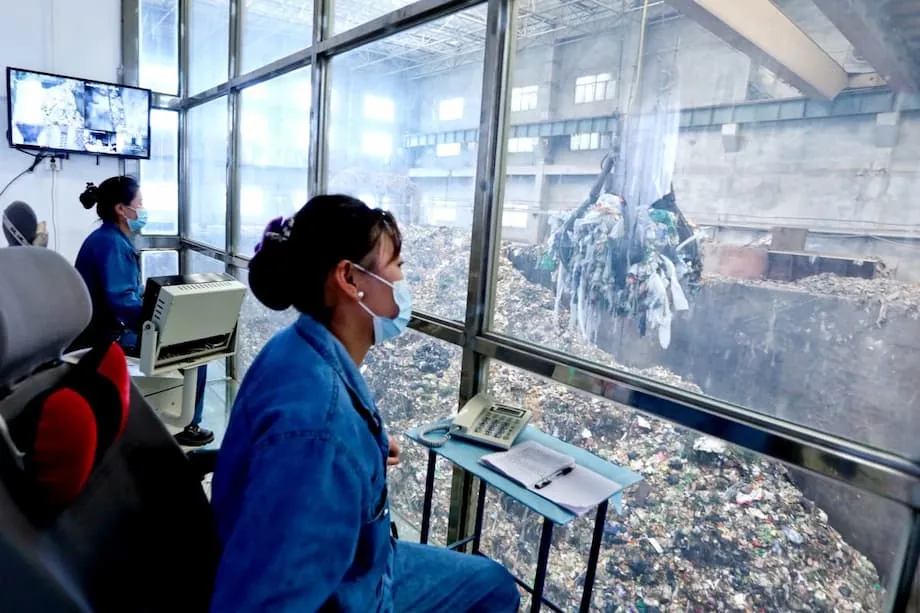
A building boom meets a shortage of rubbish
China had more than 1,010 waste incineration enterprises and capacity to process around 1.11 million tonnes of rubbish a day by 2023, more than any other country. Yet its incinerators were operating, on average, at just 60% of their designed capacity. Some plants were sitting idle for weeks because they could not secure enough waste to keep running.
Contents
- A building boom meets a shortage of rubbish
- How China became the largest incineration market
- Waste volumes failed to match the forecasts
- Sorting success removes fuel from the system
- Government targets pull in different directions
- Idle capacity puts pressure on plant finances
- Pollution concerns continue even with spare capacity
- Other countries face related pressures
- Matching disposal capacity to what cities need
- Key Points
The gap reflects two very different growth rates. According to the Ministry of Ecology and Environment, China collected and transported more than 262 million tonnes of municipal solid waste in 2023, an increase of 11% from 2019. Incineration capacity more than doubled over those same four years.
China built these facilities to solve a pressing problem: growing cities needed somewhere to put their rubbish, while burning it could also generate electricity. Government targets, subsidies and expectations of continued urban expansion encouraged local authorities and companies to build quickly.
Slower urbanization, economic headwinds and successful waste sorting have since weakened those expectations. More recyclable materials and organic matter are being separated from the rubbish that once went to incinerators or landfills. An environmental achievement has become a financial problem for plants built around a larger supply of waste.
As of July 28, 2025, the situation illustrates a less visible part of China's capacity problem. Steel, solar panels and other manufacturing industries have drawn much of the attention, but waste incineration also shows how ambitious investment can outrun demand. Here, the consequences reach beyond industrial profits to municipal budgets, recycling policy, pollution control and the communities living beside disposal facilities.
How China became the largest incineration market
China's expansion of waste to energy facilities accelerated over the past decade. These plants burn rubbish and use the resulting energy to generate electricity. The policy sought to reduce dependence on landfills and fossil fuels while dealing with mounting urban waste.
The Ministry of Housing and Urban-Rural Development, known as MoHURD, set ambitious goals for increasing incineration rates. Local governments and private companies responded by rushing into the industry. Incinerators were presented as a modern, efficient answer to the waste crisis, attracting substantial investment from domestic and international businesses.
Government subsidies helped support the expansion. For investors and local authorities, the combination of policy targets and financial assistance made additional plants attractive. Their plans depended, however, on enough rubbish arriving to sustain operations.
Several developments show how quickly the balance changed:
- In 2018, Shanghai diverted 21% of its waste away from incineration or landfill.
- In 2019, Shanghai launched an ambitious mandatory waste separation programme.
- By 2021, Shanghai's diversion share had reached 54%, while a national policy metric shifted from recycling to resource recovery.
- By 2022, researchers estimated that national incinerator overcapacity exceeded 100%, affecting at least 12 provincial level regions.
- In May 2023, waste to power plants recorded 8,499 planned stoppages nationwide.
- By 2023, China's daily incineration capacity had reached around 1.11 million tonnes, more than double its level four years earlier.
Waste volumes failed to match the forecasts
China's urban expansion had helped drive waste generation for years. As the pace of city growth slowed and the urbanization rate began to plateau, rubbish volumes grew less quickly than the plans behind new incinerators had assumed. Economic headwinds added to the gap between expected and actual demand.
The national figures capture the mismatch: municipal solid waste collection and transport increased by 11% between 2019 and 2023, while incineration capacity more than doubled. Waste was still increasing, but nowhere near as quickly as the country's ability to burn it.
Plants operating at an average of 60% of designed capacity have substantial unused room. That leaves operators with facilities, equipment and running costs planned for a greater volume of material than they receive. In some regions, the shortage has meant weeks without operation because a continuous supply of rubbish could not be secured.
Location has made the problem worse. The rush to build sometimes produced inefficient plant locations and poor sharing of resources between facilities. Capacity available in one area could not automatically solve disposal needs elsewhere, leaving regional differences in how heavily plants were used.
Sorting success removes fuel from the system
Shanghai's waste separation programme, introduced in 2019, required residents to sort rubbish into recyclables, wet waste, hazardous waste and residuals. Wet waste includes the organic material separated through the programme; residuals are the rubbish left after the other categories have been removed.
The programme has since spread to most major cities. Greater recovery of recyclable materials and organic matter has diverted waste away from both incinerators and landfills, reducing the amount available for disposal.
Shanghai's figures show the scale of that change. The share diverted from incineration or landfill rose from 21% in 2018 to 54% in 2021. That was an increase of 33 percentage points, with more than half of the city's waste diverted by the end of the period.
Incinerator operators therefore face a difficult commercial relationship with recycling. Better sorting reduces the amount they can burn, even though recovering materials is one of the goals of waste policy. Facilities built in anticipation of larger waste streams can struggle when households and collection systems successfully remove those materials.
The operational strain was visible in May 2023, when waste to power plants nationwide recorded 8,499 planned stoppages. Some facilities were idle for more than half the month. Those interruptions sit alongside the broader problem of plants unable to obtain enough waste for continuous operation.
Government targets pull in different directions
China divides responsibility for waste management between ministries. The Ministry of Ecology and Environment, or MEE, oversees environmental matters, while MoHURD manages waste collection and disposal. Their targets and measurements have sometimes encouraged conflicting decisions.
A change in 2021 illustrates the problem. The key metric for recyclables shifted from a recycling rate to a resource recovery rate that included both recycling and incineration. Burning rubbish could therefore contribute to a measure that also counted the recovery of materials through recycling.
Local authorities seeking to meet targets and obtain subsidies had an incentive to build more incineration capacity even as recycling increased. Some governments overestimated waste collection figures or built more capacity than needed. Some companies also expanded in anticipation of demand that never arrived.
Data gaps make planning harder. Only Shanghai regularly publishes figures on the quantities of recycled waste, limiting the ability to assess the national balance between material recovery, waste generation and disposal needs. Researchers estimated that national incinerator overcapacity had exceeded 100% by 2022, with at least 12 provincial level regions affected.
The exact national scale remains difficult to assess because of those data limitations. Planning a disposal network requires a reliable picture of what remains after sorting, alongside the amount of rubbish collected. A city can collect more waste while sending a smaller share of it to incinerators.
Idle capacity puts pressure on plant finances
Waste to energy plants in China depend heavily on government subsidies to remain profitable. Many have struggled to receive those payments on time, putting additional pressure on their finances.
Reduced waste volumes, unpaid subsidies and rising operating costs have combined to weaken the industry's profitability. A plant receiving less rubbish has less material available for electricity generation, while the business still faces the costs associated with its facility.
Companies that built for future growth now face the consequences of demand arriving more slowly than expected. Poorly chosen locations and limited sharing of resources can compound the problem, leaving some plants short of waste while available capacity is distributed inefficiently.
Local governments also face competing priorities. They have invested in disposal capacity while pursuing sorting and recycling programmes that reduce the need to burn rubbish. Decisions about new construction, payments to operators and the use of existing plants are tied to the same municipal waste system.
Pollution concerns continue even with spare capacity
Incineration has helped limit the spread of landfills around Chinese cities, but it also brings environmental and health concerns. Modern plants are designed to capture and treat emissions, yet worries remain about toxic substances including dioxins, furans and heavy metals.
Studies have shown increased health risks in communities near incinerators, including higher rates of respiratory illness and cancer. The management of emissions therefore remains a concern alongside the financial problems caused by excess capacity.
Plants also produce fly ash and bottom ash, residues that require careful handling and disposal. China's standards for treating these materials are still evolving. Improper management can allow contamination to reach soil and water.
Electricity generation adds another consideration. The carbon intensity of power from waste incineration is often higher than the national average for electricity generation, particularly when the rubbish contains plastics and other materials derived from fossil fuels. Carbon intensity describes how much carbon pollution is produced for a given amount of electricity.
Residents have resisted incineration projects in several places, including Wuhan, where protests reflected fears about health effects. Some local governments have shelved or delayed construction in response. Negative experiences, limited transparency and inadequate communication have contributed to mistrust, making public acceptance another source of uncertainty for projects.
Other countries face related pressures
Vietnam and Indonesia have also pursued waste to energy plants to address growing rubbish problems. Their experiences include high costs, environmental concerns and difficulties matching proposed facilities to workable waste management systems, alongside concerns about excess capacity.
Vietnam's government has promoted incineration as a way to reduce landfill use and generate electricity. Progress has been slowed by a lack of supportive policies, high investment costs and limited public understanding. Health and environmental risks remain a concern, particularly at older plants with inadequate emissions controls.
Public resistance and legal challenges have further complicated Vietnam's development of new facilities. The difficulties show that constructing a plant is only one part of establishing a disposal system that can operate with public acceptance and adequate pollution controls.
Indonesia has announced plans for incinerators in major cities as it confronts a plastic waste crisis. Critics argue that burning rubbish offers limited help in reducing waste and creates toxic emissions. Indonesia's Supreme Court ordered the government to revoke regulations promoting incineration, stressing waste reduction and recycling instead.
Australia and New Zealand continue to debate the role of waste to energy facilities. Supporters see a way to address waste disposal and energy needs together, while opponents point to environmental risks and the priority of reducing waste and recycling. Several European countries are restricting new incinerator construction to encourage higher recycling rates and lower emissions.
Matching disposal capacity to what cities need
China's experience exposes a central planning problem: a successful recycling programme changes how much disposal capacity a city needs. Building incinerators around expectations of continually rising waste can leave facilities underused when growth slows or more materials are recovered.
The waste hierarchy offers an order for making those decisions. It gives priority to reducing waste, reusing products and recycling materials, with incineration and landfill treated as last resorts. The purpose is to keep useful resources in circulation and reduce the amount requiring final disposal.
More incinerators can provide temporary relief where landfill space is scarce, but continued construction can also deepen excess capacity, financial losses and environmental harm. The policy priorities identified for China include:
- Improving data collection and transparency so capacity reflects actual waste volumes.
- Coordinating government agencies to prevent contradictory incentives.
- Investing in recycling infrastructure and public education to increase resource recovery.
- Maintaining strict environmental standards and monitoring for existing and future incinerators.
- Exploring shared regional facilities and better rural waste collection to balance the use of available capacity.
A circular economy places waste reduction and the reuse of resources at the centre of that approach. For China, the immediate challenge is to align its extensive incinerator network with a waste stream being reshaped by slower urban growth and better sorting, while managing the costs and pollution risks of the facilities already built.
Key Points
- By 2023, China had more than 1,010 incineration enterprises and capacity to process around 1.11 million tonnes of waste daily.
- Incineration capacity more than doubled from 2019 to 2023, while municipal solid waste collection and transport rose 11% to more than 262 million tonnes.
- Plants were operating at an average of 60% of designed capacity, with some idle for weeks.
- Shanghai's share of waste diverted from burning or landfill rose from 21% in 2018 to 54% in 2021.
- Conflicting incentives, limited recycling data, delayed subsidies and inefficient locations have added to the industry's difficulties.
- Emissions, ash disposal, carbon pollution and public opposition remain concerns alongside the financial strain.
- Better data, coordinated planning, recycling investment and shared facilities are among the proposed responses.