AI equipment drives a record quarter
Hon Hai Precision Industry, better known as Foxconn, reported record quarterly net profit of NT$77.524 billion on November 12, 2026, as spending on artificial intelligence equipment pushed its cloud and networking business to 54% of sales. The Taiwan manufacturer raised its outlook for several product divisions and forecast another year of rapid growth in AI rack shipments in 2027.
Contents
- AI equipment drives a record quarter
- Cloud equipment takes a larger share
- Why operating profit rose faster than sales
- Nine months of growth, with a larger funding bill
- Cash collection becomes a fourth quarter priority
- What Foxconn expects through 2027
- Custom chips and faster connections widen the opportunity
- Parts shortages divide the outlook
- Partnerships connect manufacturing with AI demand
- Key Points
Profit for July through September rose 34% from a year earlier and 29% from the previous quarter. Earnings per share reached NT$5.51, compared with NT$4.27 in the second quarter and NT$4.15 a year earlier. Revenue reached a record NT$3.016 trillion, up 46% from a year earlier and 19% from the previous quarter.
Foxconn's profit exceeded the LSEG consensus estimate of NT$69.6 billion by about 11%. Another analyst estimate put the expected figure at NT$70.3 billion, which the company also surpassed.
The results show two changes happening together at the world's largest contract electronics manufacturer. Servers and networking equipment now generate more than half its revenue, while a larger production base and greater automation are helping operating profit grow faster than sales. Financing that expansion, however, is consuming substantial cash.
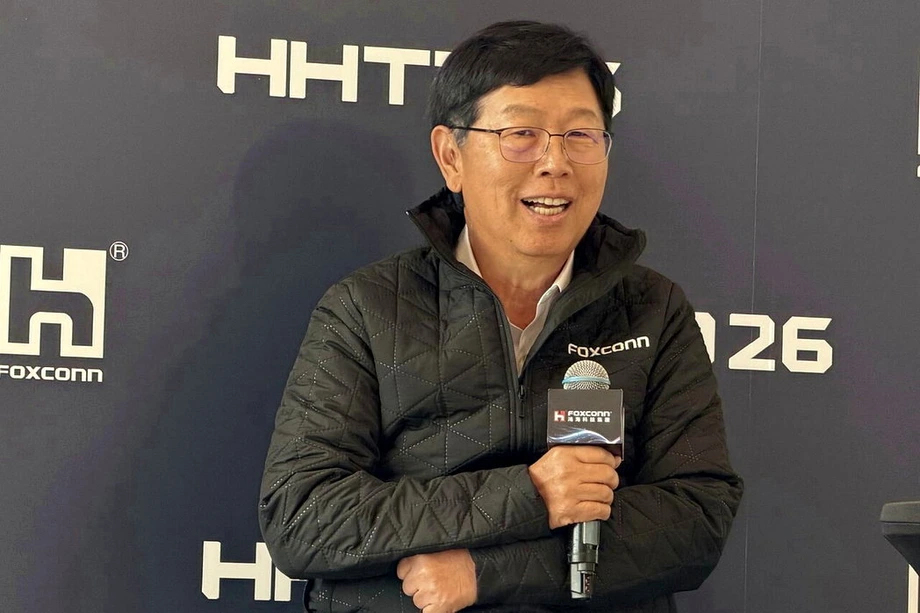
Chairman Young Liu expects strong demand to continue into 2027, supported by investment from major cloud service providers. His caution concerns the ability to obtain chips, memory and other components, alongside the cost and timing of building the facilities that will house the equipment.
Cloud equipment takes a larger share
Cloud and networking products accounted for 54% of third quarter revenue, up from 51% in the second quarter. Smart consumer electronics contributed 29%, computing products 12%, and components and other products 5%.
At those rounded shares, cloud and networking sales were about NT$1.63 trillion, compared with roughly NT$875 billion for consumer electronics. The cloud division was therefore about 1.9 times the size of the consumer division during the quarter.
Liu, Foxconn's chairman, said the shift would continue over the next several years:
Cloud and networking products already account for more than 50% of our revenue this year and we expect that share to exceed 60% over the next three to five years.
Moving from 54% to more than 60% would represent an increase of more than six percentage points. The division includes networking equipment as well as servers, so the changing mix reflects demand for the connections between computers alongside the machines performing AI calculations.
Foxconn said its core AI server and rack business grew more than expected. An AI rack combines servers with power equipment, cooling and fast connections, allowing many processors to work together. Producing a working rack requires the manufacturer to coordinate those parts rather than simply assemble individual computers.
Why operating profit rose faster than sales
Operating profit reached NT$115.35 billion, increasing 64% from a year earlier and passing NT$100 billion for the first time in a quarter. That growth exceeded the 46% rise in revenue.
Chief Financial Officer David Huang attributed the improvement to a larger operating scale, a lower expense ratio and greater automation. When production expands, expenses such as administration and development can be spread across more sales. Automation can also help factories handle more equipment consistently.
Foxconn's operating margin rose to 3.83% from 3.43% a year earlier. In simple terms, the company retained about NT$3.83 in operating profit from each NT$100 of sales after production costs and operating expenses.
Gross margin moved in the opposite direction, falling to 6.02% from 6.35%. Huang cited the product mix and higher raw material prices. Gross margin measures what remains after the direct cost of making products, before expenses such as administration, sales and research.
Despite the lower gross margin, gross profit rose 39% to about NT$181.5 billion because the company sold much more. Net profit margin, which also reflects items beyond core operations, was 2.57%, below 2.80% a year earlier but above 2.37% in the second quarter.
Nine months of growth, with a larger funding bill
Foxconn's revenue for the first nine months reached NT$7.661 trillion, up 39% from NT$5.497 trillion a year earlier. Net profit rose 30% to a record NT$187.417 billion, compared with NT$144.141 billion in the same period of 2025.
Earnings per share increased to NT$13.35 from NT$10.38. Operating profit was about NT$285.8 billion, and the operating margin reached 3.73%, compared with 3.16% a year earlier. The nine month gross margin was 6.10%, while net profit margin was 2.45%.
Those earnings were accompanied by a substantial cash outflow. Operating activities used NT$125.7 billion during the first nine months, compared with NT$49.5 billion a year earlier. Capital spending rose 43% to NT$161.726 billion.
Free cash flow, the cash remaining from operations after capital spending, was negative NT$287.4 billion. The outflow was NT$125.1 billion larger than a year earlier. Foxconn said rapid growth increased inventories and money owed by customers, raising the amount of funding needed to keep the business running.
A manufacturer can record revenue and profit before collecting payment. It may also need to buy expensive components and build production capacity before shipping finished equipment. Foxconn's AI expansion is increasing both demands at once.
Cash collection becomes a fourth quarter priority
Huang said the spending was backed by firm orders from leading customers and demand extending beyond the immediate period. He described the investment as necessary to capture opportunities in AI infrastructure, while saying Foxconn would manage liquidity, working capital and investment returns closely.
Cash and time deposits stood at approximately NT$1.45 trillion at the end of September. Inventory had risen 27% from a year earlier to about NT$1.51 trillion, while receivables, the payments customers still owed, had increased 46%.
Foxconn's balance sheet moved from NT$219.8 billion in net cash at the end of June to NT$21.5 billion in net debt at the end of September. Net debt compares borrowings with cash holdings, giving another view of how the expansion is being financed.
Huang said whether free cash flow would finish 2026 positive depended on fourth quarter shipments, customer collections and the execution of capital spending. The company had not settled that outcome when it presented the results.
For investors, those three measures provide a practical way to follow the expansion: how much equipment leaves factories, how quickly customers pay, and how much more Foxconn spends to increase capacity.
What Foxconn expects through 2027
Foxconn expects strong revenue growth in the fourth quarter compared with both the preceding quarter and the same period of 2025. Spokesman James Wu said third quarter AI rack shipments had met the company's target for a high double digit increase from the previous quarter, and that the fourth quarter should deliver another increase at that pace.
The company also forecast high double digit growth in AI rack shipments for 2027, alongside market share gains. It described the broader outlook as cautiously optimistic, with cloud and networking remaining the main growth engine.
Foxconn raised its outlook for consumer electronics to strong growth and for computing products and components and other products to slight growth. Its broad expectation of strong total revenue growth remained in place, while the revisions improved its assessment of individual divisions.
The main reporting and planning milestones are:
- July through September 2026: Revenue and quarterly net profit reached records, with cloud and networking contributing 54% of sales.
- November 12, 2026: Foxconn released its results and discussed its revised outlook at an investor conference.
- October through December 2026: AI rack shipments are expected to rise at a high double digit rate from the third quarter.
- 2027: Foxconn expects another year of high double digit growth in AI rack shipments.
- Within three to five years: Liu expects cloud and networking to exceed 60% of group revenue.
Custom chips and faster connections widen the opportunity
Foxconn is working with cloud customers on systems using application specific integrated circuits, or ASICs. These chips are designed for particular tasks, while graphics processing units, or GPUs, support a wider range of computing workloads.
Liu said ASIC demand should accelerate as more AI activity moves into inference, the process of using a trained model to answer questions or perform tasks. AI agents, software that carries out sequences of actions, could add to that workload.
Third quarter ASIC server shipments increased about 150% from a year earlier, while GPU server shipments grew about 70%. GPU equipment remained the larger business. The difference in growth rates shows how quickly demand for custom systems is expanding alongside the established GPU market.
Custom chips also create custom manufacturing requirements. Liu identified system architecture, motherboards, power, fast connections and rack integration as areas where customers need different designs. He said Foxconn can make at least half of the components itself, giving it control over more of the production process.
Foxconn is also developing optical connectors, optical components and switches using co-packaged optics, or CPO. This technology places optical connections close to computing or networking chips so that data can move using light. Liu described optical communications as a longer term direction as AI systems exchange increasing amounts of information.
Parts shortages divide the outlook
Liu warned that chips, memory and some key components remained in tight supply across the industry. He expects new capacity to ease constraints gradually, while AI demand continues to exceed supply into 2027.
For Foxconn, the pressure affects product lines differently. Liu expects consumer electronics to remain relatively stable because major customers concentrate on premium models and continue introducing new products with higher specifications.
Personal computers face a tougher balance. Memory shortages and rising component prices could increase retail prices and discourage consumers from replacing their machines. Foxconn expects computing revenue to decline slightly from the third quarter in the final quarter of 2026, despite improving its assessment of the full year.
Electric vehicles provide another possible source of growth. Liu said overseas customer projects would move into production and delivery in 2027, while more models enter commercial use, supporting further growth in related revenue.
Liu also identified inflation, interest rates, currency movements and political uncertainty as factors affecting costs and investment decisions. On American AI policy following the midterm elections, he said the immediate effect on the industry appeared limited, while longer term policy changes required monitoring.
Partnerships connect manufacturing with AI demand
Foxconn's earnings outlook follows its October meeting with OpenAI, when Chief Executive Sam Altman met Liu in Taiwan. Their cooperation covers the physical equipment needed for AI, including racks, power, cooling, networking and cables.
The partnership announced in November 2025 set up a process for OpenAI to share future hardware requirements and for Foxconn to support development. The initial agreement gave OpenAI options to evaluate and purchase resulting systems, with purchasing decisions requiring further commercial arrangements.
Foxconn has also been developing its role as a provider of computing capacity. Its Taiwan supercomputing center plan with Nvidia set out a US$1.4 billion facility rated at 27 megawatts, intended to house a large cluster of advanced GPUs through the Visonbay.ai business.
Alongside factories being built in Mexico and Texas for Nvidia AI servers, these projects show the breadth of Foxconn's expansion: designing systems with customers, manufacturing the equipment and developing facilities that can provide computing services.
The next financial test is concrete. Foxconn needs to translate its growing order book into delivered equipment and collected cash while keeping component supplies and investment spending under control. The record quarter provides the earnings base; fourth quarter execution will determine how much cash follows.
Key Points
- Foxconn reported record third quarter net profit of NT$77.524 billion, up 34% from a year earlier.
- Revenue reached NT$3.016 trillion, with cloud and networking accounting for 54% of sales.
- Operating profit rose 64% to NT$115.35 billion as scale and automation reduced the expense burden.
- First nine month net profit reached NT$187.417 billion, while free cash flow was negative NT$287.4 billion.
- Foxconn expects high double digit growth in AI rack shipments in the fourth quarter and again across 2027.
- Chips, memory, customer payments and capital spending remain central to managing the expansion.