A small factory component carries a large supply risk
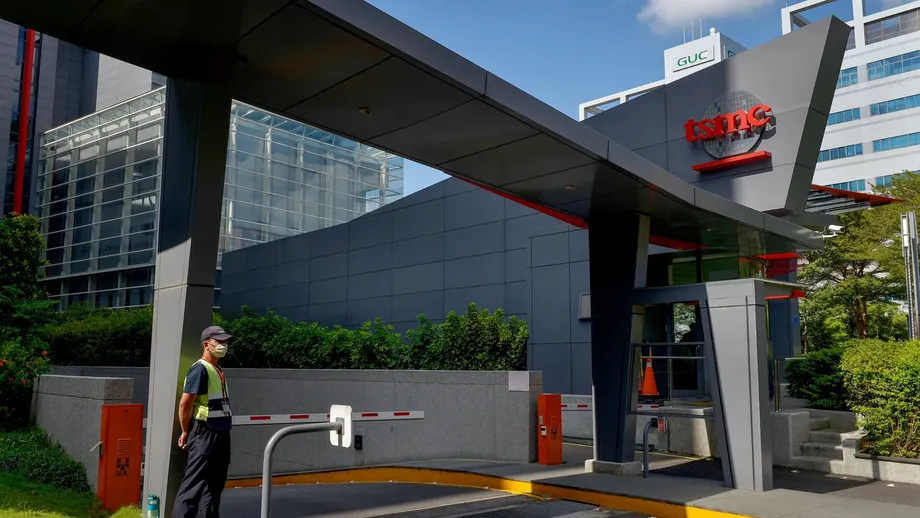
TSMC is asking equipment suppliers whether motors without rare earths could work in its factory automation systems, an effort to reduce exposure to Chinese export controls at plants producing some of the world's most advanced chips. Three industry executives briefed on the plans described the supplier survey in accounts published on October 22.
Contents
- A small factory component carries a large supply risk
- Why motors matter to chip production
- China dominates the processing and magnet stages
- Taiwan's research has reached metals and alloys
- How the research and production plans fit together
- Recycling needs the right material at the right cost
- Cleaner processing is part of the industrial challenge
- Overseas sourcing and public purchasing widen the effort
- What this means for factories and suppliers
- Key Points
The exploration comes as Taiwan pursues a broader materials strategy: domestic production equivalent to half of an anticipated annual rare earth requirement of about 2,000 tonnes by 2030. Meeting that goal would mean producing roughly 1,000 tonnes a year, while also developing the refining, recycling and manufacturing capacity needed to turn raw material into usable products.
TSMC's immediate concern is machinery. Rare earth magnets help motors move parts inside highly automated factories. A shortage of those specialized components could affect production serving smartphone makers, artificial intelligence systems, data centers and defense supply chains.
Two people familiar with the discussions said the work remained at an early stage, with no broad introduction of equipment using motors without rare earths. Suppliers are being asked to assess feasibility, and no timetable for adoption has been disclosed.
Taiwan's response therefore has two connected tracks. TSMC is exploring whether equipment can use different components, while the government and researchers are trying to secure alternative sources of the materials that industry continues to need. Both address a supply chain in which China holds a dominant position.
Why motors matter to chip production
TSMC, the world's largest contract chipmaker, manufactures chips for other companies. Its factories depend on automated machinery, and motors provide the movement that allows equipment to operate. Rare earth magnets are widely used because they support compact, efficient motor designs.
China requires export licenses for certain rare earth materials, magnets and related processing technologies. Companies dependent on controlled products must therefore account for permission to export as part of their supply arrangements.
One person familiar with TSMC's plans said concern about possible disruption from China prompted the search for alternatives. The commercial issue reaches beyond obtaining raw minerals: a chipmaker also needs equipment suppliers to deliver the specialized parts used in its factories.
ITRI researcher Cao Shen, a group leader at the institute's Material and Chemical Research Laboratories, has explained that Taiwan's semiconductor industry uses much less rare earth material directly than electric vehicle makers and industries centered on motors. Semiconductor uses include chemical mechanical polishing, which smooths surfaces during manufacturing, as well as some insulating materials and equipment.
A relatively small material requirement can still matter when it sits inside a necessary machine component. For TSMC, the practical question is whether suppliers can provide suitable motors with less exposure to controlled materials while meeting factory requirements.
China dominates the processing and magnet stages
China accounted for 91% of refined magnet rare earth production and 94% of sintered permanent magnet production in 2024, according to figures attributed to the International Energy Agency. Sintering is a manufacturing process that binds material particles into a solid magnet.
Those figures place the concentration at two stages: processing rare earths into usable materials and manufacturing a major type of finished magnet. Finding a mineral deposit elsewhere addresses only one part of the chain. Manufacturers also need separation, refining, alloy production and magnet making.
Cao said neodymium is a main ingredient in the neodymium, iron and boron permanent magnets widely used in efficient motors. Dysprosium can be added for demanding conditions involving high temperatures, heavy loads or high rotational speeds.
TSMC's supplier survey targets demand for these materials through equipment design. Taiwan's refining and recycling projects target supply. Success on either track could reduce exposure, while each requires different engineering work and commercial decisions.
Taiwan's research has reached metals and alloys
The Industrial Technology Research Institute, known as ITRI, has focused its rare earth research on neodymium and dysprosium. In November 2025, the institute said it could process resources containing about 5% rare earths into rare earth oxides and metals with 99.9% purity.
ITRI also said it had formulated neodymium, iron and boron alloy and was testing materials with domestic companies and academic institutions. An oxide is a compound containing oxygen; producing a metal and then an alloy involves further processing toward the materials used in magnets.
The institute planned to begin transferring technology to private companies in 2026. Technology transfer means making research methods and associated knowledge available for industrial use, allowing companies to develop production around the work.
Taiwan already has potential industrial customers. Taigene Metal manufactures rare earth and ferrite magnets and has a factory in Taoyuan. Local refiners would need to supply the composition, consistency and quantities that such manufacturers require.
In a statement about the current rare earth initiative, ITRI said it was working with the Department of Industrial Technology at the Ministry of Economic Affairs to plan a project. It provided no further details about that project.
How the research and production plans fit together
Economics Minister Kung Ming-hsin said in February that the government would support ITRI's rare earth technology development, with a pilot production line planned within three years. He described capacity that could meet an estimated 50% of Taiwan's domestic demand.
Officials have separately set a 2030 target of domestically producing half of an anticipated annual requirement of about 2,000 tonnes. The pilot timetable concerns building and demonstrating a production process; the national target concerns the volume Taiwan wants to supply.
The sequence of research and policy milestones shows how the effort has developed:
- 2023: A Ministry of Economic Affairs technology project began, initially establishing research equipment.
- 2024: The project moved into specific research focused on neodymium and dysprosium.
- November 2025: ITRI described its refining results and plans for technology transfer in 2026.
- February 2026: Kung announced support for a pilot production line within three years.
- October 22, 2026: Accounts of TSMC's supplier survey described early discussions about motors without rare earths.
- 2030: Taiwan aims to produce domestically half of its projected annual rare earth requirement.
The institute's research priorities extend to drones, robots and electric vehicle motors. Those sectors also need dependable magnet materials, so a domestic processing industry would serve a wider customer base than semiconductor equipment alone.
Recycling needs the right material at the right cost
Taiwan's recycling expertise offers another source of rare earths. A 2022 study by National Cheng Kung University researchers Chen Wei-sheng, Jian Guo-cai and Lee Cheng-han used magnets from discarded electric vehicle motors supplied by a local recycler.
The researchers dissolved a sample weighing one gram and tested selective separation of dysprosium from neodymium and praseodymium. Further work identified in the study included processing through multiple stages and regenerating the liquid used for extraction.
Leo Chang, vice president of UWin Nanotech, has identified access to suitable raw material and the economics of processing as central constraints. His company operates precious metal recovery technologies commercially, while its rare earth recycling applications remain under development.
Chang favors starting with concentrated, valuable waste such as permanent magnets recovered from products at the end of their useful life. Collecting mixed discarded electronics and taking them apart can add substantial costs before refining begins.
A 2026 study in AIChE Journal by Carnegie Mellon University's Chris Laliwala and colleagues modeled recovery from discarded permanent magnets. Under its assumptions, magnets from electric vehicles and hybrid vehicles could support profitable recovery. The hard disk drive case was uneconomic, partly because too little suitable material was available.
For a Taiwanese recycler, the corresponding business decision depends on local collection volumes, dismantling costs and buyers for the recovered output. A processing plant needs a dependable flow of material as well as a method for extracting valuable elements.
Cleaner processing is part of the industrial challenge
ITRI has drawn on its experience with waste acid and wastewater recycling in semiconductor and optoelectronics industries to reduce the environmental burden of rare earth refining.
The institute reported that its new process reduced waste by about 50%, chemical use by more than 40% and energy consumption by about 20%. In its November 2025 account, it set a target of reducing energy consumption by 30% by the end of 2026.
These changes matter to operating costs as well as waste management. Chemicals, energy and treatment of waste all affect the price at which a refiner can sell material. ITRI identified the balance among environmental performance, energy consumption and cost as a major development challenge.
Continuous production would also require consistent quality and sufficient volume. For a magnet manufacturer, the useful outcome is repeat deliveries of material matching its specifications at an agreed price.
Overseas sourcing and public purchasing widen the effort
Kung said in July that officials planned to visit California and Colorado the following month to assess deposits and determine whether the resources matched Taiwan's needs. He also described contacts with Australia and Canada. The work was at the sourcing assessment stage, with deliveries still to be arranged.
Imported material could supplement recovered magnets, allowing Taiwan to build processing capacity without relying entirely on domestic waste collection. The mix would depend on the elements available and the products customers wanted to buy.
Raymond F. Greene, director of the American Institute in Taiwan, Washington's de facto embassy in Taipei, said in June that the United States was working with Taiwan and other partners to develop alternative supplies, expand processing capacity and build more resilient supply chains.
U.S. officials have also discussed diversification of critical mineral supply chains with ITRI, according to a person at a U.S. think tank familiar with those discussions. Cooperation on processing would address one of the stages where China's production share is especially large.
Taiwan's Resource Circulation Promotion Act, promulgated in June, adds a purchasing measure. Article 32 requires public bodies to prioritize designated environmental and circular products and services, with product categories and assessment procedures governed by implementing rules.
Government purchasing could help create demand for recovered materials. Manufacturers would still need contracts for suitable products, connecting the policy framework to actual orders and investment.
What this means for factories and suppliers
TSMC's exploration puts a specific equipment question alongside Taiwan's broader materials ambitions. Equipment suppliers must assess whether motors without rare earths can meet the requirements of factory automation. Refiners and recyclers must organize reliable supplies of material, industrial processing and customers.
Chang also sees a role for Taiwanese companies in supplying equipment and engineering to recycling facilities near sources of discarded material overseas. He described that potential business model in these terms:
"In this way, Taiwan could become a technology and processing partner rather than simply a destination for imported waste," he said.
Securing output from such facilities for Taiwanese manufacturers would require supply agreements alongside equipment sales. That links the overseas opportunity to the same practical needs facing domestic projects: dependable inputs, suitable products and committed buyers.
For chip customers, the immediate development is preparatory work on a possible equipment alternative. For Taiwan's materials industry, the coming milestones are the planned technology transfers, the pilot production line and progress toward the 2030 volume target. Together, these efforts seek to give factories more choices about both the machinery they buy and the materials behind it.
Key Points
- TSMC has surveyed suppliers about motors without rare earths for factory automation equipment.
- Discussions remain at an early stage, with no broad equipment rollout.
- China accounted for 91% of refined magnet rare earth production and 94% of sintered permanent magnet production in 2024, according to IEA figures.
- ITRI has reported producing rare earth oxides and metals at 99.9% purity and planned technology transfer in 2026.
- Taiwan aims to supply domestically about 1,000 tonnes of a projected annual requirement of 2,000 tonnes by 2030.
- Recycling, overseas sourcing and alternative motor designs address different parts of the supply risk.