A bigger increase enters the October 22 debate
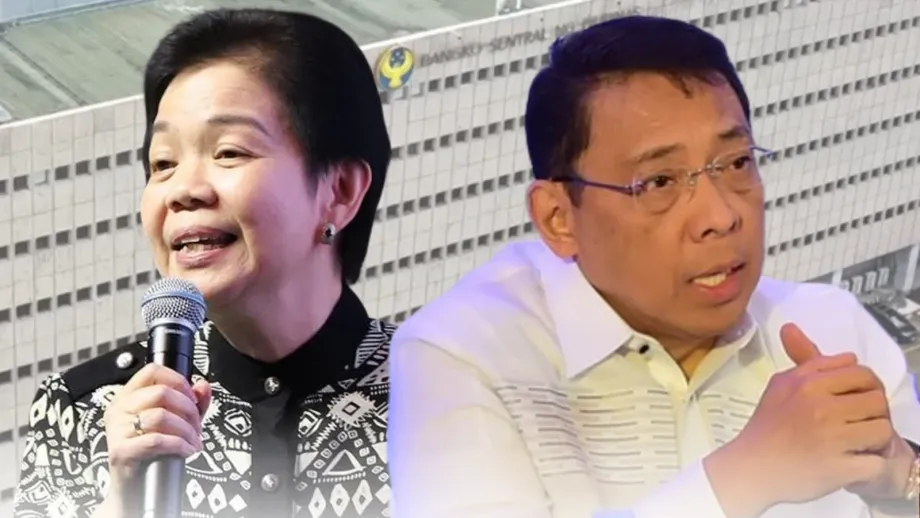
Former Bangko Sentral ng Pilipinas officials Diwa Guinigundo and Wilhelmina Mañalac are urging the central bank to consider raising its benchmark interest rate from 5% to 5.5% on October 22, 2026, as inflation spreads beyond food and fuel while economic growth remains weak.
Contents
- A bigger increase enters the October 22 debate
- Why September changed the argument
- Most economists still favour a smaller step
- The peso adds pressure through import costs
- Food and weather risks extend into 2027
- Weak growth makes tightening costly
- A spending recovery could change the balance
- Markets are already charging more
- The dates and decisions to watch
- Key Points
Their call follows September inflation of 7.2%, up from 6.1% in August, and a peso exchange rate that has weakened past PHP63 per US dollar. Core inflation, which leaves out volatile food and energy items, reached 4.7%, adding to concern that price increases are becoming more persistent.
Guinigundo, a BSP deputy governor from 2005 to 2019, and Mañalac now work as country analysts for GlobalSource Partners. In their October 20 commentary, they argued that a larger increase deserves consideration even though the economy is operating below its potential.
The two analysts explained why they favour considering a stronger response:
A hike of this scale "merits serious consideration to help anchor inflation expectations and contain the risk of further price increases."
A 50 basis point increase means adding half a percentage point to the policy rate. Most economists surveyed expect a smaller increase of 25 basis points, or a quarter of a percentage point, which would take the benchmark to 5.25%.
The choice matters beyond financial markets. Higher policy rates tend to make borrowing more expensive for households and businesses. Leaving inflation unchecked also carries a cost: food, transport and other essentials take a growing share of income, leaving families less money for everything else.
The October decision therefore turns on competing risks. A larger increase would act more forcefully against persistent inflation, while a smaller move would place less immediate pressure on an economy already struggling with weak spending and investment.
Why September changed the argument
September inflation exceeded the top of the BSP's 2% to 4% target range by 3.2 percentage points. Average inflation over the first nine months reached 5.4%, compared with the central bank's 3% target.
The annual rate rose by 1.1 percentage points between August and September. It also matched April's 7.2% reading and stood far above the 1.7% recorded in September 2025. Those figures describe how much prices increased compared with the same month a year earlier.
Core inflation of 4.7%, its highest level since October 2023, is especially important to the policy debate. By looking beyond volatile food and energy prices, the measure helps officials judge whether increases are spreading through a wider range of goods and services.
Guinigundo and Mañalac argue that this spread requires attention even when the first push comes from oil or food shortages. Transport operators, shops and other businesses may face higher costs and pass them to customers. Workers may seek higher pay to cover more expensive essentials, adding another source of business costs.
Economists call these second round effects. The BSP is trying to keep an initial price shock from developing into a continuing cycle of higher costs and prices.
Most economists still favour a smaller step
A survey of 22 economists found that 20 expected a quarter point increase to 5.25%, while two forecast a half point move. Another survey found that 12 of 13 economists expected an increase, with most favouring 25 basis points. These are separate surveys with different groups of respondents.
Nomura and Deutsche Bank both expect a quarter point increase. Nomura cited the rise in headline and core inflation, while Deutsche Bank pointed to elevated oil prices and the risk that higher costs would spread through the economy.
Jonathan Ravelas, senior adviser at Reyes Tacandong & Co., supports a larger move, alongside BPI lead economist Emilio Neri Jr., whose assessment depends partly on further peso weakness. Economist John Paolo Rivera was the sole respondent in the survey of 13 who expected the BSP to hold at 5%.
Metrobank chief economist Nicholas Mapa favours a measured quarter point increase because interest rates have limited power over inflation caused by shortages and expensive imports. UnionBank chief economist Ruben Carlo Asuncion also supports 25 basis points, balancing inflation risks against weak domestic demand.
The peso adds pressure through import costs
The peso closed at a record low of PHP63.06 per dollar on October 15. On October 16, it touched an intraday low of PHP63.23 before recovering to close at PHP62.985. A larger number means more pesos are needed to buy one dollar.
The recovery at the close gave only part of the picture. The weighted average exchange rate across the trading session weakened from PHP63.049 to PHP63.068 per dollar, indicating that transactions during the day took place at a slightly weaker average rate.
The latest decline follows the October 8 currency record, when the peso closed at PHP62.90. The subsequent PHP63.06 record close raised the peso cost of buying a dollar by another 16 centavos.
A weaker peso makes imported fuel, equipment and raw materials more expensive in local currency. Higher oil prices and currency depreciation can therefore work together, pushing up transport expenses and production costs.
Neri, BPI's lead economist, described the exchange rate condition that could support a larger October increase:
If the Peso depreciates further and moves closer to 64, the BSP may consider a 50 basis point hike on Thursday,
Gross international reserves, the country's buffer of foreign currency and other reserve assets, fell by about $13 billion during 2026 to $99.997 billion at the end of September, their lowest level in three years. Neri said preserving that buffer matters while the duration of the Middle East conflict remains uncertain.
Chinabank chief economist Domini Velasquez takes a more cautious view of using rates to support the currency. She noted that the peso weakened to around PHP62 even after the August rate increase. Guinigundo also argues that the BSP should focus on how depreciation affects Philippine prices and expectations, rather than defending a particular exchange rate.
Food and weather risks extend into 2027
Rice inflation reached 20.3% in September, according to figures cited by ANZ Research. That means rice prices were about one fifth higher than a year earlier, creating a direct squeeze on household food budgets.
El Niño adds another risk. The weather pattern can bring hotter and drier conditions that disrupt farming and reduce supplies. Nomura cited the state weather bureau's assessment that a strong El Niño could intensify through December and persist into the first half of 2027.
Chinabank estimates that El Niño could add between 0.25 and 1.57 percentage points to annual headline inflation, with most of the impact arriving next year. HSBC expects inflation to average 7.3% in the fourth quarter of 2026, led by higher food prices.
BSP Governor Eli Remolona Jr. has identified El Niño as the central bank's leading inflation risk. He described the August rate increase as preemptive, reflecting weather risks as well as the first tranche of wage increases in Metro Manila.
Higher interest rates cannot produce more rice or bring down international oil prices. Their role is to restrain borrowing and spending, and to keep households and businesses confident that inflation will eventually return toward the target.
Inflation expectations matter because they influence decisions today. A business expecting repeated cost increases may raise prices sooner, while a household expecting more expensive goods may bring purchases forward. Guinigundo and Mañalac want the BSP to reduce the risk of those responses reinforcing inflation.
Weak growth makes tightening costly
Philippine economic growth slowed from 2.8% in the first quarter of 2026 to 2.3% in the second. Growth averaged 2.6% during the first half, below the government's full year target of 3.5% to 4.5%.
Household spending growth eased from 3% in the first quarter to 2.8% in the second. Household consumption accounts for roughly two thirds of the economy, so even a modest slowdown affects many businesses.
Guinigundo and Mañalac argue that inflation itself can weaken demand when incomes fail to keep up with prices. Families must spend more on essentials and cut other purchases. Businesses then face both higher operating costs and customers with less money to spend.
The combination creates a risk of stagflation, a period of high inflation alongside weak or stagnant economic activity. The current debate concerns how to reduce that risk without placing excessive pressure on credit and spending.
A negative output gap means the economy is producing less than it potentially could. Such spare capacity would usually argue for caution about raising rates. The former BSP officials nevertheless contend that timely action is needed because persistent inflation could make recovery more difficult.
Rate increases also take time to work, typically around a year to pass fully through the economy. The BSP must consider both current weakness and the effects of increases it has already delivered.
A spending recovery could change the balance
Government infrastructure spending is central to expectations for a recovery. Delays linked to corruption allegations involving flood control projects have weighed on investment and public spending.
The Department of Budget and Management's figures put infrastructure and other capital outlays at PHP89.6 billion in July, down about 4% from PHP93.3 billion a year earlier. Spending from January through July totalled PHP457 billion, a decline of PHP256.5 billion, or 36%.
Broader public expenditure showed a stronger picture. Total spending through August rose 8.01% to PHP4.271 trillion from PHP3.954 trillion a year earlier. That amounted to about 66.05% of the PHP6.466 trillion annual expenditure programme. Infrastructure outlays and total expenditure measure different parts of government activity, helping explain why their trends can diverge.
Remolona, the BSP governor, has said faster delivery of delayed infrastructure projects could support a recovery:
I believe the government has been working strenuously to accelerate infrastructure spending, and we expect that growth will recover by the fourth quarter of 2026,
Neri argues that stronger growth would give the BSP more confidence that the economy could absorb further rate increases. Chinabank is less optimistic about infrastructure spending, household consumption and private investment, and sees the October increase as a possible end to the tightening cycle.
The World Bank, Asian Development Bank and International Monetary Fund have lowered their Philippine growth forecasts for 2026 to around 3%. The Philippine Statistics Authority is scheduled to release third quarter growth figures on November 9, providing an important checkpoint before the December policy meeting.
Markets are already charging more
Government borrowing costs have risen ahead of the October decision. Reference rate data as of October 16 showed government securities yields increasing by an average of 7.82 basis points over the week.
The yield on government bonds maturing in 10 years rose by 14.47 basis points to 8.0184%. The yield on Treasury bills maturing in one year increased by 11.12 basis points to 6.3193%.
A bond yield is the return an investor receives at the prevailing price. When bond prices fall, yields rise. Higher yields mean investors demand more compensation to hold government debt amid inflation, currency weakness and the prospect of further policy tightening.
Trading volume fell to PHP19.94 billion from PHP27.98 billion the previous week. The combination of higher yields and lower turnover shows that financial conditions are changing before the Monetary Board announces its next move.
The dates and decisions to watch
The BSP has already raised its benchmark by 75 basis points through three consecutive increases this year. Its remaining scheduled meetings are October 22 and December 17.
- April 23: The Monetary Board raised the policy rate by 25 basis points.
- June 18: A second increase added another 25 basis points.
- August 27: A third quarter point increase brought the rate to 5%.
- October 20: Guinigundo and Mañalac called for serious consideration of a half point increase.
- October 22: The Monetary Board is scheduled to decide its next policy step.
- November 9: The statistics authority is scheduled to release third quarter economic growth.
- December 17: The Monetary Board holds its final scheduled policy review of 2026.
Barclays expects quarter point increases in October and December, bringing the benchmark to 5.5% by the end of the year. A half point October increase would reach that level immediately. Neri's more adverse scenario puts the rate at 6% by December if the Middle East conflict escalates.
Other economists expect October to be the final increase unless inflation or oil prices worsen. October and November inflation readings, third quarter growth and the BSP's updated forecasts will help shape the December decision. No October decision has yet been announced.
For households, the immediate pressure remains the rising cost of essentials. For the BSP, the task is to keep those increases from spreading further while limiting the added strain on borrowing, jobs and spending.
Key Points
- Former BSP officials Guinigundo and Mañalac favour considering a 50 basis point increase on October 22, taking the policy rate to 5.5%.
- Most surveyed economists expect a smaller increase to 5.25%.
- September headline inflation reached 7.2%, while core inflation rose to 4.7%.
- Peso weakness, expensive oil and El Niño risks are adding to price pressures.
- Second quarter growth slowed to 2.3%, complicating the case for higher borrowing costs.
- Third quarter growth is due on November 9, ahead of the final scheduled policy meeting on December 17.