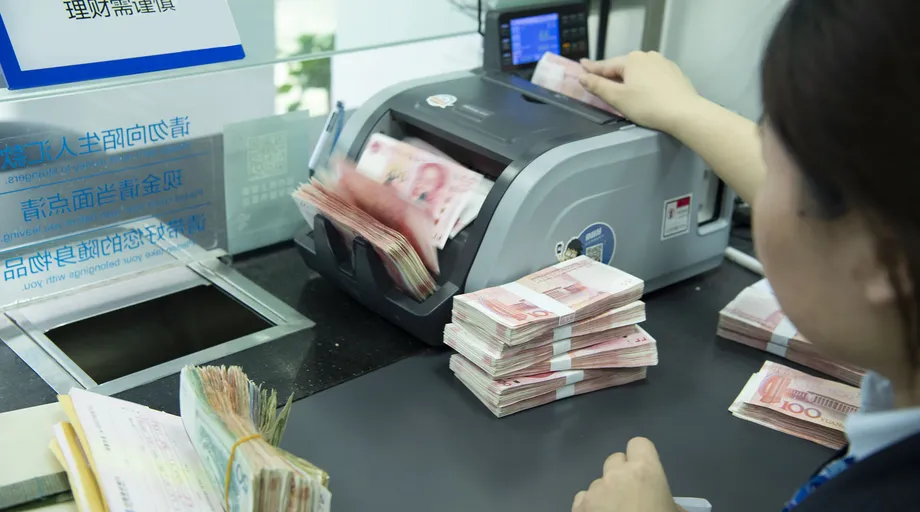
A Small Reserve Behind a Broad Guarantee
China's Deposit Insurance Fund ended 2025 with RMB130.4352 billion, about $18.5 billion, after collecting RMB65.6469 billion in bank premiums and spending RMB13.5972 billion on financial risk resolution during the year. Those precise figures show the scale of a fund whose balance amounts to roughly 0.1 percent of estimated insured deposits, far below the 1.5 percent target identified in the International Monetary Fund's 2025 assessment of China's financial sector.
Contents
- A Small Reserve Behind a Broad Guarantee
- What the 2025 Accounts Reveal
- How the 0.1 Percent Estimate Is Calculated
- Why Most Depositors Can Still Be Fully Covered
- How China Compares With Other Systems
- Baoshang Shows How Resolution Can Drain the Fund
- A Decade of Prevention and Intervention
- Who Bears Losses Beyond the Reserve?
- What Reform Proposals Would Change
- Key Points
The People's Bank of China published its annual figures on March 27, 2026. Its deposit insurance records list the 2025 release alongside annual disclosures stretching back to 2017. At the end of 2025, 3,112 banking institutions participated in the system, a more precise count than the approximately 3,000 often used to describe its reach.
The imbalance is substantial: a reserve of about RMB130 billion supports an estimated RMB124 trillion in deposits within the insurance limit. Yet that does not mean insured customers would automatically lose money if a bank failed. Recoveries from failed banks, additional industry contributions and public financing can all help cover obligations.
The central issue is who pays when the fund cannot meet the cost itself. A small reserve increases reliance on financing arranged during a crisis. If government assistance is never recovered from banks, losses that might otherwise have been funded by the industry move onto the public balance sheet.
What the 2025 Accounts Reveal
Bank premiums were the largest disclosed source of money flowing into the fund during 2025. The RMB65.6469 billion collected was equivalent to approximately half its closing deposit balance. That comparison shows that annual contributions are substantial relative to the reserve already accumulated, even though the reserve remains small relative to the deposits protected.
The accounts also recorded RMB1.7472 billion in interest income, RMB1.9706 billion returned when funding support matured, and RMB327.9 million in dividends. Recoveries from distressed assets brought in RMB4.3419 billion, while distributions from the bankruptcy estates of resolved institutions contributed another RMB151.3 million.
These categories matter because deposit insurance does not simply collect premiums and pay depositors. Some assistance can return to the fund, and assets recovered after a failure can reduce the final cost. Money initially committed to a resolution is therefore not always the same as a permanent loss.
The RMB13.5972 billion used for risk resolution in 2025 was about 10.4 percent of the closing fund balance. The annual figures establish how much was spent, but the brief disclosure does not identify the institutions receiving that support or explain how much of that year's spending may eventually be recovered. It also does not provide the insured deposit total needed to calculate an official reserve ratio directly.
How the 0.1 Percent Estimate Is Calculated
The reserve ratio measures the fund's balance against deposits protected within the statutory payout limit. It is not the ratio to all deposits in the banking system. China does not publish the insured deposit figure, so the approximately 0.1 percent estimate requires an indirect calculation.
The IMF's 2025 Financial Sector Assessment Program report identified a target fund balance of approximately RMB1.6 trillion, or $224 billion, and a target reserve ratio of 1.5 percent as of the end of 2023. Dividing RMB1.6 trillion by 1.5 percent gives an implied insured deposit base of about RMB107 trillion.
The People's Bank of China reported total deposits of approximately RMB290 trillion at the end of 2023. The implied insured amount was therefore about 37 percent of that total. Carrying that share forward to the RMB336 trillion in total deposits reported for the end of 2025 produces an estimated insured deposit base of approximately RMB124 trillion.
Dividing the closing fund balance of roughly RMB130 billion by RMB124 trillion yields about 0.105 percent, rounded to 0.1 percent. This is an estimate, not a published Chinese reserve ratio. It assumes that the insured share of total deposits stayed broadly unchanged between 2023 and 2025.
Applying the reported 1.5 percent target to that estimated 2025 deposit base would require approximately RMB1.86 trillion, about 14 times the actual balance. The resulting gap would be roughly RMB1.73 trillion. This is a comparison using the reported target ratio, not evidence that authorities have announced a revised target balance for 2025.
Why Most Depositors Can Still Be Fully Covered
China's statutory limit is RMB500,000 per depositor per bank. According to the People's Bank of China, that amount fully protects more than 99 percent of depositors. The limit has remained in place since the Deposit Insurance Regulations took effect on May 1, 2015.
That broad coverage of people can coexist with a much smaller insured share of deposit balances. Counting depositors gives each person equal weight; counting money gives greater weight to customers holding large balances. Many customers can fall entirely below the limit while a substantial amount of money remains above it.
At about five times China's GDP per person, the payout ceiling is generous by an international income comparison. The International Association of Deposit Insurers reported a median coverage limit of 2.5 times GDP per person among Group of 20 economies in 2022. China's multiple is approximately twice that median, although the comparison does not establish that it has the highest cash limit.
The coverage promise and the funding reserve answer different questions. The first defines which deposits qualify for protection. The second indicates how much industry money has already been set aside to meet costs. A broad promise backed by a small fund creates greater dependence on recoveries and additional financing when a costly failure occurs.
How China Compares With Other Systems
The United States Deposit Insurance Fund had a reserve ratio of 1.42 percent at the end of 2025, above its statutory minimum of 1.35 percent. Using China's rounded estimate of 0.1 percent, the American ratio was about 14 times as large.
The European Union generally requires national deposit guarantee schemes to reach a target of at least 0.8 percent of covered deposits. Most members have met that requirement. The Deposit Guarantee Schemes Directive allows a lower target of 0.5 percent for eligible countries with highly concentrated banking sectors; France uses that provision and meets the lower target.
Japan's reserve ratio stood at 0.43 percent at the end of March 2026, more than four times China's rounded estimate. Brazil and India also have substantially higher ratios than many advanced economies. The Japanese figure has a different reporting date from the Chinese and American figures, which should be kept in mind when comparing them.
These comparisons show the size of China's funding gap, but they do not rank the likelihood of depositor losses. Insurance systems differ in their financing arrangements, resolution powers and access to public assistance. A reserve ratio is a measure of accumulated resources, not a complete measure of the strength of a country's financial safety net.
Baoshang Shows How Resolution Can Drain the Fund
Baoshang Bank's failure illustrates the pressure that a single resolution can place on the reserve. In 2020, the fund spent RMB93 billion on resolving the bank, roughly three quarters of its reserves at the time. The People's Bank of China supplied additional funding support.
The protection granted during the 2019 intervention extended well beyond the standard insurance ceiling. All household deposits were protected, while other claims of up to RMB50 million received full protection. That threshold was 100 times the statutory RMB500,000 deposit insurance limit. Larger claims received partial protection.
Such decisions can help contain panic and preserve banking services, but they also widen the claims that resolution financing must support. If resources accumulated for limited deposit protection are used to protect creditors beyond that limit, the cost can be much larger than the statutory guarantee alone would suggest.
Meng Hui, director of the People's Bank of China's Financial Stability Bureau, has described Baoshang's takeover, transfer of business and bankruptcy liquidation as a successful market exit that protected depositors while maintaining business continuity. His account also identifies support for some city commercial banks in Liaoning and for Liaoyang Rural Commercial Bank. The distinction is between a resolution's operational success and its cost to the safety net: both can be substantial at the same time.
A Decade of Prevention and Intervention
Deposit insurance in China has responsibilities before a bank fails, rather than functioning solely as a mechanism that pays customers afterward. Meng's account says the system collected RMB373.2 billion in premiums cumulatively from its establishment to the period covered by his article marking its tenth anniversary. That is a historical collection figure, not the end of 2025 fund balance.
The main milestones show how the system's role expanded:
- May 1, 2015: The Deposit Insurance Regulations took effect.
- 2016: Premium setting moved from a benchmark rate to rates linked to institutional risk.
- From 2017: Early corrective action sought to reduce risks before institutions needed resolution.
- 2019: The fund began participating in risk resolution, including Baoshang Bank, and a deposit insurance company was established.
- November 2020: The deposit insurance identification mark was introduced throughout the system.
- 2022: Financial regulators established the Financial Stability Guarantee Fund.
- March 27, 2026: The central bank published the 2025 fund accounts.
Meng says early corrective work has helped achieve an initial reduction of risk at more than 600 institutions since 2017. Measures included requiring additional capital, controlling asset growth, restricting major credit transactions and reducing leverage, meaning borrowing relative to the institution's financial resources.
Preventive work and reserve building address different parts of the same problem. Earlier action can reduce the number and cost of failures. It cannot guarantee that every troubled institution will recover, which leaves a continuing need for sufficient funds and clear financing arrangements.
Who Bears Losses Beyond the Reserve?
When a failed bank's assets can be sold or its loans collected, the proceeds can reimburse part of the resolution cost. The 2025 accounts show this process in practice through distressed asset recoveries and bankruptcy distributions. Recoveries, however, may arrive after money is needed to preserve access to deposits.
Additional bank contributions can close a gap, but their timing matters. Requiring larger payments during a period of financial stress can weaken institutions that are already facing losses or funding pressure. Collecting more while conditions are relatively stable spreads the burden earlier and builds resources before they are needed.
Government support offers another route. Central or local authorities can provide public resources, and expectations of such support may help explain why a small insurance fund has not visibly undermined depositor confidence. The Financial Stability Guarantee Fund may also provide assistance, although its size, functions and relationship with deposit insurance are not sufficiently clear in public disclosures.
Temporary public financing and permanent public losses are not the same thing. If banks later repay the cost through assessments, the industry ultimately bears it. If there is no effective recovery mechanism, the cost stays with the government. Broad protection without clear loss sharing can also reduce the incentive for banks and large creditors to account for risk.
What Reform Proposals Would Change
Meng's proposed changes overlap with the concern that the fund needs a larger reserve. He calls for expanding accumulated resources, widening investment options while protecting fund safety, and exploring backup financing that could supply liquidity when needed. His account also points to the 2025 government work report's call to replenish resources for managing financial risks, including deposit insurance.
The case for higher contributions is strongest when paired with the existing practice of charging according to risk. Banks posing greater danger to the fund would contribute more, while the system would build reserves before a crisis forces an abrupt increase in charges. No timetable for reaching the reported 1.5 percent target is identified.
Spending rules are equally important. A larger reserve could still be depleted if future resolutions routinely protected claims beyond the statutory ceiling. A disciplined approach would require shareholders and uninsured creditors to bear losses according to their legal position, with any exceptional public assistance accompanied by a mechanism to recover costs from the industry.
Meng also proposes eventually replacing the Deposit Insurance Regulations with a deposit insurance law, strengthening early corrective measures and expanding resolution tools. These are proposals, not enacted changes. There is no specified legislative date, premium increase schedule or deadline for clarifying how the two funds would work together.
The immediate disclosure gap is more basic: publishing insured deposit totals would allow the reserve ratio to be calculated directly and tracked consistently. Until that happens, the estimated 0.1 percent ratio remains dependent on carrying forward the insured share inferred from the IMF's 2023 target figures.
Key Points
- China's deposit insurance fund closed 2025 with RMB130.4352 billion and covered 3,112 participating banking institutions.
- The fund collected RMB65.6469 billion in premiums and spent RMB13.5972 billion on risk resolution in 2025.
- Its estimated reserve ratio was approximately 0.1 percent, compared with the 1.5 percent target reported by the IMF.
- The RMB500,000 limit per depositor per bank fully protects more than 99 percent of depositors, according to the central bank.
- Baoshang's resolution consumed RMB93 billion from the fund in 2020 and included protection beyond the statutory limit.
- A small reserve does not automatically mean depositor losses, but it increases dependence on additional financing.
- Proposals include larger reserves, stronger corrective powers and backup financing. No implementation timetable is specified.