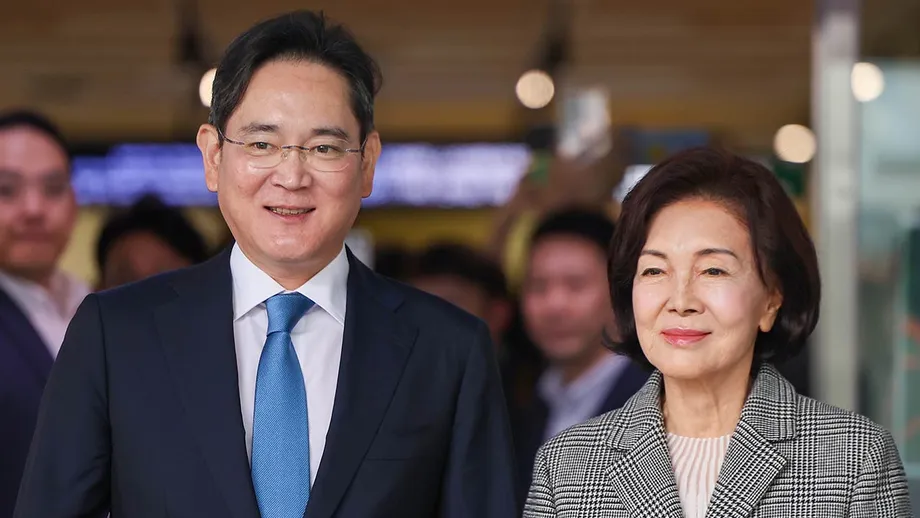
11.158 Million Shares Set to Change Hands
Samsung Electronics Chairman Lee Jae-yong is scheduled to receive 11,158,000 shares in the company from his mother, Hong Ra-hee, honorary director of the Leeum Museum of Art, in a gift worth approximately 2.6 trillion won. The agreement was signed on October 12, with the transfer planned for November 12, 2026, according to reports describing the company's October 13 regulatory disclosure.
Contents
- 11.158 Million Shares Set to Change Hands
- What Changes in the Ownership Figures?
- Why the Valuation Is About 2.6 Trillion Won
- The Earlier Purchase Was Revised Before Completion
- How the Gift Tax Will Be Calculated
- Inheritance Taxes Shaped Hong's Share Transfers
- The Key Dates and a Separate Samsung C&T Gift
- More Direct Ownership, No New Company Funding
- Dividends Could Rise, but Funding Plans Are Unclear
- Key Points
The transfer would increase Lee's holdings from 105,219,053 shares to 116,377,053 shares, raising his reported stake from 1.58% to 1.75%. Although the increase amounts to just 0.17 percentage points of Samsung Electronics, the gifted shares equal about 10.6% of his current holdings. That makes it a substantial increase in his personal investment without changing the controlling family's combined ownership.
The gift follows a separate purchase of shares from Hong and comes after years of asset transfers connected with the estate of her husband, former Samsung Chairman Lee Kun-hee, who died in 2020. The distinction between the two transactions matters: the purchase gives Hong cash, while the gift transfers ownership without payment and creates a prospective tax obligation for Lee.
The estimated gift tax is between 1.55 trillion and 1.56 trillion won. Neither that bill nor the taxable value of the shares is final. Both depend on a valuation period extending beyond the scheduled transfer, with the tax amount expected to be established in early 2027.
What Changes in the Ownership Figures?
The central figures for Lee are consistent across the accounts: he would receive 11,158,000 common shares and finish with 116,377,053 shares, equivalent to a reported 1.75% stake. One account gives Samsung Electronics' total issued shares as 6,648,649,811. Against that total, the gift represents approximately 0.168%, which rounds to 0.17%.
Reports differ on Hong's ownership percentages. Several put her stake at 0.98% before the transfer and 0.81% afterward. Others give 0.99% before and 0.82% afterward. Both versions describe a decline of 0.17 percentage points, but the precise starting and ending percentages are not consistent.
The distinction between a percentage and a percentage point also helps explain the size of Lee's gain. Moving from 1.58% to 1.75% adds 0.17 percentage points to his ownership of the company. Relative to his existing shareholding, however, it represents an increase of roughly one tenth. The transfer strengthens his direct position rather than expanding the family's total stake.
Why the Valuation Is About 2.6 Trillion Won
Reports give three different closing prices for Samsung Electronics on October 13: 232,000 won, 233,500 won and, in one account, 236,000 won. Each produces a valuation close to 2.6 trillion won, but they should not be treated as the same exact price.
At 232,000 won per share, the gift is worth 2,588,656,000,000 won, or about 2.589 trillion won. At 233,500 won, it is worth 2,605,393,000,000 won, or about 2.605 trillion won. Using 236,000 won gives approximately 2.633 trillion won. The difference between the lowest and highest of those calculations is about 44.6 billion won.
Dollar estimates also differ, with accounts describing the gift as worth approximately $1.8 billion or $1.94 billion. The won amount is the more consistent measure of the transaction. None of these figures represents cash paid to Hong, and none fixes the value that will ultimately be used for gift tax.
One account using the 232,000 won closing price says Samsung Electronics fell 18,500 won, or 7.39%, that day. Another records a decline from 259,500 won on September 11 to 233,500 won on October 13, approximately 10%. These movements illustrate why a valuation based on one closing price can differ from the average used for taxation. They do not establish that the family transaction caused the share price decline.
The Earlier Purchase Was Revised Before Completion
The preceding share purchase explains some of the conflicting figures in coverage of the family's transactions. A September plan called for Lee to buy 7,188,793 shares from Hong at 269,500 won each, a transaction worth approximately 1.94 trillion won. Several accounts describe that planned purchase as a completed September sale or retain its share count when discussing the later transaction.
More detailed accounts state that the purchase completed on October 12 involved 7,667,100 shares at 250,500 won each. Those figures produce a total of 1,920,608,550,000 won, approximately 1.921 trillion won. The reported explanation is that changes in the share price altered the quantity and price between the September disclosure and completion.
The completed purchase therefore involved 478,307 more shares than initially planned, at a price 19,000 won lower per share. Lee's reported ownership rose from 1.47% to 1.58% following that purchase, before the proposed gift would lift it to 1.75%.
Using the completed purchase figure of 7,667,100 shares, the purchase and gift together would move 18,825,100 shares from Hong to Lee. That equals approximately 0.283% of the stated issued share total. Reports using 7.19 million shares describe a different total, making the distinction between the initial plan and the reported completed transaction essential.
How the Gift Tax Will Be Calculated
The reported valuation rule for listed shares uses the average closing price over the two months before and the two months after the actual gift date. If the transfer takes place on November 12 as scheduled, the relevant prices would run approximately from mid September 2026 to mid January 2027.
This means the October 13 closing price serves only as a preliminary reference. Lower prices during the valuation period would reduce the average, while higher prices would increase it. The future portion of that period has to finish before the taxable share value can be established.
The estimated tax bill is 1.55 trillion won in one account and approximately 1.56 trillion won in several others. One explicitly says its estimate includes the premium applied when valuing shares held by controlling shareholders. Another states that the highest gift tax rate is 50% for the portion of the taxable base above 3 billion won.
The roughly 1.56 trillion won estimate is about 60% of the headline 2.6 trillion won market value. That should not be read as a simple statutory tax rate of 60%. A premium can increase the value assessed for tax purposes above the shares' ordinary market value. The final assessment and Lee's payment arrangements have not been disclosed in the accounts.
Inheritance Taxes Shaped Hong's Share Transfers
The transactions follow the family's efforts to fund inheritance taxes after Lee Kun-hee's death in 2020. One detailed account says the Samsung family paid 12 trillion won in six installments beginning in 2021 and completed the payment process in April 2026.
Hong reportedly took out a loan of approximately 1 trillion won secured against shares to help meet inheritance tax obligations. The earlier sale to Lee was described as a way to repay borrowing associated with those taxes. Completing the inheritance tax payments would not necessarily mean that every loan used to fund them had also been repaid.
The same detailed account says Hong inherited 83,091,066 Samsung Electronics common shares in April 2021, increasing her holdings at that point to 137,244,666 shares. She subsequently sold shares in several stages, beginning with a disposal of 19,941,860 shares in March 2022 through a large transaction outside regular trading hours.
Further disposals followed in 2024, October 2025 and the first half of 2026. According to that account, those disposals, together with the recent purchase by Lee and the planned gift, total 83,091,066 shares, matching the number she inherited. This does not mean Hong would have no Samsung Electronics shares left. Both sets of reported ownership percentages show that she would retain a stake after the gift.
The Key Dates and a Separate Samsung C&T Gift
The Samsung Electronics transfer is part of a sequence rather than an isolated event. The main reported dates show the progression from inheritance obligations to a purchase and then a gift:
- 2020: Former Samsung Chairman Lee Kun-hee died, leaving the family with substantial inheritance tax obligations.
- April 2021: Hong inherited 83,091,066 Samsung Electronics common shares.
- March 2022: Hong began a series of disposals with a sale of 19,941,860 shares.
- April 2026: The family reportedly completed its six installment inheritance tax payment process.
- September 2026: A plan was disclosed for Lee to purchase shares from Hong.
- October 12, 2026: The gift agreement was signed, and detailed accounts place completion of the separate purchase on this date.
- October 13, 2026: The planned gift was disclosed.
- November 12, 2026: The gift is scheduled to take place.
- Early 2027: The gift tax amount is expected to be determined after the share valuation period ends.
Hong also transferred her entire Samsung C&T holding to Lee, but reports disagree on the date and exact share count. Several describe a gift at the end of the previous year, including last December, of 1,808,577 shares representing approximately 1.06%. Another places it in January 2026 and gives 1,808,557 shares, a difference of 20 shares.
Those discrepancies prevent a single precise account of that earlier transfer. The consistent point is that Hong gave Lee her entire Samsung C&T stake before the latest planned Samsung Electronics gift, adding to the movement of family holdings into his name.
More Direct Ownership, No New Company Funding
The gift transfers existing shares between two shareholders. It does not increase the number of Samsung Electronics shares in issue, dilute other investors' ownership or bring new money into the company. The preceding purchase similarly paid Hong rather than Samsung Electronics.
Samsung said it had no separate corporate position because the arrangement was a private transaction between major shareholders. The company also expected limited market impact from a transfer within the family. That explanation concerns the mechanics of the transaction, not a guarantee about future market prices.
Lee's larger direct holding also needs to be viewed alongside the wider ownership structure. Samsung Life Insurance is reported to hold 8.51% of Samsung Electronics. The largest shareholder group, including Samsung affiliates, family members and related executives, is reported to hold 19.7% of voting shares.
Lee's projected 1.75% stake therefore does not by itself amount to majority control. The wider group structure, described as centered on Samsung C&T, would remain in place. What changes is the distribution of holdings within that structure: more Samsung Electronics shares would belong directly to Lee, while fewer would belong to Hong.
Dividends Could Rise, but Funding Plans Are Unclear
A larger shareholding would entitle Lee to more dividend income whenever Samsung Electronics pays dividends on those shares. The gift increases his share count by about 10.6%, so an unchanged dividend per share would increase the dividend attributable to these holdings by the same proportion once he qualifies for the payment.
One account describes Samsung Electronics as having announced 90 trillion to 110 trillion won in shareholder returns for the year. It also gives a KB Securities forecast of 70 trillion won in dividends during the second half. These figures have different meanings: shareholder returns are not necessarily all dividends, and a securities firm's forecast is not a confirmed payment.
The same account raises the possibility of separate taxation for income from high dividend payments if Samsung Electronics satisfies the relevant requirements. It does not establish that the company has qualified or that Lee will receive that treatment.
No disclosed plan explains how Lee would fund the estimated gift tax. Future dividends may increase his income, but the reported figures do not demonstrate that any particular distribution has been set aside for the bill. The immediate milestones are completion of the November 12 transfer, the end of the valuation period in approximately mid January and the expected tax calculation in early 2027.
Key Points
- Hong Ra-hee plans to give Lee Jae-yong 11,158,000 Samsung Electronics shares on November 12, 2026.
- Lee's holdings would rise to 116,377,053 shares, increasing his reported stake from 1.58% to 1.75%.
- The gift is worth approximately 2.6 trillion won, although reports differ on the reference closing price.
- Hong's remaining stake is reported as either 0.81% or 0.82%; the family's combined ownership would not change.
- Detailed accounts put Lee's preceding purchase at 7,667,100 shares for approximately 1.921 trillion won, revised from the September plan.
- Gift tax is estimated at 1.55 trillion to 1.56 trillion won, with the final amount expected in early 2027.
- The transfer creates no new Samsung Electronics shares and provides no new funding to the company.