Record commitments put investment quality to the test
Vietnam registered $50.36 billion in foreign direct investment through September 30, 2026, up 76.4 percent from a year earlier, while actual investment disbursement reached $21.07 billion, according to the National Statistics Office under the Ministry of Finance. The surge comes as Vietnam pursues a more selective investment strategy, seeking technology, research, skilled employment and stronger connections between multinational companies and domestic suppliers.
Contents
- Record commitments put investment quality to the test
- What the nine month figures reveal
- Singapore anchors the regional investment relationship
- Resolution 10 sets targets beyond capital volume
- Government plans tie support to delivery
- Acquisitions offer another route into Vietnam
- Governance becomes part of the financing decision
- Suppliers, skills and infrastructure must keep pace
- The sequence from policy to implementation
- Key Points
The September figures give fresh weight to the discussion at KPMG's Vietnam's Next Cycle briefing in Singapore on August 25. Investors and business leaders examined a shift from choosing factory locations toward placing research and development operations, regional business functions and capital in Vietnam. Manufacturing remains the foundation, but acquisitions, strategic partnerships and investments in services are becoming more prominent.
The policy ambitions are specific. Politburo Resolution No. 10-NQ/TW, dated June 8, 2026, targets $200 billion to $300 billion in registered foreign investment during 2026–2030, alongside $150 billion to $200 billion in implemented investment. It also seeks 10,000 Vietnamese businesses participating in foreign investment supply chains and at least three leading global technology companies establishing headquarters, offices or research operations.
The distinction between commitments and delivery is central. Registered capital records investment commitments, including new projects, expansions and certain share transactions. Disbursement measures capital actually deployed. Both are rising, but commitments are growing much faster. Vietnam's next investment cycle therefore depends on converting investor interest into operating businesses, productive infrastructure and measurable domestic benefits.
What the nine month figures reveal
The $50.36 billion total consists of three different channels: $29.24 billion registered across 3,108 newly licensed projects, $14.15 billion added to 948 existing projects, and $6.97 billion in capital contributions and share purchases. These categories show that investors are entering Vietnam, expanding established operations and buying positions in businesses already operating there.
New project numbers rose 6.2 percent, while their registered capital reached 2.4 times the comparable figure a year earlier. Capital growth far exceeded growth in project numbers, indicating larger average commitments per newly licensed project. Additional investment in existing projects rose 25.1 percent, while capital contributions and share purchases increased 44 percent.
Manufacturing and processing attracted $13.38 billion in new registrations, or 45.8 percent of the total. Transport and storage followed with $5.14 billion, or 17.6 percent. Including expansions, manufacturing received $21.82 billion, representing 50.3 percent of new and adjusted capital, while real estate attracted $6.94 billion.
Actual deployment remains more concentrated. Manufacturing accounted for $17.40 billion, or 82.6 percent, of disbursed investment. Real estate received $1.59 billion, and electricity, gas and related utility activities received $723.4 million. The contrast suggests diversification is more advanced in investment commitments than in money already put to work.
First half registered investment was $34.65 billion, up 61 percent, while disbursement reached $13.03 billion, up 11.2 percent. Although the Singapore briefing described a narrowing gap between commitment and delivery, the aggregate figures do not establish that conclusion: by September, registered capital was rising 76.4 percent against 12.1 percent growth in disbursement. Projects deploy money over several years, so these figures are not a direct completion measure, but they do show that implementation has not matched the pace of new commitments.
Singapore anchors the regional investment relationship
Singapore led newly registered investment through September with $9.26 billion, or 31.7 percent of the total, among 79 investing countries and territories. South Korea followed with $5.70 billion and Luxembourg with $4.99 billion. Hong Kong contributed $3.01 billion, China $2.27 billion and Japan $1.56 billion.
Singapore's cumulative registered investment in Vietnam stood at nearly $97 billion across more than 4,500 projects, making it the country's second largest foreign investor. Its role as a regional centre for headquarters, finance and transactions helps explain why KPMG chose it to open the briefing series.
The relationship gained a broader framework in March 2025, when the countries established a Comprehensive Strategic Partnership, Singapore's first with another ASEAN member. It builds on their 2013 Strategic Partnership and 2023 Green-Digital Economic Partnership, extending cooperation into energy connectivity, innovation, the digital economy and capital markets.
Planned stock market connectivity and depository receipt arrangements could provide additional routes for investment. Depository receipts are securities representing shares in a company listed in another market, allowing investors to gain exposure through a different exchange. These initiatives should be distinguished from investment already committed or deployed.
Yap Wee Kee, partner of Capital Markets Group and Private Enterprise at KPMG in Singapore, said businesses should align their regional plans with the different strengths of ASEAN economies.
"The opportunity for Singapore enterprises lies in understanding those strengths and aligning their regional strategy accordingly," he said.
Resolution 10 sets targets beyond capital volume
Resolution 10 seeks to bring 75 percent of foreign investment from developed economies with strong technology, capital and modern management capabilities. By 2030, Vietnam aims to rank among ASEAN leaders in the investment environment, competitiveness, innovation, public service quality and capacity to receive investment projects of higher quality.
Its industrial targets include localisation of 45–50 percent in key industries, meaning a greater share of production value would be generated domestically. Alongside the goal of 10,000 Vietnamese companies in foreign investment supply chains, it seeks 500–1,000 Vietnamese suppliers working directly with major producers. These objectives connect foreign capital attraction to the development of domestic business capabilities.
Priority areas include semiconductors, artificial intelligence, big data, cloud computing, biotechnology, advanced materials, green industries, logistics and financial services. Vietnam also wants regional headquarters, treasury and procurement centres, data centres and research facilities, rather than production plants alone.
The longer horizon extends to 2045, when the foreign invested sector is envisaged to contribute approximately 30 percent of GDP and 25 percent of total social investment. A separate private sector agenda under Resolution 68 targets a contribution of 55–58 percent of GDP by 2030 and more than 60 percent by 2045. These targets should not simply be added together, because the categories describe different aspects of economic ownership and activity.
Resolution 10 sets policy direction rather than directly amending existing laws. Its practical effect depends on subsequent legislation, regulations and administrative execution. Investors can use it to understand government priorities, but it does not by itself establish a new entitlement to incentives or market access.
Government plans tie support to delivery
Government Resolution No. 280/NQ-CP, issued September 22, 2026, provides the action plan for implementing Resolution 10. It directs ministries and local authorities to review rules across investment, land, construction, taxation, customs, securities, intellectual property, data and labour, identifying overlapping requirements and unnecessary business conditions.
The plan calls for digital administrative procedures, connected agency systems and investment management using digital data and artificial intelligence. Decentralised authority is to be accompanied by standardised processes, transparency and effective checks after approvals. The purpose is to reduce processing time and compliance costs without abandoning oversight.
The Ministry of Finance is tasked with developing proposed support mechanisms for strategic projects, linked to technology transfer, research, workforce training, domestic value added, local supplier development and green and digital transitions. Investor commitments would be monitored periodically, with incentives or support withdrawn when commitments are not fulfilled.
This creates a different investment proposition from support based mainly on project size. A company seeking preferential treatment may need to demonstrate what technology it transfers, which Vietnamese suppliers it develops, how many workers it trains and whether promised environmental outcomes are delivered.
The plan also calls for reviewing restrictions on foreign market access, including possible relaxation of ownership limits in selected sectors. These are directions for review and policy development, not confirmation that particular limits have already changed. Proposed local budget support for workforce training likewise requires further policy action.
Acquisitions offer another route into Vietnam
The Singapore discussion identified growing interest in growth capital, strategic partnerships, succession transactions and platform acquisitions. Growth capital finances expansion, while a platform acquisition gives an investor an established business from which to build a larger operation. For businesses led by their founders, succession planning can also create opportunities for new ownership or management arrangements.
The September statistics show the scale of equity activity. Foreign investors completed 2,335 capital contribution and share purchase transactions worth $6.97 billion. Of these, 725 transactions worth $2.64 billion increased company charter capital. The remaining 1,610, worth $4.33 billion, involved purchases of existing domestic shares without increasing charter capital.
That distinction matters: an acquisition can change ownership without injecting new equity into the company. About 62 percent of the recorded value involved existing shares, calculated from $4.33 billion out of $6.97 billion. Professional, scientific and technical activities attracted $2.75 billion, or 39.5 percent, while wholesale, retail and vehicle repair activities received $2.02 billion, or 28.9 percent.
These administrative figures are not directly comparable with a separate KPMG tally of around 220 M&A deals worth $2.3 billion through November 2025. That tally reported an average deal size of $29.4 million, down from $50.7 million in 2024. However, dividing $2.3 billion by 220 produces approximately $10.5 million. The published figures therefore appear to use different coverage for the average, or contain an inconsistency that is not explained.
Named 2025 transactions included Birch's $365 million acquisition of Phuong Dong Real Estate, AEON's $162 million acquisition of Post and Telecommunications Finance Company, and a $277 million Hyosung restructuring. Together, they total $804 million, approximately 35 percent of the reported $2.3 billion market value. Real estate attracted 27 percent of M&A capital, with materials and healthcare also among the leading sectors.
Governance becomes part of the financing decision
Vietnam's resilience does not mean investors will fund every growing business. Across Southeast Asia, transaction activity was subdued for much of 2025 as financial conditions, valuation differences, regulatory uncertainty and geopolitical risks restrained confidence. In Vietnam, the Singapore discussion pointed to governance, reliable reporting and credible plans for creating value as increasingly important selection criteria.
Warrick Cleine MBE, chairman and CEO of KPMG in Vietnam and Cambodia, explained why market potential alone is becoming insufficient.
The opportunity in Vietnam is no longer just a growth story. As the market matures, investors are becoming increasingly selective about where they place capital and whom they partner with. Factors such as governance, transparency, talent, operational readiness, and the ability to execute at scale are becoming as important as market potential.
For a Vietnamese company, this connects governance directly to financing. Clear accounts, documented ownership, effective management controls and credible operating plans affect whether investors can assess risk and agree on a valuation. Succession transactions require particular attention to whether the business can function beyond its founder.
Vo Ha Duyen of VILAF said special investment procedures linked to technology could shorten permitting by nine to 12 months. Discussions of deal confidence nevertheless identified regulatory inconsistency, uncertain approvals for foreign buyers and unclear exit routes as continuing concerns. Faster procedures in selected cases do not establish uniform certainty across all acquisitions.
Douglas Jackson, managing director of Alvarez & Marsal Vietnam, associated a provisional stock market upgrade with potential portfolio inflows and better exit options. Those were expectations, rather than completed outcomes. Resolution 10 separately targets an MSCI upgrade before 2030; that ambition should not be treated as the same event as the provisional classification discussed in 2025.
Suppliers, skills and infrastructure must keep pace
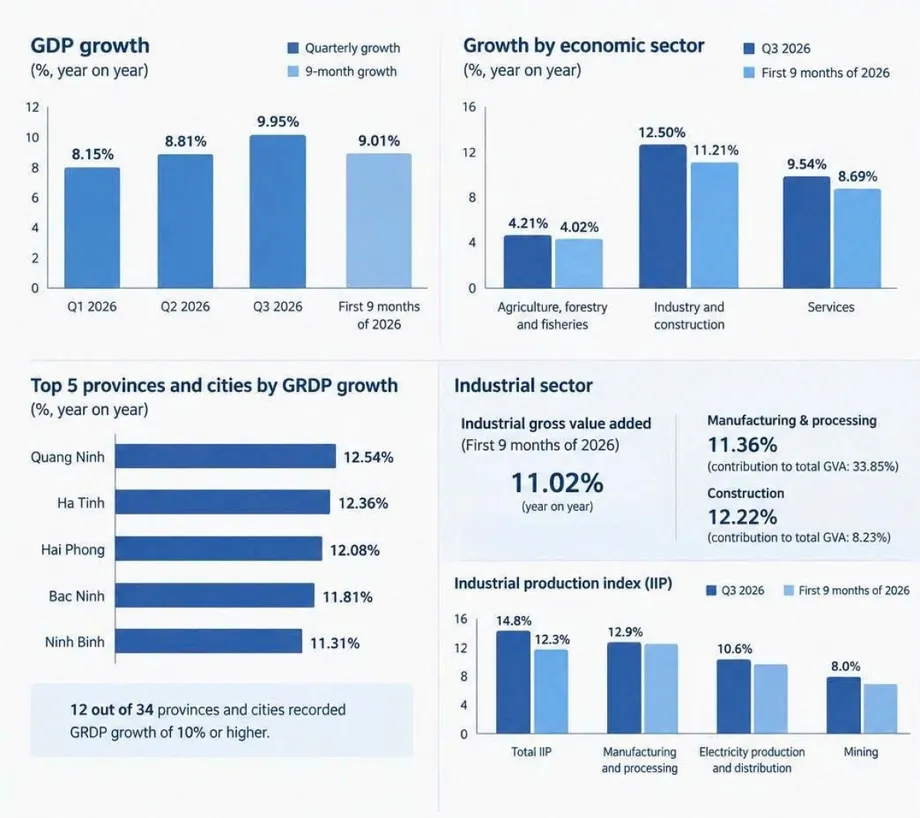
Vietnam's economy reached approximately $514 billion in 2025, with GDP growth of 8.02 percent. Government ambitions of roughly 10 percent annual growth during 2026–2030 are accompanied by plans for rail, airports, ports, digital infrastructure and renewable energy. These are enabling investments for the more sophisticated operations Vietnam hopes to attract.
At an October 8 seminar in Hanoi, Kamijo Hiroki, deputy CEO of VPBank, described five priorities: supplier localisation, international treasury services, talent, green transition and M&A. He said the VPBank and Sumitomo Mitsui Banking Corporation partnership combines local business relationships and execution with global corporate networks and access to international funding.
Hiroki's proposal makes the supplier targets more concrete. Vietnamese businesses seeking multinational customers may need support with production capacity, technology, quality systems, financial strength and governance. Treasury services address another practical need: managing foreign exchange, liquidity, documentation and cash across countries. The partnership proposes organising cooperation through four steps, align, connect, mobilise and scale, rather than treating financing as a standalone activity.
Skills development also has a policy framework. Decision No. 1002/QD-TTg, dated May 24, 2025, covers training for advanced technology industries during 2025–2035, with an outlook to 2045. The government action plan prioritises technology, engineering, data, automation, production management, logistics and finance. Regional cooperation includes the innovation talent exchange between Singapore and Vietnam, designed for placements of up to two years in fields including AI, cybersecurity and semiconductors, with an annual quota of 300 applications.
Infrastructure needs extend beyond transport and electricity. Hugo Virag, managing director and co-head of Southeast Asia at Astris Finance, cited estimates of $20 billion to $30 billion required for Vietnam's water sector by 2030. Water access, drainage, reliable power and stronger grids are practical conditions for expanding industrial activity, not separate concerns from investment attraction.
The sequence from policy to implementation
The developments span several years, with successive steps linking diplomatic cooperation, workforce preparation, investment policy and capital flows.
- March 2025: Singapore and Vietnam established a Comprehensive Strategic Partnership.
- May 24, 2025: Decision No. 1002/QD-TTg approved the advanced technology workforce training programme.
- June 8, 2026: The Politburo issued Resolution No. 10-NQ/TW on foreign investment development through 2030, with a vision to 2045.
- August 25: KPMG opened its Vietnam's Next Cycle briefing series in Singapore.
- September 22, 2026: Government Resolution No. 280/NQ-CP established the implementation action plan.
- September 30, 2026: Registered FDI reached $50.36 billion and disbursed FDI reached $21.07 billion.
- October 8: The Hanoi seminar examined banking partnerships, supplier development and the capabilities needed for the next investment cycle.
The next milestones are the 2030 investment, supplier and localisation targets, followed by the 2045 economic contribution goals. Detailed incentive eligibility, changes to specific foreign ownership restrictions and the proposed workforce training support mechanism still depend on further decisions. No specific forthcoming hearing, vote or publication date has been identified for those measures.
Key Points
- Vietnam registered $50.36 billion in FDI through September 2026, up 76.4 percent; disbursement rose 12.1 percent to $21.07 billion.
- Singapore led newly registered investment with $9.26 billion, or 31.7 percent of the total.
- Resolution 10 targets $200 billion to $300 billion in registered investment and $150 billion to $200 billion in implemented investment during 2026–2030.
- Manufacturing received 82.6 percent of disbursed FDI, despite a broader mix of new commitments.
- Foreign capital contributions and share purchases reached $6.97 billion across 2,335 transactions.
- Future support is intended to reward technology transfer, workforce training, domestic suppliers and environmental performance.
- Policy implementation, business governance and infrastructure readiness will determine how much committed capital becomes productive investment.