A semiconductor tax windfall puts fiscal choices under scrutiny
South Korea's proposed Future Response Fund would direct 162.3 trillion won in projected additional tax revenue toward three purposes in 2027: 45.4 trillion won for projects, 12.5 trillion won to reduce new government borrowing and 104.4 trillion won held in reserve. Fiscal scholars are challenging whether a fund intended to protect future generations should immediately finance programs that could require payments for years.
Contents
- A semiconductor tax windfall puts fiscal choices under scrutiny
- What the government wants the fund to do
- Why some economists want a decade of saving
- Saving while borrowing creates a separate cost question
- Recurring projects could consume the buffer
- Which projects qualify as future investment?
- How much control would parliament retain?
- Local governments face a change in financial autonomy
- A larger headline total is not money already saved
- What the design debate leaves unresolved
- Key Points
Yeom Myeong-bae, emeritus economics professor at Chungnam National University, proposes saving for roughly 10 years before spending a limited proportion of accumulated resources, with government debt repayment taking priority. Another economist, Hwang Sung-hyun of Incheon National University, argues that the fund should be abandoned because the government would accumulate its reserve while issuing 106 trillion won in new government bonds.
The government presents a different case: semiconductor earnings are producing unusually strong tax receipts, and some of that money should be saved against a downturn while some supports future growth. The central dispute is therefore not simply whether to spend or save. It concerns when revenue becomes reliable enough to commit, which expenditures genuinely prepare for the future, and who controls withdrawals.
An official Korea Development Institute account of the September 11, 2026, budget and fund forum records both the government's allocation plan and proposals for stronger parliamentary oversight, independent evaluation and saving only after exceptional revenue has been confirmed through final accounts. Those safeguards could determine whether the fund becomes a lasting fiscal buffer or another source of recurring spending.
What the government wants the fund to do
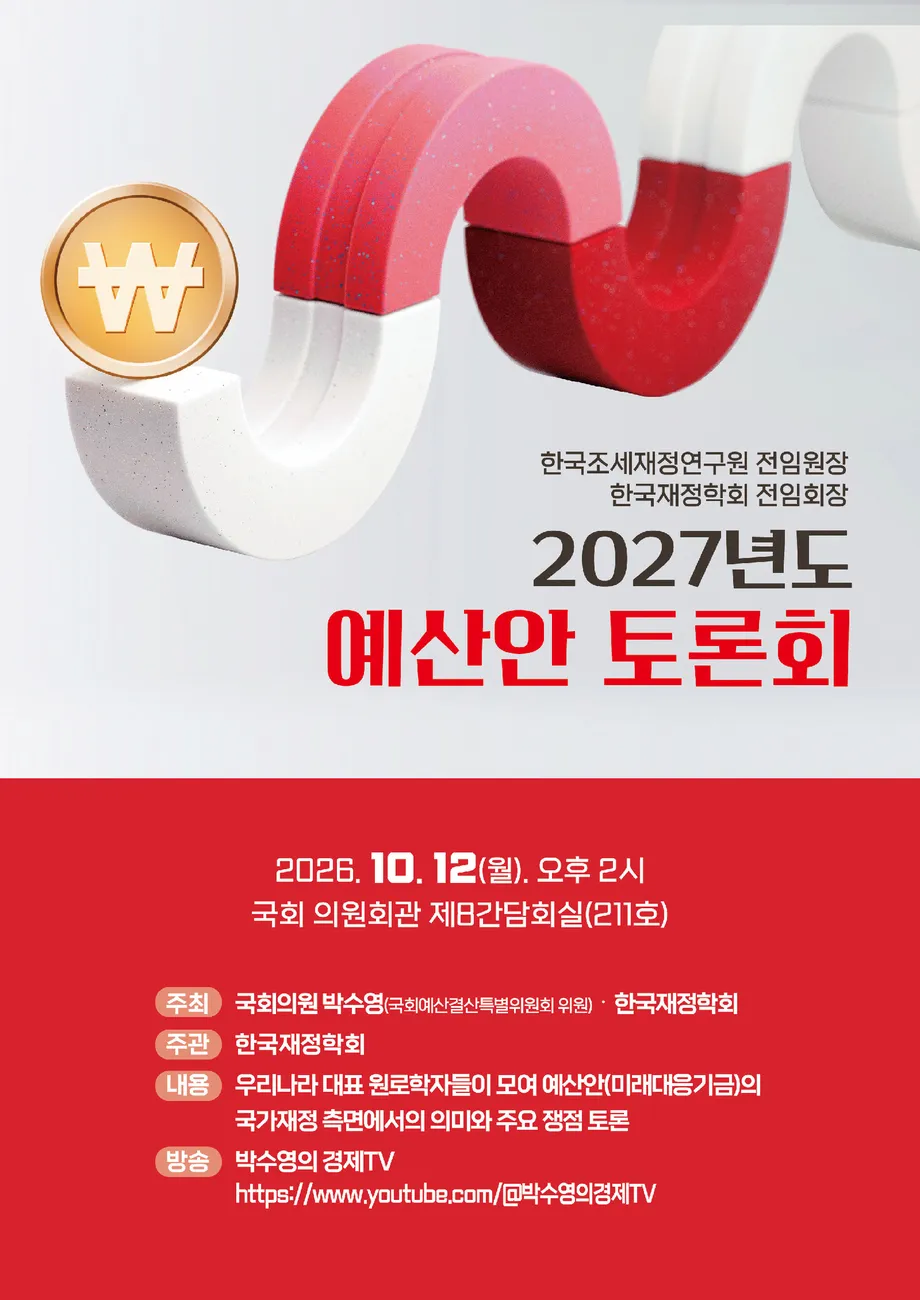
The Economic, Humanities and Social Research Council and KDI describe two functions in their official forum notice: strategic investment for the future and fiscal stabilization against tax revenue swings. Their September 11 event ran from 2 p.m. to 6 p.m. at the El Tower in Yangjae, Seoul. It was separate from the budget discussion planned by the Korean Association of Public Finance and People Power Party lawmaker Park Soo-young.
The Ministry of Planning and Budget's forum participation statement confirms that Vice Minister Cho Yong-beom attended to explain the 2027 budget and fund proposal. KDI's account says Cho argued that the budget would combine record spending with a lower national debt ratio. It does not supply a numerical debt ratio supporting that assessment.
At an October 8 parliamentary audit, Budget Minister Park Hong-geun described the fund's intended role:
The Future Fund is a strategic investment platform to bolster our growth potential. It is a stabilization mechanism to ensure stable and effective fiscal management.
The investment categories are youth, growth engines, regional development, and education and talent development. Some descriptions count education and talent separately, producing five areas rather than four. The underlying destinations are substantially the same. The government's definition of windfall revenue concerns receipts above their long term trend because of structural economic changes or large fluctuations, including an industrial supercycle.
Why some economists want a decade of saving
Yeom's proposal treats the fund as a resource for people living 30 to 50 years from now, including generations not yet born. He argues that youth, growth, regional and education programs should instead be financed through the ordinary budget. His concern is that uncertain additional revenue cannot safely support fixed annual obligations.
He would first accumulate resources for about a decade, then permit spending of a specified share. When the fund records a surplus, a proportion would repay government bonds; when it records a deficit, repayment would stop. No spending percentage or detailed withdrawal formula is specified in his proposal.
Yeom also advocates keeping national debt within 40% of gross domestic product. He reaches that proposed ceiling by starting with the European Union's 60% reference value and subtracting 10 percentage points for demographic welfare pressures and another 10 for possible reunification costs. This is his policy recommendation, not an established Korean legal limit or a demonstrated calculation of those future costs.
Former presidential economic affairs secretary Cho Won-dong agrees that debt repayment protects the choices available to future generations, but rejects a requirement to use every won of excess tax revenue that way. He supports advance investment in future growth while warning against using temporary semiconductor receipts to finance permanent benefits, including child allowances and rural basic income.
Saving while borrowing creates a separate cost question
Hwang's objection focuses on the government's balance sheet. The planned 104.4 trillion won reserve is close to the 106 trillion won in new bond issuance he identifies for the same year, a difference of 1.6 trillion won. He argues that borrowing less now and issuing bonds later if tax receipts weaken would avoid unnecessary interest costs.
Holding financial assets while carrying debt is not automatically a loss. The cost depends on the interest paid on borrowing, the return earned on reserve assets and the value of having cash available during a crisis. Hwang warns that the gap between borrowing costs and investment returns could produce losses. No quantified estimate of that gap accompanies his argument.
The government's 12.5 trillion won allocation for reducing new bond issuance also needs careful interpretation. Avoiding new borrowing lowers debt relative to what otherwise would have been issued; it is different from redeeming existing bonds. Yeom and Cho discuss repayment, while the government's published allocation describes reduced issuance.
Hwang nevertheless considers the proposed 12.8% increase in total expenditure acceptable in light of Korea's relatively low public spending compared with the OECD average. His position separates opposition to the fund's financing structure from opposition to fiscal expansion. He wants spending concentrated on low birth rates, aging and inequality, which he argues also affect the economy's capacity to grow.
Recurring projects could consume the buffer
Park Soo-young's office analyzed ministry project explanatory materials obtained on October 8. It identified 130 projects with 45.3862 trillion won in proposed spending, of which 122 projects worth 42.6199 trillion won would continue beyond 2028. Those figures place roughly 93.9% of the spending in continuing projects.
Within that group, 67 projects worth 27.2921 trillion won had no specified end date. That is about 60.1% of the analyzed spending. Ten direct cash or points support programs, totaling 798.36 billion won, were all classified as ongoing. They included assistance for employment, rent, marriage and children's savings.
The proposed Our Child Independence Fund illustrates how commitments could grow as eligible participants accumulate. Its initial 2027 budget is 146.5 billion won. Estimates cited by Park's office put annual government contributions at 700 billion won in 2031 and as much as 2.6 trillion won in 19 years. These are projections, not approved future appropriations.
There are discrepancies in the spending accounts. A parliamentary committee account uses 45.3625 trillion won, slightly below the 45.3862 trillion won in Park's analysis; the government's rounded figure is 45.4 trillion won. One account also describes projects ending in 2027 as 276.63 billion won, or 6.1% of spending. That amount is only about 0.6% of 45.3862 trillion won. Subtracting the continuing project total instead gives 2.7663 trillion won, about 6.1%. The discrepancy cannot be resolved without the underlying tables.
Which projects qualify as future investment?
Project descriptions have drawn criticism because some expenditures resemble ordinary operating costs or established benefit programs. Proposed items include 100 billion won in combined special allowances and incentives for public institution employees and roughly 5.7 billion won for ministerial residences. Separate accounts put the residence allocation at 5.67 billion won and 5.7 billion won, a small difference consistent with rounding.
A larger disagreement concerns the Rural Basic Income pilot. One account puts its 2027 allocation at 116.58 billion won, while another gives 1.1657 trillion won, approximately ten times as much. Both describe ministry project materials, but the difference is unexplained. It should not be treated as a settled budget figure.
The latter account describes monthly payments of 150,000 won in local vouchers for qualifying residents who have lived in designated areas for at least 30 days. It says the 2026 program covered 300,000 people at a cost of 331.8 billion won. The other account says project documentation allows consideration of a full program in 2027, despite classifying the pilot as a project lasting one year.
The Youth Culture and Arts Pass allocation is reported to rise from 36.1 billion won in 2026 to 792.5 billion won in 2027, nearly 22 times the earlier amount. Critics question whether these and other programs meet the fund's growth purpose. Parliamentary reviewers also identify possible overlap with employment insurance, housing, industrial and science funds, ordinary research spending and the Special Account for Balanced Regional Development.
How much control would parliament retain?
A National Assembly committee review of the proposed National Finance Act amendment, issued on October 4 under expert adviser Yoo In-kyu's name, warns that greater executive flexibility could reduce advance parliamentary control. Two provisions are central: wider authority to change fund spending and permission to cover tax shortfalls without a supplementary budget.
The amendment would allow adjustments of up to 30% within major spending categories without submitting a revised plan for prior Assembly approval, compared with 20% for ordinary project funds. Applying those percentages to the committee's 45.3625 trillion won spending figure gives approximately 13.6 trillion won and 9.1 trillion won, a difference of about 4.5 trillion won. These are illustrations of scale, not a claim that every expenditure could be freely redirected.
The proposal would also allow reserve transfers to the general account when revenue falls short without a supplementary budget. Current procedures require a supplementary budget and an amendment to the fund management plan. Reviewers warn that the change would move some control from approval before action toward scrutiny afterward. The government responds that such transfers would not increase total expenditure above the original plan.
A separate National Assembly Research Service assessment raises concerns about scrutiny of transfers and overlapping administrative responsibilities. Reviewers also identify unclear project selection criteria, differing definitions of excess revenue across the proposed laws and no explicit formula governing withdrawals when additional tax revenue is negative. Annual plans alone would not resolve these operating questions.
Local governments face a change in financial autonomy
The proposed arrangement would deduct money destined for the fund from domestic taxes before calculating local allocation tax. Interior Minister Yoon Ho-jung says the statutory allocation rate would remain 19.24%, but an unchanged rate applied to a smaller base can still yield less money than under the existing formula.
One account estimates the reduction against the existing calculation at 30.6 trillion won. The Narasallim Research Institute gives a different comparison for ordinary local allocation tax: 68.5 trillion won under the fund plan against 98.1 trillion won without the transfer, a gap of 29.6 trillion won. The estimates differ by 1 trillion won and use descriptions that are not fully identical.
The fund's proposed local account contains 15.3 trillion won, including 3.5 trillion won in discretionary local future growth support. The remainder would largely arrive through project budgets. Yoon says the government plans to cover project costs in full to avoid local matching contributions and is considering giving local governments the lead in policy design and decisions.
That does not make project funding equivalent to general revenue. Former Korean Association of Public Finance president Hyun Jin-kwon argues that the arrangement changes who decides how taxes are spent, moving discretion toward the center. Democratic Party lawmaker Lim Ho-seon has also called for a reliable mechanism to offset the allocation reduction. Yoon says total local allocations would nevertheless rise from about 63 trillion won in 2026 to around 70 trillion won in 2027. Growth from one year to the next and a reduction against an alternative formula can both occur.
A larger headline total is not money already saved
The often discussed 218.5 trillion won figure adds the 2027 fund plan of 162.3 trillion won to 56.2 trillion won in projected additional domestic tax receipts for 2026. It is an arithmetic combination, not a confirmed fund balance. Collections, transfer decisions and legislative approval would determine the actual resources.
The September 30 revenue revision put 2026 national tax receipts at 478.6 trillion won, 63.2 trillion won above the supplementary budget's 415.4 trillion won. Of that increase, 56.2 trillion won concerned domestic taxes. Democratic Party lawmaker Ahn Do-geol separately cited expected excess revenue of 88.4 trillion won at the October 8 audit. The benchmarks behind those different excess revenue figures are not reconciled, so they should not be substituted for one another.
Ahn supports the proposed allocation of approximately 64% for stabilization, 28% for investment and 8% for debt reduction. He argues that repaying all excess receipts could leave the government needing to borrow again during the next shortfall. He also says the range of national tax revenue growth fluctuations widened from 3.2 percentage points in 2011 to 2015 to 12.3 points in 2021 to 2025, about 3.8 times as much.
The reserve target has a useful, limited comparison: revenue shortfalls of 56.4 trillion won in 2023 and 30.8 trillion won in 2024 totaled 87.2 trillion won. The planned 104.4 trillion won reserve is about 1.2 times that sum. Its adequacy would still depend on future shocks, spending commitments and whether assets could be converted to cash without large losses.
What the design debate leaves unresolved
KDI fiscal and social policy research director Lee Tae-seok proposes confirming exceptional revenue through final accounts, meeting minimum liquidity needs first, and then adjusting debt risk reduction and prepared growth investment to fiscal conditions. The September forum also examined separating stabilization from investment, placing more resources with the Public Capital Management Fund and strengthening independent evaluation.
Ireland provides a concrete comparison for separating purposes. Its Future Ireland Fund has a baseline annual contribution of 0.8% of GDP from 2024 through 2035, with withdrawals barred before 2041. A separate fund supports spending during downturns. Korea's proposal places immediate projects and a reserve inside one mechanism, making withdrawal priorities especially consequential.
Bank of Korea Monetary Policy Board member Chang Yong-sung, speaking in a personal capacity, connects the design to inflation and monetary policy. He warns that semiconductor cycles are difficult to predict and that higher profits do not necessarily translate strongly into employment. He said:
If the fund is well-designed to contribute to long-term growth, it is expected to help the Bank of Korea by alleviating aggregate demand pressure.
The reported sequence shows how quickly the proposal reached detailed scrutiny:
- July 2026: President Lee Jae-myung introduced the fund concept.
- September 1: The 2027 budget proposal outlined the 162.3 trillion won plan.
- September 11: KDI and the research council held their budget and fund forum.
- September 30: The government revised its 2026 tax revenue estimate upward.
- October 4: A parliamentary review flagged oversight and sustainability concerns.
- October 8: Parliamentary audits examined the fund's purpose and project commitments.
The establishment law, related amendments and 2027 budget still require Assembly approval. No final vote date is specified. The unresolved choices include a reserve floor, rules for withdrawals during shortfalls, project selection standards and protection for local finances. Fitch Ratings has also warned that fiscal gains concentrated in a narrow range of sectors may be temporary, reinforcing the distinction between projected receipts and dependable resources.
Key Points
- The 2027 proposal allocates 162.3 trillion won across projects, reduced borrowing and reserves.
- Yeom Myeong-bae recommends about 10 years of saving before limited spending, prioritizing debt repayment.
- Park Soo-young's analysis places roughly 94% of project spending in programs continuing beyond 2028.
- Parliamentary reviewers question spending discretion, withdrawal rules and the durability of tax receipts.
- Local governments could receive more than in 2026 but less than under the existing allocation formula.
- The 218.5 trillion won headline is a possible combined amount, not an accumulated balance.
- Legislative approval and detailed operating safeguards remain unresolved.