P4.4 billion financial trail enters the impeachment case
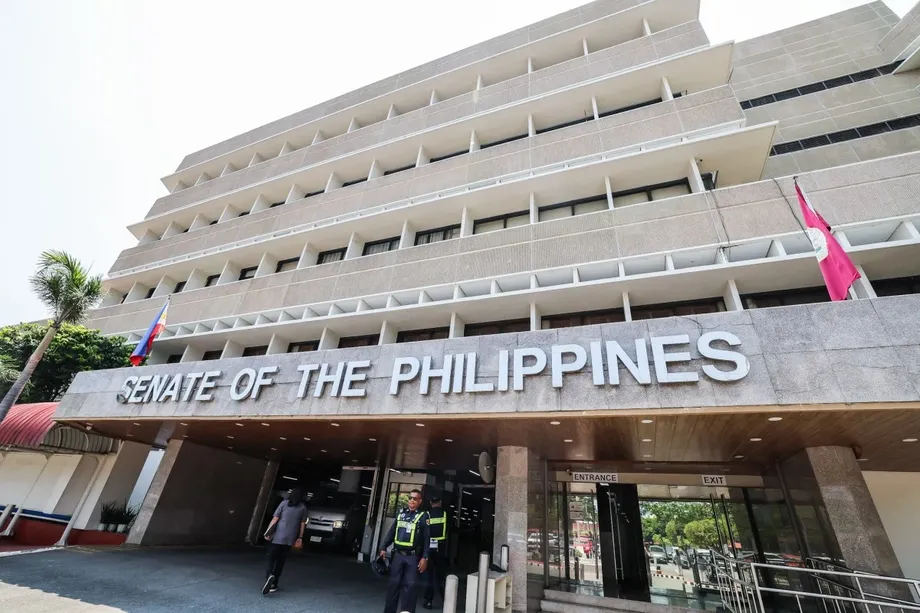
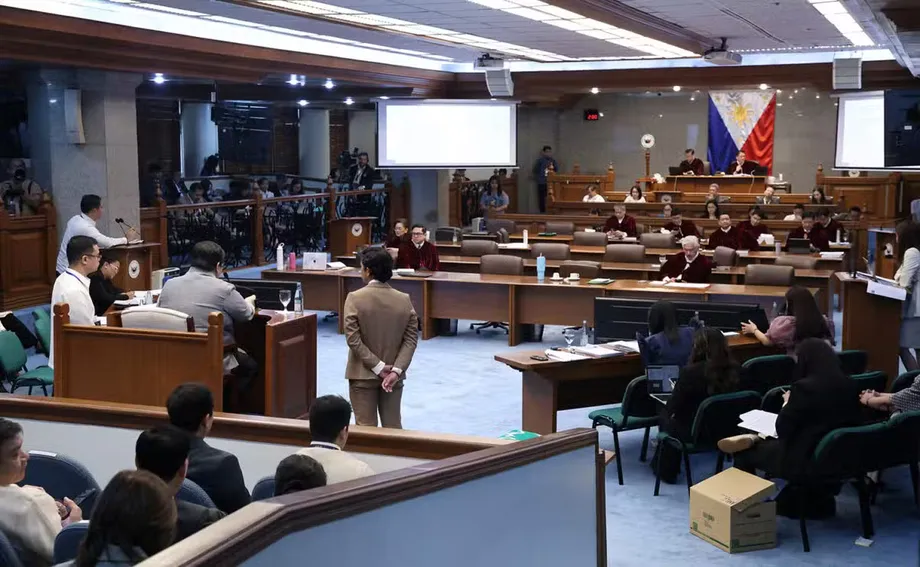
The Senate impeachment court allowed testimony on P4.4 billion in reported transactions involving Vice President Sara Duterte and her husband, lawyer Manases Carpio, opening a financial examination that now includes corrected bank reports, insurance purchases, corporate remittances and tax records.
Contents
- P4.4 billion financial trail enters the impeachment case
- Why the court permitted confidential records
- The bank correction behind the smaller total
- What covered and suspicious reports actually show
- Older accounts and the manager's check dispute
- Cash withdrawals and the declaration question
- Cale88 remittances and the China investigation
- Tax testimony adds income and ownership evidence
- Account balances and Carpio's response
- Timeline and decisions still pending
- Key Points
At the October 5, 2026 hearing, Day 33 of the trial, Anti-Money Laundering Council Secretariat Executive Director Ronel Buenaventura described records covering 2007 to 2025. The presentation cited 666 covered transaction reports and 55 suspicious transaction reports after overlapping records were removed.
The P4.4 billion is an aggregate of reported transactions, not a finding that the couple owned P4.4 billion, received that amount in income or held it at one time. It also is not an additional sum to be added to the individual transactions discussed in court. Transfers between accounts and repeated movements of the same funds can contribute to transaction totals without increasing wealth by the same amount.
The evidence forms part of Article II of the impeachment case, which alleges wealth disproportionate to lawful income and incomplete disclosure of assets, liabilities and net worth, including in Duterte's declarations for 2022, 2023 and 2024. Duterte has denied wrongdoing and described the allegations as politically motivated.
Subsequent hearings brought bank representatives and a Bureau of Internal Revenue official before the court. Their testimony supplied account balances, income figures and details of a disputed corporate share transfer, while also exposing limits in what the AMLC records alone can establish.
The central task is therefore more specific than comparing a large transaction total with a government salary: determining who owned or controlled the funds, where they came from, which assets remained at the relevant reporting dates and whether those assets were properly declared.
Why the court permitted confidential records
Defense lawyer Mark Vinluan sought to exclude Buenaventura's testimony under Section 8-A of the Anti-Money Laundering Act, arguing that confidentiality requirements contained no exception for impeachment proceedings.
Presiding officer Francis "Chiz" Escudero rejected the argument that the reports were entirely beyond the court's subpoena powers. He distinguished protection against unauthorized disclosure from compliance with a lawful court order.
Escudero explained the court's interpretation of the confidentiality provision:
The provision therefore regulates the manner and conditions of disclosure. It does not command absolute silence under every circumstance.
He limited testimony to relevant, subpoenaed records and said portions could be heard in a closed session if necessary. The defense retained the right to object to particular evidence. Escudero also rejected the contention that Buenaventura necessarily faced criminal liability for complying with the court's order.
The dispute extended to foreign currency accounts. Senator Imee Marcos argued that such accounts had been excluded in earlier impeachment proceedings. Escudero instead cited Republic v. Sandiganbayan and the 2012 Corona impeachment proceedings in support of allowing testimony about AMLC reports containing foreign currency transactions.
His ruling distinguished existing reports lawfully held by the AMLC from a new order compelling a bank to disclose a customer's foreign currency deposits. Senators Pia Cayetano and Imee Marcos nevertheless questioned whether the court was reading an impeachment exception into a law that did not expressly contain one.
The court also allowed AMLC documents to appear on the Senate livestream despite their confidentiality markings. That permission drew a separate defense objection about public exposure, making the scope of disclosure a contested issue alongside whether the records could be admitted at all.
The bank correction behind the smaller total
The P4.4 billion figure replaced an earlier estimate of roughly P6.7 billion presented to the House. Buenaventura attributed the change partly to corrected Bank of the Philippine Islands reports. He also identified differences in the coverage of the subpoenas and reporting institutions.
In an April 6, 2026 letter, BPI asked the AMLC to delete 13 covered transaction reports involving Carpio because a bug in a source application had produced inaccurate amounts. One readable entry originally recorded at about P269 million was corrected to P300,000. Other corrected amounts also fell below the P500,000 reporting threshold.
Buenaventura said the AMLC validated and accepted the correction before submitting its records to the impeachment court on July 30. The reported reduction from about P6.7 billion to P4.4 billion is approximately P2.3 billion, although the testimony did not attribute that entire difference solely to the software error.
Senator Tito Sotto questioned how a reporting glitch could turn amounts around P2 million into billions. Buenaventura said he could recall no correction of comparable size since taking office in April. Metrobank official Niña Aguilar said she had not encountered a similar error during her tenure. BPI witness Marwin Galvez, who appeared to explain account records rather than reporting technology, could not identify the bug's cause.
Duterte spokesperson Paolo Panelo argued that the correction demonstrated the danger of treating raw reporting data as verified evidence of wealth. The prosecution maintained that a substantial transaction total remained after the correction. Both positions make verification of the underlying entries central to the case.
What covered and suspicious reports actually show
A covered transaction report, or CTR, generally records a cash transaction exceeding P500,000 within one banking day under the rules described in the hearings. The reporting threshold does not itself establish wrongdoing. A suspicious transaction report, or STR, can be filed regardless of amount when an institution identifies specified warning signs.
The individual counts presented were 373 CTRs and 34 STRs involving Duterte, and 363 CTRs and 30 STRs involving Carpio. Seventy overlapping CTRs explain why the combined covered report count was 666 rather than 736. The individual STR counts add to 64, while the aggregate presentation cited 55. The reported testimony does not fully reconcile that separate difference.
Vinluan also challenged the decision to total the transactions. Buenaventura acknowledged that the court had not specifically instructed the AMLC to prepare aggregate amounts or tabular summaries. He said those summaries were prepared in connection with the July 21 subpoena and a September 29 request from House prosecutor Gerville Luistro.
Reports differ slightly on the allocation of the P4.4 billion. One account gives P1.63 billion in inflows, P1.3 billion in outflows and P1.4 billion with undetermined direction. Another gives P1.63 billion, P1.31 billion and P1.46 billion respectively, which sum to P4.4 billion. Buenaventura said incomplete or ambiguous sender and beneficiary information prevented reliable classification of some transactions, mostly from before 2014.
Banks and insurers cited allegations involving graft, drug trafficking and misuse of public funds in some STRs. These included insurance transactions in July and November 2019, a Philippine Savings Bank report dated August 1, 2024 and a BDO Life report dated December 5, 2024. Some relied on news coverage as a trigger for suspicion, not an established finding of criminal conduct.
Aguilar later described Metrobank's process as involving further checks and internal approval before submission. Buenaventura acknowledged that he had no personal knowledge establishing that Duterte had accumulated unexplained wealth. His testimony concerned the records held by the AMLC.
Older accounts and the manager's check dispute
BPI confirmed a joint Rodrigo and Sara Duterte time deposit opened on January 22, 2010 with P40.65 million. It was renewed 12 times and reached about P41.72 million. Bank testimony also identified three manager's checks for P41,721,035.62 each, dated April 19 and October 17, 2012, and October 7, 2013, payable to Rodrigo Duterte.
A manager's check is issued by a bank against funds it has received. Galvez explained that the money leaves the customer's account and moves to a bank settlement account while the check remains outstanding. It therefore does not appear in that customer's account balance at year end.
Prosecutors argued that this mechanism, alongside another approximately P55 million time deposit converted into a manager's check, could help establish concealment. Galvez said unused checks were not uncommon and declined to infer deliberate concealment.
Escudero noted that Sara Duterte's signature did not appear on the relevant documents for opening or closing the time deposit or purchasing the checks. Defense lawyer Michael Poa said she did not recall the account and had no participation in its transactions. Joint account ownership and responsibility for each transaction therefore remain separate matters for the court to assess.
The AMLC also identified seven transfers between accounts on March 28, 2014, totaling P193.70 million in one account of the proceedings and P193.71 million in another. Buenaventura said separate reference numbers identified distinct transfers within the same bank. Distinct entries, however, do not by themselves establish that each represented newly acquired money.
Other records included a P20 million BPI AIA life investment policy purchased on April 1, 2014 and a P16,852,782 manager's check dated May 30, 2016 payable to Samuel C. Uy. Separately, an AMLC information sharing report listed Duterte as beneficiary of P14.88 million in checks purchased in 2011 and 2012 by Samuel Cang Uy and two others.
Cash withdrawals and the declaration question
Buenaventura identified six transactions through which Carpio withdrew P41 million on August 6, 2024: P23 million from BDO and P18 million from Philippine National Bank. Records also showed Duterte transactions in December 2024 totaling P10.04 million: P2.371 million at Landbank on December 5, and P5.969 million at BDO plus a P1.7 million Metrobank check encashment on December 20.
Prosecutor Mae Divinagracia linked the withdrawals to testimony from Ombudsman records officer Karen Batu that the couple's joint statements of assets, liabilities and net worth did not declare cash on hand or in banks from 2019 to 2025.
That allegation requires attention to reporting dates. A withdrawal proves money moved on a particular day, but does not establish how much remained as cash, was spent or became another asset by December 31. The records described in court did not resolve the final use of all these withdrawals.
Later BIR testimony introduced a different set of documents. Audited financial statements reported cash on hand and in banks of P21.23 million at the end of 2022, P28.97 million in 2023, P15.53 million in 2024 and P13.80 million in 2025. Those figures do not automatically contradict testimony about omissions from SALNs because they concern different filings. They do make reconciliation between the filings necessary.
Cale88 remittances and the China investigation
Cale88 Foods Corp., a banana chips exporter linked to Carpio, received approximately P319 million in remittances involving China and Hong Kong, according to the testimony. Reports differ on the precise total and report counts: one gives P319.32 million through 141 CTRs and three STRs; another gives P319.33 million through 143 covered reports, comprising 141 involving mainland China and two involving Hong Kong.
Named counterparties included Jinhua Dongxi Trading Co., Ltd. and China National Township. Buenaventura confirmed that suspicious reporting cited an absence of an underlying legal or trade obligation, purpose or economic justification. That stated concern is not a judicial finding that every remittance was unlawful or that the money belonged personally to Duterte.
On October 11, President Ferdinand Marcos Jr. confirmed a government investigation into allegations raised by former senator Antonio Trillanes IV. Marcos said the Department of National Defense had responded because the allegations could involve national security.
Marcos described that concern conditionally:
The most disturbing aspect of it is the Chinese money. That now rises to a national security issue.
He also said authorities needed to establish the facts before reaching conclusions and denied involvement in an alleged campaign to discredit Duterte. The investigation had not established in the reported proceedings whether the remittances represented legitimate export payments, improper financing or another arrangement.
Tax testimony adds income and ownership evidence
On October 8, BIR official Anne Loraine Garcia-Marquez testified that Duterte and Carpio earned a combined P85.34 million, net of tax, from 2007 to 2025. Duterte's reported 2025 SALN declared P98.66 million in net worth, a numerical difference of P13.32 million. That comparison alone cannot determine unexplained wealth without establishing starting assets, liabilities and other lawful sources.
Escudero had separately compared P424 million moving through accounts during 2022 to 2025 with P336 million obtained by adding annual SALN figures. These are different measures: transaction totals measure movement, while net worth measures assets less liabilities at a particular date. Adding successive annual net worth declarations can also count the same retained assets repeatedly.
Garcia-Marquez confirmed that the BIR had authorized an audit of either Duterte or Carpio but declined to identify the subject. She also testified about legal practice registration, other income and Davao City compensation appearing in a 2023 tax filing. Prosecutors questioned whether these records indicated prohibited professional activity or another office, but the testimony did not settle the nature of each payment.
The BIR had no record of taxes paid on a transfer of Carpio's Cale88 shares and no application for an electronic Certificate Authorizing Registration, the tax clearance required before such a transfer is recorded in company books. Garcia-Marquez said the sale could remain valid between the parties even though it should not have been entered in the stock and transfer books. Escudero struck a prosecutor's description of the sale as fake.
Account balances and Carpio's response
Reports of subsequent bank testimony differ substantially on combined ending balances. One gives about P190 million across 30 active accounts at the end of 2025. Another gives P39 million across eight banks, with annual figures of P59 million in 2022, P71.3 million in 2023 and P22.2 million in 2024. The reported accounts do not establish a common scope that reconciles those totals.
BPI separately identified nine accounts with a combined P8 million ending balance in 2025 and 34 closed accounts, without specifying all closure dates. Corporate balances also require separation from personal holdings: GenCorp's reported balances fell from P50.75 million in 2022 to P14.50 million in 2025, while two Cale88 checking accounts closed in July 2026.
Insurance testimony identified a P10.6 million FWD investment insurance purchase by Carpio in 2024, with a reported financial value of P13.2 million and the couple's children as beneficiaries. Its value and disclosure treatment are distinct from bank balances and transaction turnover.
Responding to questioned credit card spending, Carpio said Japan travel expenses were initially paid for a group and later shared. He said sportswear purchases concerned senior basketball players and Kuala Lumpur spending related to a junior basketball team.
Carpio denied using public money:
There is nothing illegal about spending my own hard-earned money. No public funds were used for these personal expenses.
He also said Duterte was neither involved nor present. That response addresses the credit card expenses, rather than explaining every withdrawal, corporate remittance or disclosure issue raised in Article II.
Timeline and decisions still pending
The financial examination developed through several dates:
- April 6, 2026: BPI requested deletion of 13 erroneous covered reports.
- July 30: The AMLC submitted records incorporating validated corrections.
- October 5 and 6: Buenaventura testified and faced questions about totals, confidentiality and declarations.
- October 7: Bank representatives described joint accounts, checks and balances.
- October 8: Garcia-Marquez presented tax evidence and confirmed an audit authorization.
- October 11: Marcos confirmed an investigation into the alleged Chinese remittances.
The October 8 hearing anticipated continued BIR cross examination on October 9, followed by forensic analyst Alexander Cabrera. No outcome of that planned testimony is established here. A December 16 verdict date discussed during the trial was clarified as a logistical projection, not a guaranteed decision date.
Reports also differed on Article III, the bribery charge. One described prosecutors as no longer presenting it; Luistro said formal withdrawal had not yet been announced to the court. That distinction separates an intention from a completed procedural action. Article II still requires findings on ownership, lawful sources and disclosure, not simply acceptance of an aggregate number.
Key Points
- The P4.4 billion represents reported transaction activity, not established wealth or illegal income.
- BPI corrected 13 reports after a software error inflated amounts.
- The court allowed relevant AMLC testimony despite confidentiality objections.
- Suspicious reports record concerns, not proof that a crime occurred.
- Bank, tax and SALN figures require reconciliation, particularly where reported totals differ.
- Duterte denies wrongdoing; Carpio says questioned card spending used personal funds.
- No final finding on unexplained wealth or the corporate remittances is established by the described proceedings.