A Chip Stock Bet Turns Into a Market Crisis
South Korea is tightening controls on leveraged exchange traded funds tied to individual stocks after a sharp reversal in Samsung Electronics and SK Hynix shares inflicted heavy losses on retail investors. By August 5, 2026, authorities had raised entry requirements and were considering limits that could reserve these products for professional investors.
Contents
- A Chip Stock Bet Turns Into a Market Crisis
- How the Rally and Restrictions Unfolded
- Why Twice the Daily Return Can Produce Larger Losses
- Retail Losses and Forced Selling
- Officials Apologize as Lawmakers Demand Answers
- Higher Entry Requirements Already Affect Trading
- Emergency Powers Could Change Fund Leverage
- Losses Reach Banks as Investors Turn Overseas
- Concentration Adds to the Pressure on the Kospi
- Key Points
The funds were introduced in late May, offering twice the daily return of individual companies. Retail investors quickly poured 14 trillion won into them, compared with about 2 trillion won from foreign investors. That put retail investment at roughly seven times the foreign total, leaving individual traders heavily exposed when the rally reversed.
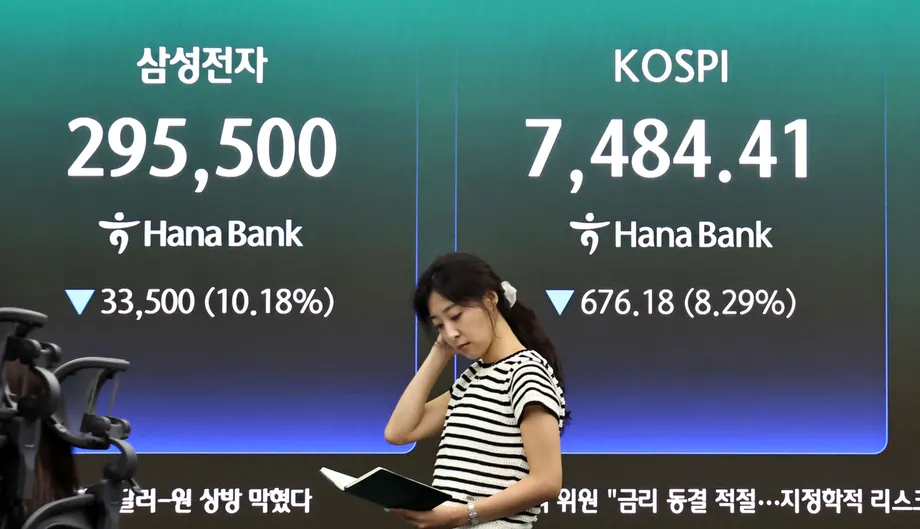
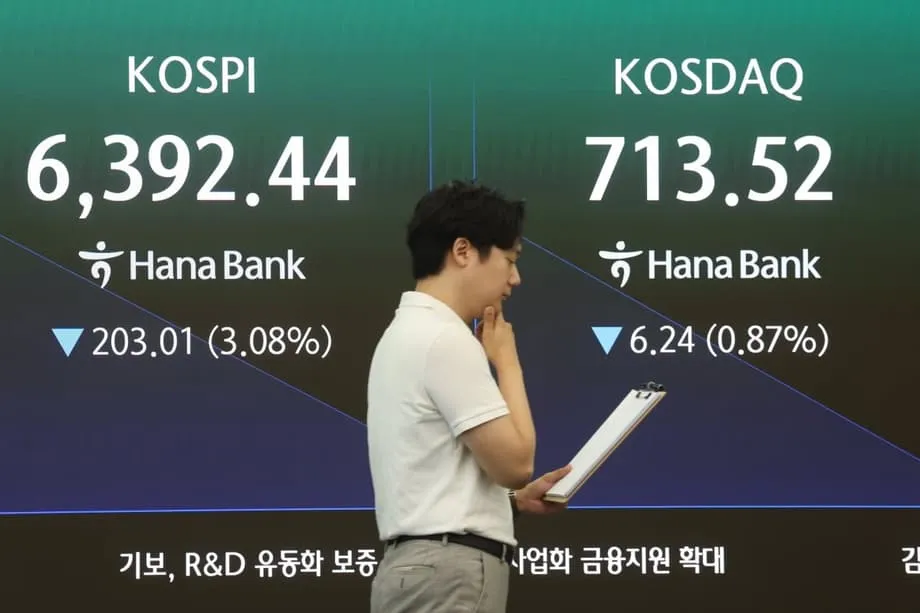
The Kospi index subsequently fell nearly 35 percent in a month as chip stocks retreated from record highs reached in June. Products targeting twice the daily movement in SK Hynix shares fell more than 80 percent from their June 23 peak. The equivalent Samsung Electronics product lost almost 75 percent from its June 3 high.
The damage has prompted apologies in parliament, questions about the speed of the launch and proposals to give regulators greater power to change how the funds operate during extreme volatility. The immediate response has focused on making the products harder to access. The larger debate concerns whether exposure of this kind should remain available to ordinary investors at all.
How the Rally and Restrictions Unfolded
The crisis developed over a little more than two months, from the launch of the products to tighter trading requirements. The main dates show how quickly enthusiasm for amplified chip stock returns gave way to losses and regulatory intervention.
- Late May: Single stock leveraged ETFs were introduced, including products linked to Samsung Electronics and SK Hynix.
- June 3: The Samsung Electronics leveraged product reached the high from which it later fell almost 75 percent.
- June 23: SK Hynix leveraged products reached the peak from which they later lost more than 80 percent.
- July 31: Higher minimum cash deposits and larger minimum trading units took effect simultaneously.
- August 5: Further restrictions and emergency regulatory powers remained under consideration, with implementation of additional measures expected in mid-August.
The June peaks matter because investors buying close to those levels entered just before the sharp decline. A fund designed to magnify a stock's daily gains also magnifies its daily losses, exposing those buyers to a much faster fall than they would have experienced holding the underlying shares.
Why Twice the Daily Return Can Produce Larger Losses
Conventional ETFs usually track a basket of shares, spreading exposure across several companies. These products instead use derivatives to magnify exposure to one company's share price. Derivatives are financial contracts used here to obtain the targeted exposure without simply buying an equivalent amount of ordinary shares.
The funds aim to deliver twice the underlying stock's return each day. Their leverage resets daily, so their performance over several days can differ sharply from twice the stock's return over that entire period. Each day's gain or loss changes the amount on which the next day's return is calculated.
A simple example explains the effect. A stock that rises 30 percent and then falls about 23.1 percent returns approximately to its starting price. Starting from 100, it rises to 130 and then falls back to roughly 100.
A fund providing twice those daily movements follows a different course. It rises 60 percent, taking the same starting value of 100 to 160. It then falls 46.2 percent, leaving about 86.1. The stock has returned approximately to where it began, while the leveraged investment has lost roughly 13.9 percent.
This compounding effect helps explain why holders lost far more than they expected once the rally reversed. A sequence of sharp rises and falls can erode the value of a product that resets its leverage every day, even when the underlying share eventually recovers its starting price.
Retail Losses and Forced Selling
Estimates put total retail losses on single stock leveraged ETFs at up to 56 trillion won. One investor reportedly lost more than 2.1 billion won on a position worth 5 billion won in an SK Hynix product. That loss amounted to more than 42 percent of the stated position.
Retail investors who bought near the June peaks also faced margin calls and forced liquidations. A margin call requires an investor using borrowed money to provide more cash or collateral when the value of the investment falls. If the investor cannot meet the demand, holdings may be sold to repay the borrowing.
Those sales added pressure to a market already falling. Daily leverage magnified the losses inside the funds, while borrowing created another source of pressure on investors who needed to raise cash quickly. Forced selling then contributed to further price declines.
Investor settlement deposits dropped by 21.21 trillion won in just over a month, signaling that less cash was available for further purchases. The decline reduced investors' capacity to add positions as prices fell.
The broader market experienced multiple circuit breakers and the activation of sidecar mechanisms that halted program trading. Circuit breakers interrupt trading during extreme market moves, while sidecar measures pause certain automated trading activity. In one session, the Kospi fell as much as 12.6 percent during trading before closing down 6 percent.
Officials Apologize as Lawmakers Demand Answers
Finance Minister and Deputy Prime Minister Koo Yun-cheol apologized during a parliamentary hearing and accepted responsibility after lawmakers criticized the rapid introduction of the products. Members of both the ruling party and the opposition questioned whether investor protection measures had been properly reviewed before listing.
Lawmakers also asked whether external pressure had influenced the launch. Their scrutiny extended beyond the losses themselves to the decisions that made concentrated, amplified exposure available to retail investors.
Financial Services Commission Chairman Lee Eog-weon expressed regret over the increased market volatility caused by the products. He told the National Assembly that regulators were considering restricting access to professional investors and lowering the leverage multiple from two times.
Lee, speaking about possible legislative changes, explained why a lower multiple was being considered:
Since the tracking multiple of two times is too large, lowering it would likely have an effect in terms of easing volatility.
Presidential policy chief Kim Yong-beom defended the original decision. He noted that retail investors actively trade many derivatives and that Samsung Electronics and SK Hynix account for a large share of the market. Critics rejected that explanation and continued to call for accountability.
Higher Entry Requirements Already Affect Trading
Authorities raised the minimum cash deposit needed to trade the products from 10 million won to 30 million won. They also increased the minimum trading unit from one share to 20 shares. Both changes took effect on July 31.
The deposit requirement tripled, while the minimum number of shares in a trade rose twentyfold. Together, the measures raised the amount an investor needs to commit before participating.
Trading volume in the affected products fell 75.5 percent on the first day the new deposit rules applied. Their share of total Kospi trading volume dropped to 6.4 percent, compared with an average of 33.8 percent during July. That was a decline of 27.4 percentage points in their share of market activity.
Further proposals include a cap limiting leveraged holdings to 20 percent of an individual investor's total portfolio. Authorities are also pursuing longer mandatory education programs and simulated trading exercises before participation.
The proposed portfolio limit would address how much of an investor's money is concentrated in leveraged products. The education and simulation requirements would give prospective traders more exposure to how those products behave before they commit real money.
Emergency Powers Could Change Fund Leverage
Regulators are drafting amendments that would allow authorities to reduce leverage directly during extreme volatility, bypassing meetings of fund beneficiaries. The changes could lower a fund's multiple from two times to 1.5 times or even one times.
At 1.5 times, a fund would target one and a half times its underlying stock's daily movement. At one times, the target would match that daily movement. Reducing the multiple would reduce the size of the daily gains and losses the product seeks to deliver.
The proposal draws on Hong Kong's flexible leverage framework. The South Korean approach would give regulators proactive intervention rights, rather than relying on fund managers to decide when to change the leverage.
Officials are also examining a variable leverage structure under which asset managers could adjust exposure between one and two times depending on market conditions. That would make the leverage level adjustable rather than fixed at twice the daily return.
Market participants have urged authorities to define emergency triggers, notification procedures and exit options for existing investors. Those details would tell holders when intervention can happen, how they will learn about it and what choices they have if a fund's investment target changes.
As of August 5, the additional rules and emergency powers were still being considered. Implementation of further measures was expected in mid-August, and analysts expected high volatility to continue until then.
Losses Reach Banks as Investors Turn Overseas
OK Savings Bank, South Korea's second largest savings bank, reported losses tied to holdings in the same leveraged products. The downturn therefore affected financial institutions as well as individual traders.
Some retail investors shifted activity to overseas markets as domestic restrictions tightened. Net purchases of United States stocks reached $4.67 billion in July, the largest monthly inflow since January.
The Direxion Daily Semiconductor Bull 3X Shares product alone attracted $3.77 billion in net buying from Korean investors. Its three times leverage target offered even greater daily exposure to semiconductor shares than the domestic products targeting twice the daily return.
The $3.77 billion directed into that product was about 81 percent of the $4.67 billion in net purchases of United States stocks during July. The figures show how heavily the overseas buying was concentrated in a leveraged semiconductor investment.
Overseas holdings also declined in value. The value of Korean retail investors' United States stock holdings fell by $33.7 billion between the end of May and the end of July despite net inflows. Moving money overseas left many investors exposed to further losses rather than ending their exposure to the semiconductor downturn.
Concentration Adds to the Pressure on the Kospi
Samsung Electronics and SK Hynix together account for nearly half the Kospi's market capitalization, the combined market value of its listed companies. Their size means that movements in two chipmakers carry considerable weight in the broader index.
The leveraged funds added concentrated exposure to companies that were already central to the market. When sentiment toward chip stocks shifted, the same sector was under pressure through ordinary shares, leveraged products and positions financed with borrowing.
Daily resets and margin borrowing helped accelerate both the rally and the decline. Rising prices encouraged amplified bets, while falling prices produced larger fund losses and forced sales. The heavy weighting of the two chipmakers made the correction more concentrated in one industry.
The episode has also revived longer term discussion of the Korea Discount, the valuation gap affecting South Korean shares. Those discussions include corporate governance improvements and greater industrial diversification to reduce dependence on a single industry.
The immediate regulatory response focuses on access, position sizes and the amount of leverage funds can use. The wider debate concerns the concentration of the market itself, alongside the standards under which companies are governed.
Key Points
- Single stock leveraged ETFs launched in late May attracted 14 trillion won from retail investors and about 2 trillion won from foreign investors.
- The Kospi fell nearly 35 percent in a month. SK Hynix leveraged products lost more than 80 percent from their June 23 peak, while the Samsung Electronics equivalent fell almost 75 percent from its June 3 high.
- Estimated retail losses reached up to 56 trillion won, with daily resets, margin calls and forced selling magnifying the damage.
- Koo Yun-cheol apologized in parliament, while Lee Eog-weon outlined possible restrictions on access and lower leverage.
- Minimum deposits rose to 30 million won and minimum trading units to 20 shares on July 31. Trading volume fell 75.5 percent on the first day.
- A proposed 20 percent portfolio cap, longer education requirements and simulated trading would add further restrictions.
- Draft amendments would allow regulators to reduce leverage during extreme volatility without beneficiary meetings. Additional measures were expected in mid-August.
- Korean investors bought a net $4.67 billion of United States stocks in July, including $3.77 billion in Direxion Daily Semiconductor Bull 3X Shares.