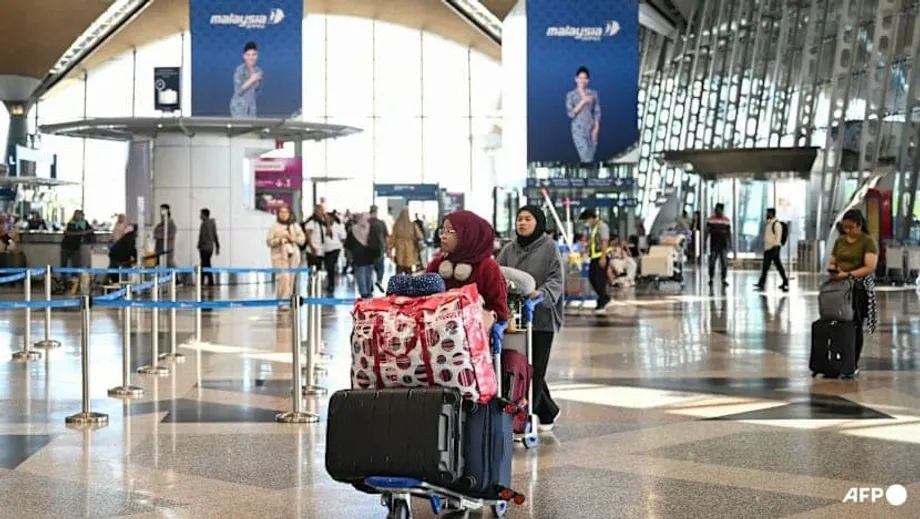
Thousands of Flights Lost as Gulf Hubs Struggle
More than 5,000 flights were cancelled in the first 48 hours after the United States and Israel began their military campaign against Iran on February 28. By March 17, 2026, the disruption had spread far beyond the Middle East, raising airfares, stranding travelers and threatening tourism income across Asia. Malaysia, meanwhile, was seeking a larger role as an alternative aviation hub.
Contents
- Thousands of Flights Lost as Gulf Hubs Struggle
- Reopened Airspace Still Means Limited Flights
- Tourism Losses Meet Rising Fuel Costs
- Factories Also Face Supply Disruption
- Why Malaysia Has Some Protection
- Thailand, Bali and Cambodia Face Greater Exposure
- Malaysia Seeks a Larger Role in Transit Travel
- Airline Shares Fall While Energy Stocks Gain
- Recovery Depends on Safety, Prices and Timing
- The Essentials
Dubai, Abu Dhabi and Doha, major connecting points between Europe and Asia, have faced severe operating restrictions or complete closures as Iranian missile and drone attacks threaten civilian airspace. The crisis has exposed how much international travel depends on a small number of very large airports: when those connecting points stop working, passengers thousands of kilometres away lose access to their destinations.
The European Union Aviation Safety Agency has banned European operators from flying over the region, including Saudi Arabia and Oman. Airlines have been forced to fly north over the Caucasus or west over East Africa, adding hours to journeys between Europe and Asia. European safety restrictions also prevent aircraft leased from European operators from using contested airspace, complicating operations for airlines elsewhere.
Indian budget airline IndiGo faces journeys from Mumbai to England that can take up to two hours longer because aircraft must travel over East Africa instead of the Arabian Peninsula. Longer flights burn more fuel and increase crew costs, putting further pressure on fares.
The main developments have unfolded across several dates:
- February 28: The United States and Israel began their military campaign against Iran.
- The first 48 hours: More than 5,000 flights were cancelled.
- The first week: Luxury travel firm Lightfoot Travel recorded a 50% fall in total bookings.
- Eleven days into the conflict: The United Arab Emirates partially reopened its airspace, although airline schedules remained sharply reduced.
- March 17: Disruption continued, with some airline suspensions extending into late March.
Reopened Airspace Still Means Limited Flights
Emirates was operating less than 60% of its usual schedule after the partial reopening of UAE airspace. Qatar Airways and Etihad Airways were operating just 11% and 17%, respectively. An airport reopening therefore offered only limited relief to passengers trying to reach home or continue their holidays.
Tens of thousands of travelers were stranded. Some made road journeys through the desert to Muscat to find alternative flights. Lightfoot Travel's reservations for Middle Eastern destinations disappeared almost overnight, alongside its 50% fall in total bookings during the first week of fighting.
Dubai continued to face immediate safety threats. Iranian drones forced arriving aircraft into extended holding patterns, meaning they had to circle while waiting for permission to land. In one incident, unmanned aerial vehicles fell near Dubai International Airport and injured four people. The airport is the world's second busiest hub for international passengers.
British Airways suspended Middle East services until late March and cancelled Abu Dhabi flights indefinitely. KLM halted Dubai operations through March 28. Airlines resuming some services still faced decisions about whether aircraft could safely enter, land in and depart from affected airspace.
The uncertainty has changed both routes and booking decisions. Travelers who would normally connect through a Gulf airport have sought alternatives, while those planning holidays in the Middle East have pulled back. Connecting passengers and holidaymakers consequently face different recovery prospects: a restored flight network can bring transit passengers back, while a destination also needs visitors to feel comfortable spending time there.
Tourism Losses Meet Rising Fuel Costs
The World Travel and Tourism Council estimates that international visitor spending in the Middle East has fallen by at least $600 million a day since the conflict began. Hourly losses were also estimated at approximately $20 million. Hotels, restaurants, shops and tourism businesses are losing income alongside airlines.
Oxford Economics projects that international arrivals to the Middle East could fall between 11% and 27% in 2026 compared with the previous year, depending on how long the conflict lasts. Its estimates translate into 23 million to 38 million fewer international visitors and lost spending of $34 billion to $56 billion.
Brent crude has risen to approximately $90 a barrel, about 50% above its level at the start of 2026. Jet fuel costs have effectively doubled for many airlines. Carriers face a combined squeeze: they are paying more for fuel while using more of it on longer routes.
Airlines are passing those costs to passengers through fuel surcharges and higher base fares. Thai Airways has announced price increases of 10% to 15%, citing overwhelming demand and rising fuel costs. Sustained increases could discourage discretionary travel, especially holidays that households can postpone.
The Strait of Hormuz has also experienced severe shipping disruption. It handles roughly one fifth of global seaborne oil and liquefied natural gas supplies, making interrupted shipping a major concern for energy buyers far from the fighting.
Across Asia, around 80% of oil imports transit through the strait. Higher energy costs can push prices up while slowing economic activity, a combination known as stagflationary pressure. Pacific island economies face particular strain because energy imports alone account for 5% to 15% of gross domestic product, while international tourism supports substantial employment and income. Gross domestic product, or GDP, measures the value of goods and services produced in an economy.
Factories Also Face Supply Disruption
Qatar, the world's second largest helium producer, supplies approximately one third of global demand. Production at its Ras Laffan facility stopped following suspected Iranian strikes, creating a threat to manufacturers that depend on the gas.
Semiconductor industries in Taiwan, South Korea and Japan use helium in chip manufacturing. A disruption to this supply therefore reaches beyond airlines and tourism into the production of electronic components.
Petrochemical disruption creates another pressure point. Plastics and resins made from these materials are used in electronics packaging. The Philippines is particularly exposed because electronics account for more than half of its exports.
Asian economies are consequently facing several connected pressures: more expensive energy, interrupted industrial supplies and weaker access for international visitors. For countries and businesses exposed to more than one of these areas, the costs can arrive together.
Why Malaysia Has Some Protection
European visitors account for less than 15% of Malaysia's total tourist arrivals, limiting its direct exposure to disrupted routes serving Europe. Demand from East Asia, India and other Southeast Asian countries is expected to cushion potential losses, giving Malaysia a broader mix of visitors than destinations more dependent on distant markets.
Approximately 200 outbound flights from Kuala Lumpur International Airport to Middle Eastern destinations have nevertheless been cancelled since the war began. Malaysia is affected by the same aviation disruption, even as tourism leaders remain optimistic about reaching the country's target of 45 million tourist arrivals in 2026.
Nigel Wong, president of the Malaysian Association of Tour and Travel Agents, described the country's position as favourable because of its location and aviation connections:
We are in a sweet spot at the moment, very much like Singapore. Malaysia is very strategically positioned in terms of being a hub for air travel.
Malaysia also has a reputation as a safe and welcoming destination for Muslim travelers. Visitors from the Middle East form a valuable niche market because they typically stay longer and spend more on family holidays, shopping and medical tourism.
Those strengths support confidence among Gulf visitors, including families traveling during summer holidays and school breaks. Malaysia's halal tourism credentials, meaning services suited to Muslim travelers, form part of that appeal.
The Visit Malaysia 2026 campaign has launched promotional initiatives and upgraded facilities. Direct international routes are expanding to Kuala Lumpur and to secondary destinations such as Penang and Kota Kinabalu, particularly from Chinese markets. More direct services spread tourism activity beyond the capital and reduce reliance on a single entry point.
The ringgit has appreciated approximately 10% against the US dollar over the past year, yet Malaysia remains competitively priced compared with regional peers. Wong cautioned against complacency: heritage conservation, improvements to urban amenities and other infrastructure work need to continue despite external pressure. The campaign's strong initial momentum needs continued investment to support later demand.
Thailand, Bali and Cambodia Face Greater Exposure
Thailand and Indonesia, particularly Bali, face greater risks from prolonged disruption because of their dependence on tourism from distant markets. Tourism accounts for approximately 12% of Thailand's GDP and 9.4% of Cambodia's, making flight access an important part of their economic performance.
European visitors travel in large numbers to Bali, Phuket and Bangkok, with many journeys relying on connections through Dubai, Doha or Abu Dhabi. Losing access to those airports interrupts travel even when the destination itself remains open.
Aviation analyst Brendan Sobie identified Bali and Cambodia as especially exposed because travelers from Europe have no direct flight options to those destinations. They depend on connecting services, allowing disruption at a transit airport to spread into hotel bookings and local tourism income.
The Thai Hotels Association warns that Thailand could lose more than 40 billion baht in tourism revenue under a worst case involving eight weeks of airspace closure. Thailand's tourism ministry has modelled three revenue scenarios. Its eight week closure scenario projects nearly 600,000 fewer foreign arrivals and losses of approximately 40.9 billion baht.
A closure lasting four weeks could mean 334,000 fewer arrivals and 21.5 billion baht in lost revenue. The ministry also identifies inflation in Europe as a separate pressure on visitors' spending power, even when flights are available.
Thai travel agents say markets requiring long flights supplied 10 million visitors in 2025 and could suffer declines of 50% this year. A fall of that size would mean about 5 million fewer visitors from those markets.
Weekly arrival figures from early March showed an immediate 18% decline in European and Middle Eastern markets after the conflict escalated. Arrivals fell substantially among German, Russian, British, French and Israeli travelers. The Association of Thai Travel Agents forecasts declines of up to 50% for the full year if conditions persist.
Malaysia's smaller European share gives it some protection from this particular disruption. Thailand, Bali and Cambodia face a more direct connection between the availability of Gulf transit flights and the number of visitors able to reach their hotels and attractions.
Malaysia Seeks a Larger Role in Transit Travel
Malaysia, Thailand, Singapore and Hong Kong could attract travelers looking for alternatives to Middle Eastern stopovers. Capturing that traffic requires reliable operations and sustained investment in aviation infrastructure, as well as flights that connect passengers to their final destinations.
Norazman Mahmud, chief executive of the Civil Aviation Authority of Malaysia, said the disruption presented an opportunity for the region to provide a more stable route to Europe:
What is happening in the Middle East is a good opportunity for our region to become the next hub, a safer, more stable hub to get to Europe rather than stopping in the Middle East.
Malaysia Airlines has announced plans to increase frequencies to European destinations, including additional London and Paris flights. The expansion responds to demand for direct connections that avoid potential conflict zones and forms part of broader improvements intended to strengthen Malaysia's competitiveness as an alternative hub.
Direct travel connects the departure city with the destination without a change of aircraft. The Gulf model commonly brings passengers from many cities to one hub, then sends them onward. The current disruption has encouraged more interest in direct routes, although connecting networks still provide access to many destinations that cannot support direct services.
United Airlines has recorded a striking shift on another alternative: the Southern Cross Route, linking Australia and New Zealand with Europe through the United States. It reported booking more than 1,000 passengers a day on those journeys during the week, compared with fewer than one a day last year.
The route dates to the middle of the 20th century and uses American cities such as Los Angeles and San Francisco. It avoids both Middle Eastern and Russian airspace restrictions, offering another way to complete journeys that normally pass through Gulf hubs.
Longer flying times and the need to adjust capacity will keep fares elevated in the near term. Southeast Asian aviation centres could gain lasting economic benefits if some transit passengers continue using alternative routes after the immediate disruption ends. Malaysia's chance depends on converting interest into dependable connections.
Airline Shares Fall While Energy Stocks Gain
AirAsia X shares have fallen 28% since hostilities began, reaching their lowest level since September 2025. The decline triggered automatic trading suspensions and reflected concern about the airline's sensitivity to jet fuel prices.
Analysts estimate that every one dollar increase in jet fuel costs could reduce AirAsia X's bottom line by approximately 80 million ringgit, equivalent to 5.3% of earnings. Singapore Airlines shares fell nearly 7%, while Cathay Pacific declined 8%.
Malaysia's energy sector moved in the opposite direction. The Bursa Malaysia Energy Index climbed more than 4% in the immediate aftermath of the conflict, as rising Brent prices improved earnings prospects for companies producing oil and gas.
PETRONAS reported a 21% decline in core earnings for the 2025 financial year compared with the previous year because of lower realised energy prices. The current geopolitical risk premium, the extra price associated with fears of disrupted supply, therefore matters for the national finances as well as corporate earnings.
Dialog Group, Hibiscus Petroleum and Dagang NeXchange have attracted greater investor interest because of their exposure to higher realised energy prices. The same increase that raises airline costs can improve revenue prospects elsewhere in the economy.
Malaysian banks and real estate investment trusts have shown defensive characteristics during the uncertainty. Financial institutions maintain Common Equity Tier 1 ratios of 14.5%, providing substantial capital buffers. This ratio measures a bank's core capital against assets adjusted for their risk, helping indicate its capacity to absorb losses.
Analysts favour banks focused on the domestic market and utilities such as Tenaga Nasional because of relatively predictable earnings and limited direct exposure to Middle Eastern volatility. Research houses also suggest that Chinese and Indian travelers who had planned Middle Eastern holidays may choose Malaysia instead. That redirected demand could offset some weakness in Western arrivals and support the domestic tourism sector.
Recovery Depends on Safety, Prices and Timing
Oxford Economics' scenarios show how strongly the length of the conflict affects tourism losses. An early resolution within one to three weeks could limit the annual decline in Middle Eastern arrivals to 11%. Fighting lasting months could push the loss to 27%.
The World Travel and Tourism Council remains optimistic about the possibility of a rapid recovery. Gloria Guevara of the council has pointed to historical patterns in which tourism rebounds quickly after security incidents, sometimes in as little as two months when governments and the industry work together to restore confidence.
Lightfoot Travel's Lucy Jackson Walsh expects the possibility of a burst of travel after the conflict ends, similar to the release of delayed demand following the pandemic. Travelers who postpone holidays during the fighting may book again once they feel safe.
Aviation consultant Jonathan Hinkles expects Gulf transit traffic to recover quickly because of competitive prices and extensive connections. Leisure tourism to Middle Eastern destinations could need a longer period to recover. The recovery outlook ranges from roughly two months to two years, reflecting different prospects for transit traffic and destination tourism.
Travelers value the ability to reach destinations around the world with one stop. Gulf hubs retain that attraction, creating strong reasons for passengers to return when safety stabilises. Southeast Asian alternatives must therefore compete on connectivity and price as well as stability.
Malaysia's tourism authorities stress the need to maintain infrastructure investment and promotional momentum. Its Muslim tourism appeal, expanding direct flight network and political neutrality could help the country emerge stronger, provided the conflict does not extend into the peak European travel season between April and August.
No firm date for normal aviation operations or a complete tourism recovery has been given. March 28 remains a stated deadline for KLM's Dubai suspension, while British Airways' broader Middle East suspension extends into late March and its Abu Dhabi cancellations remain indefinite.
Malaysia's immediate advantage is a diversified visitor base. Its longer opportunity lies in building the routes and facilities needed to serve passengers seeking alternatives. Both remain subject to the same pressures affecting the wider region: expensive fuel, reduced capacity and uncertainty over how long the conflict will last.
The Essentials
- More than 5,000 flights were cancelled in the first 48 hours after the military campaign began on February 28.
- Dubai, Doha and Abu Dhabi remain central points of disruption, with sharply reduced airline schedules despite some reopening.
- The World Travel and Tourism Council estimates at least $600 million in lost Middle Eastern visitor spending each day.
- Oxford Economics projects 11% to 27% fewer Middle Eastern arrivals in 2026, with spending losses of $34 billion to $56 billion.
- European visitors make up less than 15% of Malaysia's arrivals; approximately 200 outbound flights from Kuala Lumpur to the Middle East have been cancelled.
- Malaysia retains a target of 45 million tourist arrivals in 2026 and is seeking more transit traffic through expanded European connections.
- Thailand's scenario involving eight weeks of airspace closure projects nearly 600,000 fewer arrivals and losses of 40.9 billion baht.
- Jet fuel costs have effectively doubled for many carriers, while Thai Airways has announced fare increases of 10% to 15%.
- AirAsia X shares have fallen 28%, while Malaysia's energy index rose more than 4% in the immediate aftermath.
- Recovery prospects range from about two months to two years, with Gulf transit traffic expected to return faster than leisure tourism to affected destinations.