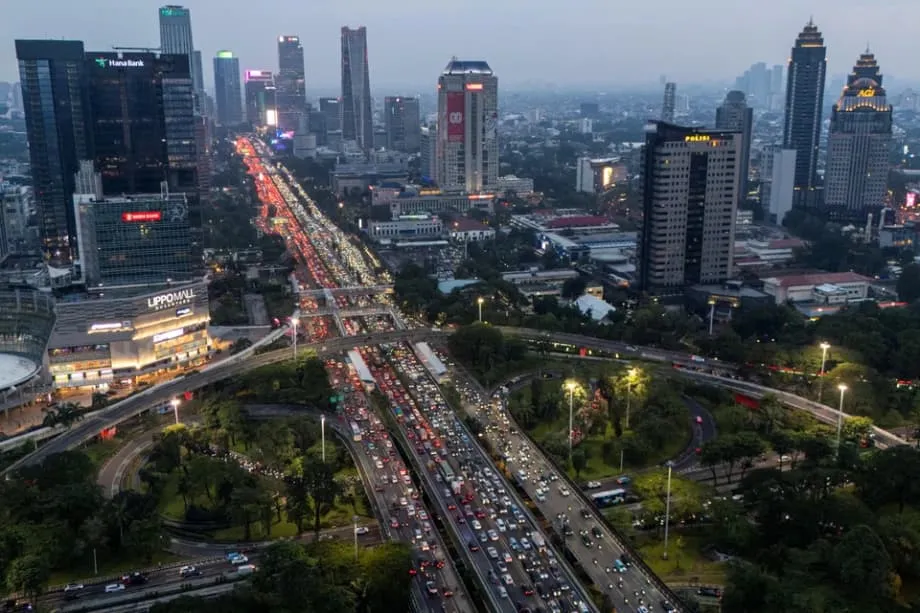
A Selloff That Reaches Beyond Share Prices
Indonesia has lost approximately $120 billion in equity market value since late January 2026, after global index provider MSCI warned that concerns about transparency and share ownership could push Southeast Asia's largest economy from emerging market to frontier market status. As of February 27, the pressure extends across stocks, the rupiah, government borrowing and confidence in the institutions managing the economy.
Contents
- A Selloff That Reaches Beyond Share Prices
- Why MSCI and FTSE Russell Have Put Changes on Hold
- Who Really Owns the Shares Available to Trade?
- A Timeline of Mounting Pressure
- Central Bank Leadership Adds to Currency Concerns
- Spending Plans Put Predictability Under Scrutiny
- Malaysia Offers a Regional Alternative
- Resignations, Arrests and a State Investment Response
- Yuan Borrowing Expands the Financing Options
- Strong Public Support Meets Weak Market Confidence
- What to Know
The Jakarta Composite Index (JCI) fell 4.73% in the first week of February alone, erasing roughly Rp 705 trillion ($41.6 billion) in market capitalization. The wider crisis has brought trading halts not seen since the 1998 Asian Financial Crisis and Indonesia's most severe market credibility shock in decades. Market capitalization is the combined value of listed shares at their current prices, so falling prices can erase large amounts of that value without an equivalent amount of cash leaving the country.
MSCI's warning has exposed a breakdown in trust between international investors and Indonesian regulators. Investors need to know who owns shares, how many are genuinely available to trade and whether prices reflect ordinary buying and selling. Uncertainty about those basic questions has become a threat to Indonesia's place in global investment portfolios.
Moody's Ratings added to the pressure on February 5 by changing Indonesia's sovereign credit outlook to negative, citing less predictable policymaking and governance concerns. Finance Minister Purbaya Yudhi Sadewa has described the volatility as a temporary market shock rather than fundamental weakness, but his reassurance has failed to stop capital flight.
Foreign investors had already withdrawn $1 billion from Indonesian equities in 2025 and accelerated their exit as the crisis unfolded. The challenge now combines technical problems in the stock market with broader doubts about how economic decisions are made.
Why MSCI and FTSE Russell Have Put Changes on Hold
MSCI immediately froze all increases in foreign inclusion factors and suspended new stock additions to the MSCI Investable Market Index. A foreign inclusion factor helps determine how much of a company's shares can count toward an index used by international investors. Freezing increases restricts the scope for affected shares to receive a larger place in those portfolios.
FTSE Russell followed by postponing its March 2026 index rebalancing until May 22, 2026. Rebalancing is the scheduled adjustment of which stocks an index contains and how much weight each receives. Together, the two providers' decisions have halted opportunities for Indonesian equities to gain a greater allocation in global passive investment portfolios.
Passive funds follow an index instead of selecting every investment independently. Changes to an index can therefore influence where billions of dollars go. Indonesia's possible reclassification matters because funds built to hold emerging market assets would face a different investment framework if the country moved into the frontier category.
Analysts estimate that a frontier market reclassification could trigger foreign fund outflows of $25 billion to $50 billion. MSCI has warned that Indonesia risks such a change by May 2026 if transparency problems persist. The decision remains unresolved, leaving authorities a limited period to address the concerns behind the warning.
Who Really Owns the Shares Available to Trade?
Free float transparency sits at the center of the dispute. Free float is the share of a company available for public trading, excluding holdings kept by strategic investors, governments or company insiders. MSCI and FTSE Russell use this information to calculate how much of a stock belongs in their indices.
MSCI's consultation with international investors revealed declining confidence in information maintained by the Indonesian Central Securities Depository (KSEI) and the Indonesia Stock Exchange (IDX). Investors raised persistent concerns about shareholder categories and suspected coordinated trading that could distort how prices are formed.
Opaque ownership makes it harder to judge both liquidity and investment value. Liquidity describes how readily shares can be bought or sold. A company may have many shares on paper, but investors need a reliable account of how many circulate freely and whether apparently separate holders act together.
Indonesia currently requires a minimum free float of 7.5% for listed companies. Malaysia's threshold is 25%, comparable to developed markets such as Hong Kong. Put simply, Indonesia's minimum allows 7.5 out of every 100 shares to be available for public trading, against 25 in Malaysia. That difference helps explain why concentrated ownership has become a central concern.
Indonesian authorities have pledged to double the minimum to 15% and tighten ownership disclosure to a 1% threshold, with full implementation expected by March 2026. The IDX has begun publishing monthly free float reports and using more detailed investor classification categories. These measures aim to give investors a clearer view of ownership, although skepticism remains about whether the changes will endure beyond the immediate crisis.
A Timeline of Mounting Pressure
Indonesia's market problems developed alongside changes in borrowing, monetary leadership and public opinion. The key dates show how several pressures accumulated within a few weeks.
- October 2025: Indonesia made its debut offshore yuan bond sale, raising six billion yuan.
- November 2025: President Prabowo Subianto's approval rating stood at 78%.
- December 2025: Foreign inflows into bonds denominated in Malaysian ringgit reached RM3 billion.
- January 15-21, 2026: Indikator Politik Indonesia conducted a survey that put Prabowo's approval at 79.9%.
- January 2026: Thomas Djiwandono, Prabowo's nephew, was appointed deputy governor of Bank Indonesia. Indonesia also recorded a rare January budget shortfall as spending accelerated.
- Late January 2026: MSCI's warning triggered the market collapse and the start of losses totaling approximately $120 billion.
- First week of February 2026: The JCI fell 4.73%, losing roughly Rp 705 trillion ($41.6 billion) in market value.
- February 5, 2026: Moody's changed Indonesia's sovereign credit outlook to negative.
- February 25, 2026: Indonesia began marketing its second offshore yuan bond in four months.
- March 2026: Authorities expect full implementation of the proposed free float and ownership disclosure reforms.
- May 2026: Indonesia faces the risk of MSCI reclassification. FTSE Russell has postponed its March index rebalancing until May 22.
The poll preceded the MSCI warning, while the borrowing initiative came after the stock market shock and Moody's decision. Those dates place the government's strong public support and its financing response at different stages of the crisis.
Central Bank Leadership Adds to Currency Concerns
Prabowo's appointment of Thomas Djiwandono as deputy governor of Bank Indonesia has sharpened investor worries about central bank independence and nepotism. Djiwandono defended his selection as based on merit despite his family connection to the president.
The rupiah fell to a record low of 16,985 per US dollar immediately after Djiwandono's nomination. The appointment and Moody's negative outlook came during the same period, compounding doubts about monetary and fiscal institutions. The currency has also been trading near historic lows around 16,825 per dollar, with analysts warning that a move beyond 17,000 would take it into uncharted territory.
Central bank independence matters to investors because monetary decisions affect inflation, interest rates and the currency. Concern about political influence can make it harder to anticipate how the bank will respond when government spending needs and price stability pull in different directions.
Fauzan Luthsa, an adviser at Ormit Kelola Nusantara in Jakarta, described the difficulty of assessing risks when policy changes repeatedly:
Ad-hoc policy doesn't protect the market, it makes the impossible to price. The biggest risk is a pattern of policy that is reactive and constantly changing.
Prabowo's administration has unsettled investors through decisions viewed as improvised economic management. For investors, pricing risk means deciding what return would compensate them for uncertainty. Frequent policy surprises make that calculation more difficult, even when an individual decision is intended to support growth.
Spending Plans Put Predictability Under Scrutiny
Prabowo's $20 billion free school meals program has added to creditor and equity investor concerns about fiscal discipline. The program is politically popular, but its scale risks weakening decades of deficit control. Authorities raised the budget deficit ceiling to 3% of gross domestic product, and faster government spending produced a rare budget shortfall in January 2026.
A budget deficit occurs when government spending exceeds revenue. The ceiling expresses the permitted gap as a share of the economy. Investors examining Indonesia's finances are watching both the spending commitments and whether the rules governing them remain predictable.
Muhammad Rizal Taufikurahman, head of the Center for Macroeconomics and Finance at Indonesia's Institute for Development of Economics and Finance, said investors need a consistent record more than immediate promises of growth:
Markets are not asking for pro-growth policies in the short term, what they need is predictability so risks can be calculated. Proof points of recovery are not policy statements, but track record: Two to three quarters with no regulatory surprises.
His proposed test places recovery over several quarters, rather than within a single announcement or trading session. It also connects the stock market's transparency problems to the broader policy environment: investors want reliable information about companies and reliable expectations about government decisions.
The administration has dismissed Moody's criticism and maintained its target of 8% economic growth by 2029. That stance keeps ambitious growth and social spending at the center of policy even as investors demand greater certainty about budgets, regulation and institutional independence.
Malaysia Offers a Regional Alternative
Malaysia has emerged as the primary beneficiary of regional capital reallocation as Indonesia's markets struggle. Hong Leong Investment Bank Research describes it as ASEAN's "safe harbour," pointing to political stability, market depth and regulatory transparency.
The research house places Malaysia between Singapore, where risk and yields are lower, and higher risk markets such as Indonesia. Malaysia's 25% minimum free float gives investors greater confidence in trading liquidity and in prices formed through genuine market activity.
Malaysia's appeal follows a difficult year for regional equities. The ASEAN-4 markets of Malaysia, Indonesia, Thailand and the Philippines recorded $10.3 billion in foreign equity outflows in 2025. Malaysia accounted for 50% of those withdrawals despite having the group's most stable political climate.
Trading activity strengthened in January 2026, when Malaysia's average daily trading value reached RM3.4 billion, higher than every monthly level recorded in 2025. Foreign inflows into bonds denominated in ringgit had reached RM3 billion in December 2025.
Malaysia is also the largest ASEAN constituent in the MSCI Emerging Markets index. That position gives global funds an established way to maintain regional exposure while Indonesia faces scrutiny over transparency. The contrast brings the practical value of clear ownership rules into focus: fund managers can compare access to shares, trading activity and regulatory stability across neighboring markets.
Resignations, Arrests and a State Investment Response
Five senior officials from the IDX and the Financial Services Authority (OJK) resigned in a single afternoon following MSCI's warning. They included IDX President Director Iman Rachman, who cited personal responsibility for the market events. The rapid departures demonstrated accountability while also raising concern about institutional continuity during the crisis.
Chief Economic Minister Airlangga Hartarto pledged firm action against market manipulation. Police arrested several brokerage executives suspected of rigging prices. The enforcement drive came alongside sudden fines for alleged stock manipulators, adding to investor concern about abrupt regulatory changes.
Temporary replacements for departing officials have proposed changes to free float and ownership disclosure rules. Their rapid, reactive introduction, with limited consultation, has left international observers unconvinced that the response offers lasting regulatory certainty. Enforcement has been welcomed by some investors, but the process of introducing rules remains part of the confidence problem.
Danantara, Indonesia's sovereign wealth fund, has presented itself as a market stabilizer. Chief Investment Officer Pandu Sjahrir announced daily investments in liquid stocks with strong business fundamentals. The fund conducts trading worth billions of US dollars daily and is targeting a trading value of $8 billion to $10 billion over the longer term.
James Athey, a fixed income fund manager at Marlborough, said the accumulation of recent policy steps was keeping him cautious:
I do feel like each of these steps is a little nick, a little cut that could add up into something bigger. What we've had recently I think is going to keep me sidelined for a bit longer. Because it's a hard one to price.
His comments capture the difficulty facing the government's response. Changes intended to support prices or strengthen supervision are arriving in a market already sensitive to unexpected decisions. Foreign fund managers remain cautious despite the state investment effort.
Yuan Borrowing Expands the Financing Options
Indonesia began marketing its second offshore yuan bond in four months on February 25, 2026. The government sought a benchmark sized sale in three parts, with maturities of three, five and ten years. The new transaction follows its six billion yuan debut in October 2025.
These securities are known as dim sum bonds, meaning bonds denominated in yuan and sold offshore. Indonesia is using record low offshore yuan interest rates to diversify its financing beyond dollar and local currency markets, while traditional funding channels face pressure from Moody's negative outlook.
The government is also seeking to refinance an estimated $3 billion to $4 billion in notes maturing this year. Refinancing means raising new borrowing to replace debt coming due. The timing places that task amid market volatility and deteriorating credit conditions.
Alessia Berardi, head of global macroeconomics at Amundi Investment Institute, warned that investor perceptions would harden and risk premiums would rise if leadership signaled tolerance for higher inflation or frequent central bank intervention to smooth fiscal operations. A risk premium is the extra return investors demand to accept greater uncertainty.
Government bonds provide a central gauge of confidence in Indonesia's economic management. Yields on government debt maturing in ten years have risen 34 basis points this year to 6.458%. A basis point is one hundredth of a percentage point, so the increase amounts to 0.34 percentage points. Higher yields increase the return demanded by investors and can make new borrowing more expensive.
Strong Public Support Meets Weak Market Confidence
Prabowo's domestic standing has remained strong even as investors retreat. Indikator Politik Indonesia's January 15-21 survey put his approval rating at 79.9%, up from 78% in November 2025. Gen Z voters and rural residents gave him his strongest support, while 72.8% of respondents expressed satisfaction with the free meals program.
The poll was completed just before MSCI's warning triggered the market collapse. It shows the president entered the crisis with substantial public backing for an agenda that investors increasingly associate with expansive spending and greater state intervention.
Prabowo's centralization of control and expansion of military involvement in civilian governance worry international investors. The same approach appeals to domestic constituencies seeking strong leadership and immediate economic relief. Public approval strengthens his mandate, while market participants seek fiscal discipline, transparent ownership and fewer regulatory surprises.
Indonesia's challenge therefore reaches beyond market branding. The administration must deliver visible benefits to voters while rebuilding confidence in the institutions that govern investment. The promised March reforms, FTSE Russell's May 22 review timetable and MSCI's possible May reclassification give that task concrete deadlines. Durable trust will depend on the ownership information investors receive and the consistency of decisions over time.
What to Know
- Indonesia has lost approximately $120 billion in equity market value since MSCI's warning in late January 2026.
- The JCI fell 4.73% in the first week of February, erasing roughly Rp 705 trillion ($41.6 billion).
- MSCI froze inclusion increases and new stock additions. A frontier market reclassification by May could prompt estimated outflows of $25 billion to $50 billion.
- FTSE Russell postponed its March index rebalancing until May 22, 2026.
- Authorities plan to raise minimum free float from 7.5% to 15% and tighten ownership disclosure to 1%, with implementation expected by March.
- Moody's changed Indonesia's sovereign credit outlook to negative on February 5 as policy and governance concerns mounted.
- Malaysia's 25% free float requirement and established index position have made it an alternative for regional investment.
- Indonesia began marketing another offshore yuan bond on February 25 while facing refinancing needs of $3 billion to $4 billion this year.
- Prabowo's approval reached 79.9% in a January poll, showing strong domestic support before the market crisis erupted.