Factory Weakness Is Becoming a Household Income Problem
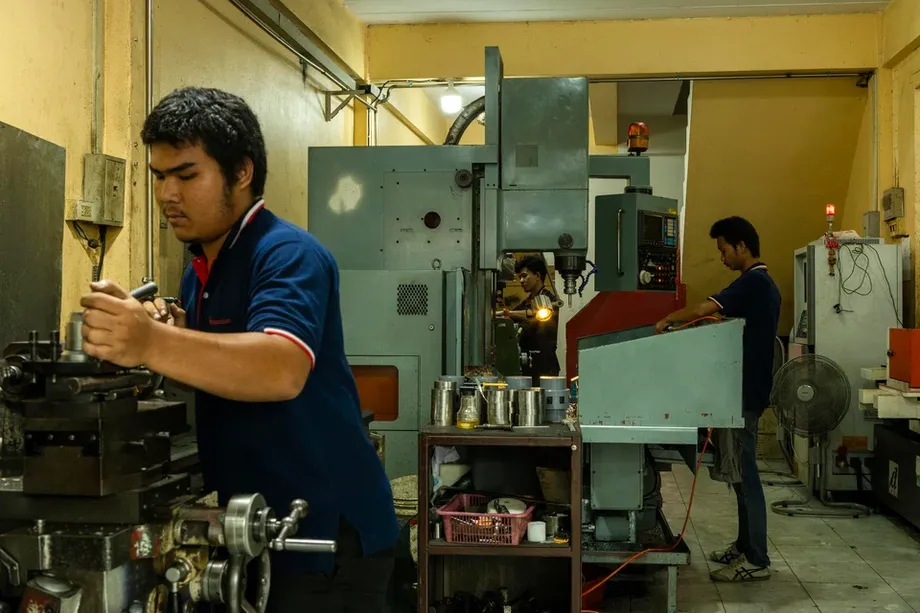
Thailand's workers are moving out of manufacturing and agriculture into services, but many are entering jobs paying just 114 baht an hour. Manufacturing jobs pay an average of 183 baht an hour, while modern services pay 703 baht. The Bank of Thailand is warning that this shift toward less rewarding work is weakening the income outlook and holding back the country's economic potential.
Contents
- Factory Weakness Is Becoming a Household Income Problem
- Three Wage Levels Reveal an Uneven Transition
- A Development Model That Has Lost Momentum
- Education Limits Access to Better Paid Work
- Regional Growth Exposes Thailand's Weakness
- Tourism Falls While Neighbours Recover
- Household Spending Faces a Further Slowdown
- Senior Policymakers Describe an Economy That Is Stuck
- Politics, Business Restrictions and Corruption Slow Reform
- Proposals Put Job Quality Ahead of Investment Totals
- The Bottom Line
From the recovery after the coronavirus pandemic in 2022 through the third quarter of 2025, Thailand's gross domestic product grew by an average of only 2.4%. GDP measures the value of goods and services produced in an economy. Services now account for 60% to 61% of Thailand's GDP, leaving growth increasingly dependent on a sector where many workers earn relatively little.
Pranee Sutthasri, senior director of the Bank of Thailand's macroeconomic department, described the movement of workers at a recent Monetary Policy Forum. She said manufacturing's contribution to the economy had steadily deteriorated as workers moved away from industry and agriculture toward services. Most of those moving were entering traditional services, where wage growth had been weak.
Most labour migration has gone into traditional service sectors, where average wages remain low at around 114 baht per hour, only slightly above the Covid-period level of 110 baht.
By January 22, 2026, the pressures extended beyond factories. Foreign visitor arrivals had fallen in 2025, hotel revenue was forecast to contract, and private consumption was expected to slow further in 2026. Thailand was relying more heavily on services to absorb workers at the same time that a major part of its service economy, tourism, was losing momentum.
The central concern is the kind of employment replacing industrial work. A growing service sector can support stronger incomes when workers enter productive, better paid occupations. Thailand's current movement is largely toward traditional services, where average wages have barely risen since the pandemic.
Three Wage Levels Reveal an Uneven Transition
Traditional service wages increased from 110 baht an hour during the pandemic to 114 baht, a rise of just 4 baht. Manufacturing wages rose from 173 baht to 183 baht, an increase of 10 baht. Modern service wages climbed from 558 baht to 703 baht, a much larger gain of 145 baht.
Those figures show how differently parts of the economy are developing. Modern services offer much higher average pay, but most workers leaving industry and agriculture are moving into the traditional service economy. The sectors absorbing labour are therefore providing limited support for household spending.
A comparison of the current averages makes the income gap easier to understand. Traditional service pay of 114 baht an hour is 69 baht below manufacturing's 183 baht, or about 38% lower. Modern service pay of 703 baht is more than six times the traditional service average. These are comparisons between sector averages; the central bank's concern is that the direction of labour movement is toward the lower paid part of services.
Thailand's weakening income outlook connects its production problems to daily household decisions. When earnings grow slowly, families have less room to increase spending. That limits the demand businesses need to expand, creating a cycle in which weak incomes and weak growth reinforce each other.
A Development Model That Has Lost Momentum
Thailand's industrial difficulties have developed over more than a decade. The country once achieved economic growth in double digits as workers moved from agriculture, where output per worker was low, into manufacturing, where productivity was higher. That movement helped raise production and incomes.
Rising labour costs have since slowed manufacturing expansion. Many industries requiring large numbers of workers, including textiles and electrical appliances, have closed operations or moved to neighbouring Laos and Cambodia. Lower wages and abundant workers with some industrial skills have made those countries attractive alternatives.
The weakening of the industrial base is often described as industrial hollowing out. Such a shift usually occurs in developed economies. Thailand is experiencing it while still a country with middle incomes, creating the risk that its population becomes old before it becomes rich.
Thailand's extremely low fertility rates are expected to bring rapid population ageing. Labour shortages add to the challenge: the economy needs to raise the value each worker produces while the population structure becomes less favourable to growth.
Policies centred narrowly on manufacturing for export have also left agriculture and services behind. A wide productivity gap separates the stronger parts of the economy from the less developed sectors where most workers remain. Productivity means how much a worker can produce, and persistent differences in it limit the growth of income per person.
Education Limits Access to Better Paid Work
Thailand devotes roughly 20% of its government budget to education, yet educational results remain poor. International assessments place Thai students low in mathematics, reading and science compared with their peers around the world.
The education problem affects the economy because expanding digital and knowledge industries need skills that many workers lack. A skills mismatch occurs when the abilities workers have do not match the requirements of available jobs. That makes it harder for people leaving older industries to enter sectors offering higher wages.
The contrast between traditional and modern service pay gives this problem a practical meaning. Modern services have recorded strong wage growth, but workers need suitable training and skills to reach those opportunities. Moving people between sectors without improving their access to better paid occupations leaves much of the income problem unresolved.
Training workers in new skills and updating existing skills are therefore central to the proposed response. The aim is to prepare people for a digital economy and for industries that create more value, rather than allowing the decline of manufacturing to channel them mainly into low paying services.
Regional Growth Exposes Thailand's Weakness
Thailand's economy grew by 1.2% compared with a year earlier in the third quarter of 2025, its slowest pace in four years. Vietnam grew by 8.22% during the same quarter, supported by strong industrial output and services. Malaysia expanded by 5.2%, with robust domestic demand and recovering exports.
Technology related production also showed a wide regional gap. Thailand recorded growth of 17.2%, compared with 73.8% in Taiwan, 53.5% in the Philippines, 43.9% in Malaysia, 38.3% in South Korea and 34.8% in Vietnam. Thailand's figure was less than half Vietnam's, illustrating its weaker position in this area of production.
Thai exports rose by 12.3% in 2025, but the gains were concentrated in a narrow set of products, mainly electronics. Earlier years had seen more balanced growth across a broader range of product categories. The concentration leaves the export economy dependent on fewer sources of expansion.
Imports also continued to surge, particularly from China. Thai manufacturing uses a large share of foreign components for assembly, meaning that relatively little of the content comes from domestic suppliers. Local content refers to the inputs supplied within the country, rather than brought in from abroad.
Thailand's role as an assembly hub therefore produces limited benefits across the wider domestic economy when much of the value is created elsewhere. Higher exports can bring more activity to assembly operations, while reliance on imported components limits the gains reaching Thai suppliers, wages and other businesses.
Tourism Falls While Neighbours Recover
Thailand received nearly 33 million foreign visitors in 2025, down from 36 million in 2024, a decline of 7%. The fall weakened one of the main engines of the service economy just as services were carrying more of the burden of employment.
Japan received 39 million visitors in 2025, up from 37 million a year earlier. South Korea's arrivals rose to 19 million from 16 million, while Vietnam welcomed 21 million, compared with 18 million in 2024. Thailand's decline contrasted with continued recovery in those neighbouring tourism markets.
A Bank of Thailand official described Thailand's position within the regional recovery:
"Thailand is the only country in the region where tourist numbers declined during the post-pandemic recovery period," the BoT official said.
Thailand's hotel industry faced a forecast revenue decline of 4.5% in 2025, which would mark its first contraction in five years. Fewer tourists, lower room occupancy and reduced income from related activities, including meetings and seminars, were weighing on the industry.
Hotel operators also faced higher operating costs, including rising labour wages. Intense competition limited their ability to pass those costs on to guests through higher prices. That combination squeezed profits in a sector expected to provide employment for people leaving factories.
The tourism comparison adds another layer to Thailand's economic difficulties. Manufacturing is losing strength, while an important service industry is under pressure from weaker visitor demand and rising costs. The jobs absorbing displaced workers are consequently exposed to their own business challenges.
Household Spending Faces a Further Slowdown
Private consumption was forecast to grow by 1.9% in 2026, down from 2.4% in 2025 and 4.4% in 2024. Private consumption is the spending households make on goods and services, so slower growth means a weaker increase in demand across the domestic economy.
Weak income growth was expected to make households more cautious. High household debt added to the pressures identified in Thailand's wider economic problems. With less room to spend, families could contribute to a continuing cycle of low demand and stagnant growth.
The figures span a recovery that has become increasingly fragile:
- 2022 to the third quarter of 2025: average GDP growth reached 2.4% during the period after the pandemic.
- 2024: private consumption grew by 4.4%, and Thailand received 36 million foreign visitors.
- Third quarter of 2025: GDP grew by 1.2% compared with a year earlier, the slowest pace in four years.
- 2025: exports rose by 12.3%, foreign arrivals fell to nearly 33 million, and private consumption growth was put at 2.4%.
- 2026: private consumption growth was forecast to slow to 1.9%.
The consumption and hotel figures are forecasts. They describe the expected direction of activity, while the central bank's wage figures explain why stronger household spending is difficult to sustain.
Senior Policymakers Describe an Economy That Is Stuck
Dr. Veerathai Santiprabhob, chairman of the Thailand Development Research Institute and a former Bank of Thailand governor, drew attention to a warning from Dr. Ekniti Nitithanprapas, deputy prime minister and finance minister. Ekniti had described Thailand's economy as facing a "stuck situation or may be falling off a cliff."
Veerathai said the finance minister's language showed the seriousness of problems left unresolved for years:
We rarely hear high-level executives who set economic policy acknowledge the truth so directly," Dr. Veerathai said. "This demonstrates the severity of problems that have been neglected for so long, resulting in Thailand's economy becoming stagnant, stuck, or about to fall off a cliff.
Indicators across nearly every sector showed Thailand's development lagging behind comparable countries. The weaknesses identified included stagnant national competitiveness, poor education, low agricultural productivity, government inefficiency, high household debt and markets dominated by large capital groups.
Veerathai's warning also concerned the cost of delay. The longer Thailand remains stuck, the more its resources erode relative to the investment needed for recovery. Repairing the economy becomes harder as the capacity to support that repair weakens.
Politics, Business Restrictions and Corruption Slow Reform
Thai prime ministers have averaged just over one year in office during the past 20 years. Such short tenures disrupt policy continuity and make sustained reform difficult. Governments have tended to favour measures promising quick results over changes requiring a longer commitment.
Thailand also ranks high among major economies for restrictions on trade in services. Rules affecting sectors such as telecommunications limit competition and can enable nominee arrangements lacking accountability. In such arrangements, ownership is held in another person's name.
The Foreign Business Act places strict limits on foreign ownership across many sectors. Those limits can discourage the capital and expertise needed to modernise services. The Eastern Economic Corridor seeks to attract industries using advanced technology, but wider reform is needed to improve the economy beyond that investment area.
Transparency International ranked Thailand 108th out of 180 countries in its Corruption Perceptions Index. Bribery and officials' discretionary powers create obstacles to efficient business operations. Together with an ageing population and labour shortages, these constraints create problems that monetary policy adjustments alone cannot fix.
The barriers affect several stages of economic development: attracting investment, allowing competition, improving public administration and preparing workers. Frequent political changes make it harder to address those needs through a consistent programme.
Proposals Put Job Quality Ahead of Investment Totals
Economists and policymakers have called for Thailand to move beyond a development model heavily reliant on tax incentives to attract foreign capital. Their concern is that attracting investment has not ensured that enough of its benefits reach the local population.
A proposed new industrial policy would focus on creating more value within Thailand and directing greater benefits to Thai citizens. Support measures would be judged more by the quality of jobs they create than by investment totals alone. Skills development and innovation would form part of that approach.
Trade and investment proposals include allowing foreigners to hold more than 50% of shares in service businesses and permitting foreign professionals to work in occupations facing shortages. The intended result is greater access to capital and expertise, alongside the transfer of knowledge to Thai workers.
Several sectors offer opportunities. Thailand's automotive industry is moving toward electric vehicles with government incentives. Digital services and logistics are positioned for growth, while renewable energy offers another opening as the government sets targets for greater use of clean energy.
Those opportunities depend on a stable political environment and reduced discretionary power for state agencies that can obstruct progress. Veerathai called for a completely new development model combining industrial policy, innovation, skills development and a government that helps economic activity advance. His warning was that without comprehensive reform, Thailand risks moving deeper into stagnation.
The Bottom Line
- Traditional service wages average 114 baht an hour, compared with 183 baht in manufacturing and 703 baht in modern services.
- Thailand's GDP grew by an average of 2.4% from 2022 through the third quarter of 2025; services account for 60% to 61% of GDP.
- Growth slowed to 1.2% in the third quarter of 2025, trailing Vietnam's 8.22% and Malaysia's 5.2%.
- Exports rose by 12.3% in 2025, with gains concentrated mainly in electronics and production reliant on imported components.
- Foreign arrivals fell by 7% to nearly 33 million in 2025, while hotel revenue was forecast to decline by 4.5%.
- Private consumption growth was forecast to slow to 1.9% in 2026, from 2.4% in 2025 and 4.4% in 2024.
- Reform proposals focus on better jobs, stronger skills, more open services and investment rules, and more consistent government policy.