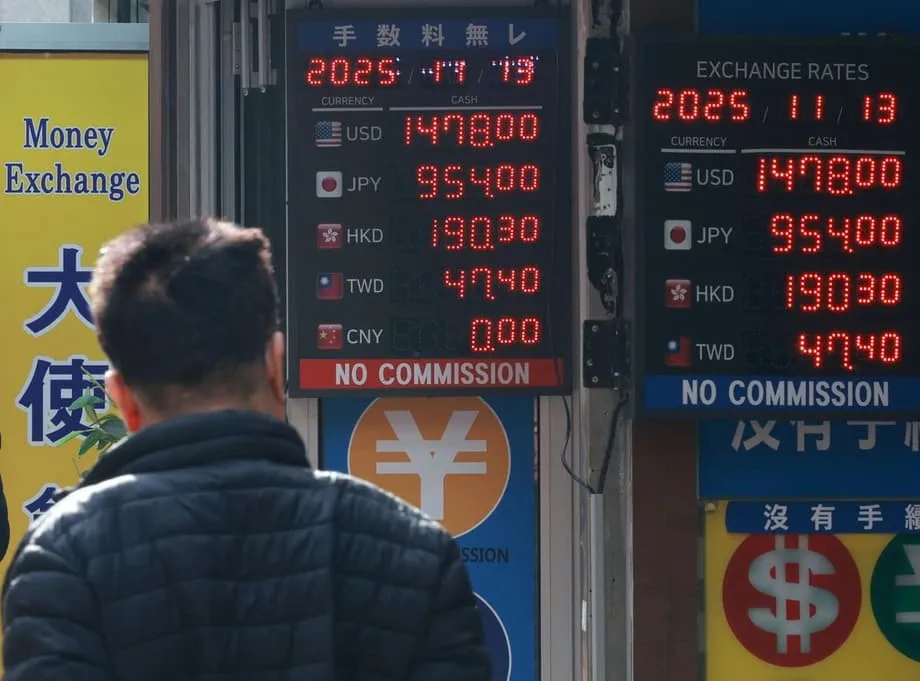
The won approaches a closely watched level
South Korea's won touched about 1,475.2 per US dollar during Thursday's trading before settling near 1,467.7, as a weakening Japanese yen added pressure to a currency market already facing strong demand for dollars. The won moved beyond 1,470 during the morning, bringing the closely watched 1,480 level back into focus ahead of November 14, 2025.
Contents
- The won approaches a closely watched level
- Why Japanese policy is weighing on the yen
- Households and businesses face higher import costs
- Why the won is moving with the yen again
- Seoul watches pension hedging and intervention
- The US investment package includes funding safeguards
- Dollar strength and funding strains add pressure
- Export gains compete with higher fuel and food bills
- What could bring the currencies some relief
- Key Points
Japan's yen fell into the mid 155 range against the dollar, its weakest level in about nine months. Its decline spread through Asian currency markets as elevated US bond yields and investors taking positions offshore in anticipation of further dollar gains supported the American currency.
The exchange rate tells readers how many won are needed to buy one dollar. A rise from 1,467.7 toward 1,480 means the won is weakening: Korean buyers need more of their own currency to pay the same dollar bill. For exporters receiving dollars, the calculation runs the other way, with those earnings becoming worth more won.
Seoul faces pressure from both abroad and at home. Expectations of spending that supports growth and gradual interest rate increases in Japan have weighed on the yen. Korean investors increasing their holdings overseas have added to immediate dollar demand, while uncertainty surrounding a planned investment package in the United States has complicated currency management.
Traders are watching whether large Korean institutions increase currency hedging near 1,480 and whether the Bank of Korea steps in to restrain excessive swings. Those possible sources of support sit alongside a broader concern: continued yen weakness could keep the won volatile even when Korea's domestic economic indicators are firm.
Why Japanese policy is weighing on the yen
US and Japanese interest rates are central to the yen's weakness. The Federal Reserve kept rates high to cool inflation, while US growth held up. The Bank of Japan has taken a slower path toward tighter policy. Even after ending negative interest rates, Japanese policy rates remain near zero, leaving a wide gap between the returns available in the two countries.
Investors can use that gap through a carry trade. They borrow in a currency with low interest costs, such as the yen, and invest in bonds or other assets offering higher returns elsewhere. Selling the borrowed yen puts pressure on Japan's currency, while investment in dollar assets can support the dollar and push it higher against the won as well.
The Bank of Japan's earlier policies also continue to matter. Years of quantitative easing, meaning large purchases of financial assets, expanded its balance sheet. Yield curve control, a policy used to restrain government bond yields, also kept domestic returns low. That legacy reduces the yen's appeal when investments elsewhere pay more.
Japan's weaker growth trend relative to the United States, partly linked to its demographics, discourages expectations of rapid interest rate increases. Its once reliable trade surplus has also narrowed under pressure from energy imports priced in dollars. When energy costs rise, Japanese buyers need more dollars to pay for fuel, adding pressure on the yen.
Prime Minister Sanae Takaichi has promoted advisers who favor fiscal policy that supports growth and a cautious approach to rate increases. Markets have interpreted that direction as tolerance for a weaker yen until its decline threatens stability. The currency recently reached fresh lows against the euro and is testing familiar weak ranges against the dollar.
Japan has intervened in currency markets before to slow rapid moves. Investors expect warnings and stronger official language before any large intervention. For now, the combination of interest rates, growth expectations, trade costs and policy signals has kept the yen soft through much of the year.
Households and businesses face higher import costs
Japanese Finance Minister Satsuki Katayama has acknowledged the growing burden on households and smaller businesses. After stressing the need for currency market stability, she described the costs associated with depreciation.
The negative side of the weak yen is becoming more evident.
A weaker yen makes imports priced in dollars more expensive for Japanese buyers. Those costs feed into producer prices, which measure prices received by businesses, and then, to a smaller extent, consumer prices paid by households. Companies can hedge against exchange rate changes or absorb costs in their profit margins, limiting the immediate increase on shop shelves.
Studies of Japan's price movements show a stronger connection between exchange rates and producer prices than consumer prices since 2021. One estimate for 2021 to 2024 puts the effect of exchange rate shifts on producer prices at roughly 0.023, compared with about 0.005 for consumer prices. These are estimates of the relationship between currency changes and prices; the larger producer figure points to greater pressure earlier in the supply chain.
Trade invoicing helps explain the pattern. Much of Asia's trade is priced in US dollars even when neither the buyer nor the seller is American. Japanese companies therefore face higher yen costs for imports billed in dollars. Japanese exporters, meanwhile, often set prices in the buyer's currency, delaying or reducing the effect of exchange rate changes on their selling prices.
Japan's industrial structure has changed the balance of benefits and costs. Decades ago, more exported goods were made at home, making yen weakness a more straightforward benefit to the real economy. Many manufacturers now produce through overseas subsidiaries. A soft yen brings gains through inbound tourism and the conversion of overseas profits into yen, while higher import prices affect a broader group.
Businesses can cushion rising costs through hedging, competition and smaller margins, but prolonged depreciation makes that harder. Protecting wages and profits while keeping prices under control becomes more difficult as the currency stays weak.
Why the won is moving with the yen again
Korean and Japanese companies compete in automobiles, electronics and machinery. A falling yen gives Japanese exporters room to reduce prices or accept lower margins while remaining competitive. Korean rivals then face pressure to adjust, and investors often respond by treating the two currencies as part of the same regional story.
The correlation between the yen and won over 90 days has risen to around 0.58 in recent weeks, from roughly 0.21 in late March, according to market strategists tracking regional currency pairs. Correlation measures how closely two things move together. The rise indicates that the currencies have recently been moving in the same direction more closely than they did earlier in the year.
The won has one of the strongest links with the yen among emerging Asian currencies over a longer period. The renewed connection is striking because, after the pandemic, the won spent long stretches moving closely with the Chinese yuan. As the yuan steadied in the second half of this year, investors shifted their attention back toward the yen.
Bank of Korea minutes from its October policy meeting acknowledged that market participants often group Japan and Korea together despite differences in their economies and financial connections. That treatment can shape currency movements even when domestic conditions point in different directions.
Portfolio managers handling regional investments may use the yen, which is easy to trade in large amounts, as a substitute for hedging other Asian exposures. Hedging means taking a position intended to offset possible losses elsewhere. When investors adjust regional exposure through the yen, the won can move alongside it even when Korean economic data remain firm.
Japanese manufacturers' pricing decisions provide another channel. If they use a weaker yen to defend market share, Korean competitors face a tougher selling environment. Currency trading and business competition can therefore reinforce the connection between the two currencies.
Seoul watches pension hedging and intervention
The 1,480 won per dollar area is the first major reference point for traders. It acted as resistance during earlier spikes, meaning the exchange rate had difficulty moving beyond it. Traders expect hedging flows to increase if the market approaches that level.
The National Pension Service, one of the world's largest asset owners, manages currency risk on overseas investments held for long periods. When a large fund increases hedging, it can sell dollars and buy won to balance its exposure. Those flows can slow the dollar's rise and reduce daily volatility. The precise pension hedging threshold has not been confirmed.
The Bank of Korea's response to rapid movements is the second reference point. The central bank does not set a fixed exchange rate, but it has a mandate to limit disorderly swings. It can use operations to smooth trading or provide liquidity, helping markets function when buying or selling becomes heavily concentrated in one direction.
Governor Rhee Chang yong has indicated that the bank will respond if currency volatility moves away from economic fundamentals. He described the central bank's readiness to act.
We are prepared to intervene if we detect signs of excessive volatility.
Recent official signals and operational support helped the won recover from its weakest levels during trading. Market participants still expect volatility to persist if the yen remains weak, but potential institutional hedging and the central bank's willingness to act provide nearby sources of support.
The US investment package includes funding safeguards
A recent Korea United States fact sheet set out ways to balance dollar funding for bilateral economic projects with foreign exchange stability. Korea would not be required to provide more than $20 billion in any calendar year, according to the document.
Korea would also use its best efforts to obtain dollars outside the open market, reducing the strain that public sector purchases could place on ordinary currency trading. The fact sheet allowed adjustments to the timing of funding if the market became unstable.
The arrangements address a practical concern around the planned US investment package. Large purchases of dollars during a period of currency stress could add to existing demand and make the won's decline harder to manage. An annual limit, alternative funding channels and flexibility over timing give officials ways to spread those needs.
Public sector funding is only part of the pressure. Korean investors have also been increasing overseas allocations, creating additional demand for dollars over shorter periods. The safeguards can ease concern about project funding while private investment flows continue to influence the market.
The sequence behind the current concern spans several periods:
- During 2021 to 2024, estimates for Japan showed exchange rate changes affecting producer prices more strongly than consumer prices.
- In late March 2025, the correlation between the yen and won over 90 days was near 0.21.
- During the second half of 2025, the yuan steadied and market attention shifted back toward the yen.
- At its October policy meeting, the Bank of Korea discussed investors grouping Japan and Korea together.
- By Thursday before publication on November 14, the won had touched about 1,475.2 per dollar and the yen had weakened into the mid 155 range.
Dollar strength and funding strains add pressure
Asia's currency markets are also responding to a stronger US dollar. Steady American growth and persistent services inflation have kept Treasury yields elevated. Investors have had to adjust to a slower path toward Federal Reserve rate cuts than they previously expected.
The resulting gap between US and Asian investment returns continues to favor dollar assets. The yen, yuan and rupee have lost ground this year, leaving central banks to balance support for economic growth against higher import prices caused by weaker currencies.
Short periods of tighter dollar funding have added another source of pressure. Analysts have pointed to changes in US government spending and heavy funding demand from large technology companies. At times, use of the Federal Reserve's standing repo facility has increased, signaling tighter conditions in cash markets. That facility provides short term cash against eligible securities.
Funding squeezes generally do not last long. They can ease when fiscal bottlenecks clear or central banks adjust their operations. An improvement would remove some of the pressure supporting the dollar, even if other forces, such as interest rate differences, continued.
Korean markets have shown an unusual combination: government bond yields and the won per dollar exchange rate rose together, while shares remained resilient. Strategists have linked that pattern to changing expectations for the Bank of Korea's policy path rather than credit stress. More settled policy expectations and calmer dollar funding conditions could help both yields and the exchange rate stabilize.
Export gains compete with higher fuel and food bills
Korean exporters can benefit when the won weakens. Dollars earned overseas convert into more won, and companies may gain room to compete on price. Semiconductor manufacturers could receive a particular boost during the sector's cyclical recovery: rising dollar prices for chips, combined with a softer won, can increase revenue and profit growth.
Korea's import bill moves in the opposite direction. The country imports most of its fuel, and oil is priced in dollars. Currency weakness raises costs for refiners, airlines and households, while food imports also become more expensive in won terms.
The amount reaching consumer prices depends on importers' hedging, retail competition and government policies. The Bank of Korea must contain inflation pressure without restricting growth too sharply, a more difficult balance when depreciation lasts for many months.
Oil prices can change that balance. If global oil prices stay within a limited range or fall, they soften the inflation effect of a weaker won. Under those conditions, gains for exporters can outweigh some of the higher import costs.
Foreign investors' response also depends on why the dollar is rising. Equity strategists argue that when stronger US growth pushes American yields higher, investors may take profits from Asian stock markets that have already risen substantially during the year. Such selling can weigh on Korea's KOSPI and KOSDAQ.
A calmer funding market and easier interest rate expectations can allow foreign capital to return. In that setting, a still weak won could continue helping exporters without producing a sustained decline in Korean shares. The same currency movement can therefore bring different results depending on interest rates, funding conditions and commodity prices.
What could bring the currencies some relief
Lower US yields would offer one route to relief. A slowdown in American growth would likely strengthen expectations of Federal Reserve rate cuts, make carry trades less attractive and help the yen recover. A firmer yen would ease some of the pressure on the won.
A gentler decline in US yields could also reduce dollar demand without a sharp growth slowdown. Less competition from high returns on American assets would help calm currency markets and reduce volatility.
Tokyo's policy decisions provide another possible turning point. A Bank of Japan signal that interest rates could rise faster, or Ministry of Finance intervention against a disorderly slide, could support the yen. Intervention tends to work best when it accompanies a change in the economic forces driving the market or when currency moves become too rapid.
Many investors believe Japanese officials are more sensitive to the speed of depreciation than a particular exchange rate, although trading discussions often focus on round numbers. The yen's pace of decline therefore matters alongside its level.
Korea has domestic supports as well. Growth exceeded expectations in the third quarter, its interest rate gap with the United States has narrowed, and semiconductor exports are recovering. Clear official communication and measures to manage volatility can work alongside those economic improvements.
The funding safeguards for bilateral projects provide another stabilizer by allowing public sector dollar needs to be paced and sourced away from the open market. With these supports, many investors regard 1,480 as a difficult level to break unless global dollar strength accelerates again.
Key Points
- The won passed 1,470 per dollar on Thursday morning, touched about 1,475.2 during trading and settled near 1,467.7.
- The yen weakened into the mid 155 range per dollar, its weakest level in about nine months.
- The correlation between the yen and won over 90 days rose from around 0.21 in late March to about 0.58 in recent weeks.
- Traders are watching 1,480, possible National Pension Service hedging and Bank of Korea action against excessive volatility.
- A bilateral fact sheet limits Korea's required annual funding to $20 billion and allows flexibility to protect currency market stability.
- Weak currencies help translate overseas earnings into more domestic currency but raise the cost of imports, including energy and food.
- Lower US yields, changes in Japanese policy, calmer dollar funding and Korea's improving economic indicators could ease pressure.