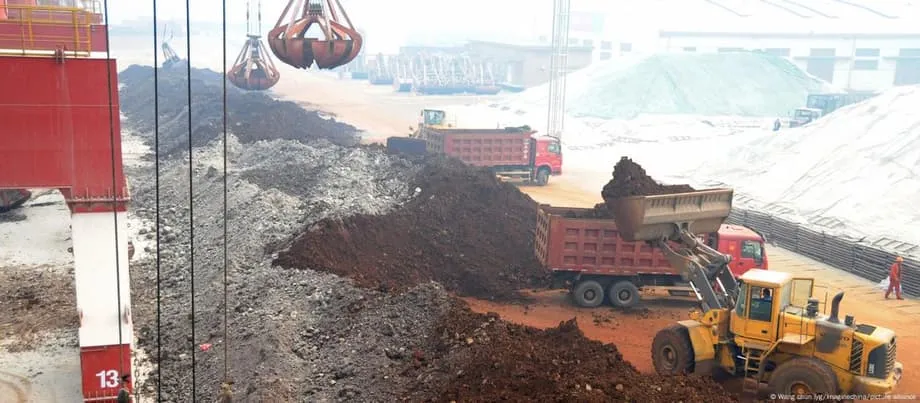
China's control reaches beyond its mines
China accounts for roughly 60 to 70 percent of global rare earth mining, around 90 percent of separation and refining, and close to 94 percent of permanent magnet manufacturing. Its dominance is even stronger in processing heavy rare earths such as dysprosium and terbium, which help magnets work at high temperatures. For manufacturers seeking alternatives, finding a different mine is only the beginning.
Contents
- China's control reaches beyond its mines
- Why these materials matter in everyday life
- How China built an industrial advantage
- The earlier shock that shaped today's response
- What changed in April and October 2025?
- Two way trade becomes a source of exposure
- Japan's partnership links money to supply
- US financing points to Australia's Goschen project
- Governments seek complete supply chains
- The Bottom Line
As of October 29, 2025, Beijing's expanded export controls are making that dependence more difficult to manage. Licensing requirements reach beyond ores to magnets and other products containing Chinese rare earth materials, including some goods made outside China. They also cover products made using Chinese extraction, separation or magnet technologies.
Thresholds can be as low as 0.1 percent for heavy rare earth inputs. Even a small amount of Chinese content somewhere in a company's supply chain can bring a product within the licensing system. Approvals can be slow, uncertain and, in some cases, unattainable.
The United States, Australia, Japan and the European Union are responding with financing, supply agreements and support for processing and magnet production. Their challenge is to build alternatives across an entire industrial chain, while keeping projects commercially viable through sharp changes in prices.
Why these materials matter in everyday life
Rare earths are a group of 17 metallic elements used in the motors, sensors and chips that keep modern life running. Their applications range from smartphones and medical devices to electric vehicles, wind turbines and radar systems.
Magnets made with rare earths can have high coercivity, meaning they resist losing their magnetism, as well as resistance to heat. Those properties help explain their value in electric vehicle motors and wind turbine generators, where magnets must keep performing under demanding conditions.
Dysprosium and terbium are especially important for magnets that need to operate at high temperatures. China's near monopoly in processing heavy rare earths makes these materials a particularly difficult part of the supply chain to replace.
Without reliable supplies, clean energy targets, advanced weapons production and the next wave of computing would be slower and more costly. The concentration of a relatively small materials market therefore creates a major strategic risk for the automotive, energy, aerospace and electronics industries.
How China built an industrial advantage
China assembled its rare earth industry over decades. Mining, separation, alloy production and magnet factories developed alongside a deep pool of engineers and equipment makers. Together, these businesses created an industrial network capable of taking material from the ground through to finished components.
Large production volumes, nearby mining and processing facilities, and looser environmental standards helped keep costs low. Feedstock, chemical reagents and skilled workers were close at hand, shortening the time needed to move materials through production and supporting continuous improvements in processing.
Separation and refining are central to that advantage. Mining produces material that still needs further treatment before manufacturers can use individual rare earth elements. The stages between a mine and a finished magnet turn concentrates into separated oxides, metals and alloys.
China's position at those intermediate stages explains why an alternative mineral deposit alone cannot provide an independent supply chain. Manufacturers also need processing capacity, the equipment and knowledge to operate it, and magnets that customers have approved for use.
The earlier shock that shaped today's response
Japanese manufacturers reported stalled shipments in 2010 after an incident in the East China Sea. A later trade ruling found that China had breached trade rules by restricting exports. The disruption exposed the risks of depending heavily on one country for essential industrial materials.
Prices surged, encouraging projects outside China to accelerate. When prices fell back, many of those projects collapsed. Investors retreated during the period from 2011 to 2016, leaving a thinner pipeline of alternatives just as demand began to surge.
Rare earth projects take a long time to develop, and customers need years to certify a new source of oxides, metals and finished magnets. Certification means checking that the material or component consistently meets the requirements of the product in which it will be used.
Price swings can undermine the financial case for a new mine or processing plant almost overnight. Once a project stops, rebuilding the necessary experience and equipment is difficult. Today's efforts to diversify supply must address both production capacity and the commercial pressures that weakened earlier attempts.
What changed in April and October 2025?
China introduced rules in April 2025 covering several heavy rare earths and products associated with magnets. Export volumes fell in the following months. Carmakers in the United States and Europe faced tight supplies of magnets designed for demanding applications, adjusted production schedules, and encountered higher prices outside China.
The scope widened in October. Licensing requirements now extend to magnets and other products containing Chinese materials or made using Chinese extraction, separation or magnet technology, even when the finished item is manufactured abroad. Applications connected to advanced chips and memory are subject to review individually.
From December 1, 2025, applications connected to foreign militaries will be denied. Chinese nationals also face restrictions on supporting rare earth projects overseas without authorization. The measures extend control into skills, technical knowledge and magnet production as well as the materials themselves.
The sequence shows how the restrictions developed from a materials supply issue into a broader challenge for manufacturing:
- 2010: Japanese manufacturers reported stalled shipments following an incident in the East China Sea.
- 2011 to 2016: Falling prices prompted many investors to retreat from projects outside China.
- 2023: Japan's partnership with Lynas extended to heavier rare earth elements.
- April 2025: China introduced controls covering several heavy rare earths and products associated with magnets.
- October 2025: China widened licensing requirements to include specified materials and technologies used in products made abroad.
- December 1, 2025: Denial of license applications connected to foreign militaries is scheduled to begin.
Two way trade becomes a source of exposure
Trade data shows that the United States exported increasing volumes of certain rare earth materials to China through 2022. Chinese factories then turned those inputs into components and finished products sold back into global markets.
That two way trade helped low carbon technologies spread and kept consumer costs low. When political relations are calm, countries and companies can benefit from relying on one another for different stages of production.
Licensing changes the way those connections work. Companies with even small amounts of Chinese content in their magnets can face legal scrutiny and waiting periods. A product made elsewhere can still depend on Chinese materials, processing or technology.
Diversification therefore has to cover the steps between mining and manufacturing. Separated oxides, metals, alloys and certified magnets all need dependable sources if businesses are to reduce their exposure to approval delays.
Japan's partnership links money to supply
Japan responded to the 2010 disruption by combining public financing, agreements to buy future production and technical support. The partnership between Sojitz, JOGMEC and Lynas in Australia created a stable pipeline of rare earth oxides for Japanese users.
An offtake agreement is a commitment to purchase output from a producer. Such arrangements connect financial support with a customer that needs the material, helping a project plan production around an expected market.
The Lynas partnership extended to heavier elements in 2023. Japan's approach tied funding directly to physical deliveries and quality assurance, helping shorten the lengthy process of approving new sources for industrial use.
The combination remains a model other countries can adapt: finance a credible producer, secure its output and support the technical work needed to bring that output into established manufacturing processes.
US financing points to Australia's Goschen project
The United States Export Import Bank has signaled up to $200 million in financing for VHM Limited's Goschen project in Victoria, Australia. The deposit contains both light and heavy rare earth oxides, alongside zircon and rutile.
Goschen has key approvals in place and is designed to expand production. Those features make it a candidate for agreements to supply electric vehicle and defense manufacturers over an extended period.
Andrew King, VHM's chief executive, described the financing signals as a turning point for supply chain security. He said support from a United States agency was a concrete step that could move a project from planning to construction.
The financing has been signaled rather than described as completed, and no construction date was given. The project's role in a wider supply chain will also depend on the processing and manufacturing stages needed to turn its output into usable components.
Governments seek complete supply chains
Washington is combining industrial policy with efforts to place more production in partner countries. The United States is funding mining, separation and magnet projects at home and with allies, while discussing a strategic reserve and minimum prices for domestic producers.
A strategic reserve would hold materials for use during supply disruptions. A price floor would give producers a minimum price, addressing the kind of sharp market declines that previously weakened projects outside China. Both measures have been discussed as part of the response.
New agreements announced across Asia seek to secure supplies, expand refining outside China and coordinate stockpiles with partners including Japan, Malaysia, Thailand, Vietnam and Cambodia. Australia is expanding production capacity and attracting development finance.
The European Union is pursuing new rules, targeted support and potential trade tools to reduce reliance. Japan continues to combine public capital, purchase agreements and technical assistance for credible producers.
These efforts target different parts of the same problem. Mines provide the starting material, processing plants produce usable ingredients, and magnet factories make components that customers must certify. Building reliable alternatives requires progress across all those stages, along with sustained investment through uncertain prices and lengthy approval processes.
The Bottom Line
- China supplies roughly 60 to 70 percent of rare earth mining, around 90 percent of separation and refining, and close to 94 percent of permanent magnet manufacturing.
- China's 2025 controls reach some products manufactured abroad through their Chinese materials or technology.
- Thresholds can be as low as 0.1 percent for heavy rare earth inputs.
- Applications connected to foreign militaries are scheduled to be denied from December 1, 2025.
- Japan's Lynas partnership connects financing, supply commitments and technical support, with heavier elements added in 2023.
- The United States Export Import Bank has signaled up to $200 million for VHM's Goschen project in Australia.
- Reducing dependence requires processing, metals, alloys and certified magnets as well as new mines.