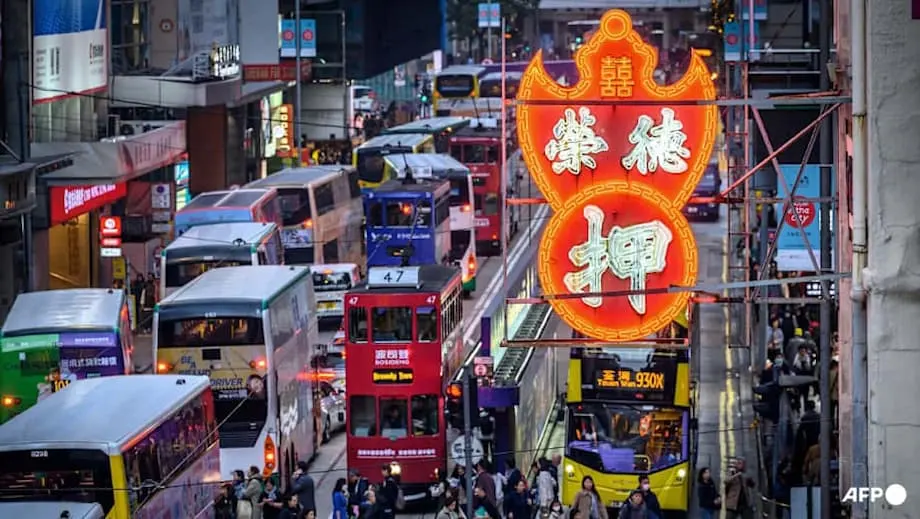
A financial revival with an uneven reach
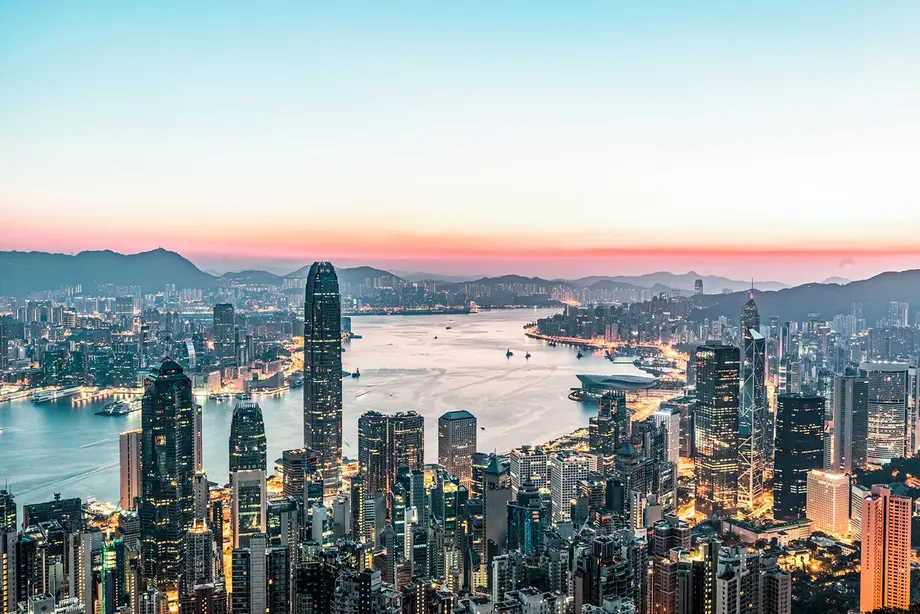
Hong Kong raised HK$107.1 billion through initial share sales in the first half of 2025, seven times the amount recorded a year earlier. The city ranks third in a major global financial centres index and fourth in a global talent ranking. Capital is returning, dealmaking is busier, and skilled workers are arriving at a pace not seen in years.
Contents
- A financial revival with an uneven reach
- Why share sales are driving confidence
- The promise behind Asia's world city
- How mainland connections power the market
- Talent returns, with a different mix
- Tourism grows faster than the street economy
- Sanctions reshape international outreach
- What international businesses are weighing
- Where Hong Kong is seeking its next advantage
- A more international role within a closer Chinese economy
- The Bottom Line
As of October 10, 2025, those gains mark a shift from the upheaval that followed the 2019 unrest, the introduction of the national security law in 2020 and prolonged pandemic restrictions. Those years prompted workers and companies to leave and weakened confidence in Hong Kong's role as a bridge between East and West.
The recovery now reaches trading floors, professional services and tourist districts, but its benefits are uneven. Some luxury businesses are thriving while smaller shops and restaurants face high rents and competition from cheaper destinations across the border. Global companies continue to value Hong Kong's legal system, freely convertible currency and financial markets, while weighing geopolitical tensions and questions about openness.
Mainland China sits at the centre of this revival. Chinese companies dominate the listing pipeline, mainland visitors account for most tourist arrivals, and mainland professionals make up most applicants to talent programmes. Hong Kong's renewed momentum therefore carries a strategic question: how much of its identity as Asia's world city can it retain as it becomes more closely tied to China's economy?
The answer matters beyond the financial sector. It affects which jobs become available, which customers sustain local businesses, where families choose to live and whether international companies continue to base regional operations in the city.
Why share sales are driving confidence
Beijing's stimulus push in late 2024 helped prepare the ground for the fundraising rebound. Stronger sentiment towards mainland businesses encouraged companies to seek capital, with Hong Kong providing a familiar venue for reaching international investors.
An initial public offering, or IPO, is a company's first sale of shares to public investors. Hong Kong's HK$107.1 billion total for the first half of 2025 illustrates how sharply that business has recovered. Professional services firms record a surge in listings, and forecasts point to the city finishing among the world's busiest listing markets in 2025. Analysts expect its strongest year for share sales since before the pandemic.
Mainland companies account for roughly 60 percent of businesses listed on the exchange and more than 80 percent of its market value. Their greater share of value means they carry even more weight in the market than their number alone suggests. They also dominate the pipeline of prospective listings.
Hong Kong's stock market has rallied as investors respond to improved sentiment about China and valuations they consider attractive. Prices nevertheless remain below peaks reached in the previous decade. The recovery in fundraising and trading has brought more work to banks, lawyers and other advisers, whose leaders describe their busiest conditions in years.
A leading financial centres benchmark places Hong Kong behind only New York and London, and ahead of Singapore as Asia's highest ranked centre. The index draws on professional assessments and more than 100 factors, with stronger business conditions, deeper markets and improved human capital supporting the city's position.
The promise behind Asia's world city
Hong Kong launched its Asia's world city brand in 2001. Research conducted locally and internationally identified qualities including enterprise, innovation, diversity and a cosmopolitan outlook. A red dragon symbol was intended to express confidence and connectivity.
The proposition rested on practical advantages: common law, low taxes, free capital flows, infrastructure of international standing and a bilingual workforce. Under one country, two systems, global investors could pursue Chinese opportunities through a city with distinct legal and financial arrangements.
For decades, the formula supported leading positions for the port and airport, attracted global banks to establish Asian headquarters and made the stock exchange a major centre for finance involving China. The last five years tested that appeal through tighter security legislation, worsening relations between the United States and China, and pandemic disruption.
The main stages of that change stretch across more than two decades:
- 2001: Hong Kong introduced its Asia's world city brand.
- 2019: Unrest began a period of disruption that was followed by departures of workers and businesses.
- 2020: The national security law took effect, while prolonged pandemic controls added to the pressures on confidence and mobility.
- Since 2022: Talent admission programmes have sought to replenish the workforce.
- Late 2024: Beijing's stimulus push helped revive sentiment towards mainland companies.
- First half of 2025: Hong Kong recorded HK$107.1 billion in initial share sales.
The challenge in 2025 is to preserve the international qualities behind the brand while building closer economic links with the mainland. Those two ambitions meet most directly in the city's financial markets.
How mainland connections power the market
Chinese technology, consumer and industrial companies use Hong Kong to reach international investors and raise capital in international currency. Beijing's stimulus has supported sentiment across priority sectors, including batteries, electric vehicles and advanced manufacturing. Large share sales by leading mainland businesses have generated lucrative assignments for banks and law firms.
The Connect programmes link markets in Shanghai, Shenzhen and Hong Kong. They let investors buy approved shares and bonds across the border while operating within China's controls on the movement of capital. In simple terms, they provide designated investment routes rather than unrestricted access to every asset.
These programmes have become the main channel for foreign portfolio investment into mainland markets and for mainland investors to buy a selected range of offshore assets. Their value to Hong Kong lies in connecting pools of money that otherwise face restrictions on investing across the border.
The same business brings closer scrutiny. As Hong Kong handles more transactions involving sectors Washington considers strategic, banks face sharper attention from US lawmakers and regulators. Large institutions have already received questions about their work on prominent Chinese deals. Compliance teams are expanding to manage changing restrictions.
Beijing's policy priorities also influence fundraising and corporate decisions. Nationalist voices online and in the media sometimes criticise commercial choices that favour Western partners. When a major local conglomerate explored selling port assets to a consortium led by US interests, hardline commentators condemned the proposed transaction as disloyal.
Logistics, finance and technology decisions can therefore carry political weight alongside their commercial purpose. Deeper integration gives Hong Kong access to business, but leaves companies operating within a narrower range of choices when transactions touch state priorities.
Talent returns, with a different mix
Hong Kong has climbed to fourth place in a widely watched global ranking of talent competitiveness, its highest position on record. Since 2022, talent admission programmes have received nearly 500,000 applications, approved more than 330,000 and helped more than 230,000 arrivals relocate.
The inflow is helping rebuild a workforce depleted during the pandemic years. Recruitment markets show a broader range of candidates willing to move to the city, while finance, technology services and professional advisory businesses report the strongest arrivals.
Low taxes, international schools of high quality and access to global platforms unavailable on the mainland make Hong Kong attractive to professionals seeking careers connected to China with continued international exposure. Moves in the United States to tighten oversight of foreign scholars have also contributed to the pressures drawing students and researchers towards Hong Kong and other Asian centres.
Most applicants come from the mainland. Their arrival connects Hong Kong with large and growing pools of engineers, financiers and entrepreneurs, although the headline totals give a fuller picture of recruitment volume than of international diversity.
Leaders in law, creative industries and healthcare argue that recruitment beyond Greater China would strengthen the city's standing as a global destination. Language matters in that effort. Businesses using English for international clients while maintaining Cantonese and Mandarin capability for regional work are better positioned to recruit broadly.
Some Western expatriates have moved to Singapore or returned to Europe and North America, citing family needs or corporate policy. Others are coming back as travel normalises and employment opportunities improve. A growing group from India and Southeast Asia is also building careers in Hong Kong, often in finance and technology support. Education and healthcare are recovering more slowly, reflecting tight global labour markets and lengthy accreditation processes.
Tourism grows faster than the street economy
Mainland travellers account for close to four in five arrivals in recent months. Rising visitor numbers have brought activity back to streets, trains and the airport, while hospitality businesses, transport operators and attractions rebuild their ability to serve demand.
Hotel occupancy is healthier than a year earlier. Luxury shopping districts report stronger foot traffic and larger purchases, with jewellery and watches among the successful categories. That pattern resembles earlier tourism cycles in which these products helped lead the retail recovery.
Many neighbourhood businesses face a different situation. Boarded shopfronts remain visible, and smaller restaurants and retailers must contend with high rents and strong competition from cheaper alternatives in Shenzhen and other mainland cities. Customers seeking similar goods, meals or experiences can find lower prices across the border.
Hong Kong's visitor recovery therefore affects businesses differently. More arrivals support hotels, transport and retailers serving mainland demand, while competition for spending continues to squeeze parts of the local economy.
Airlines based in Hong Kong have restored a larger share of their seats to the mainland and important regional markets. Carriers are expanding mainland and Southeast Asian services to capture connecting passengers, while the international aviation hub rebuilds capacity and long haul links.
Traffic connecting North America or Europe with China increasingly passes through Asian hubs, supporting Hong Kong's aviation role. Major attractions have expanded and hired aggressively in anticipation of sustained family and regional travel. Conference and exhibition calendars are also filling, helping the meetings and conventions business that brings weekday customers to hotels and restaurants.
Sanctions reshape international outreach
Hong Kong's efforts to attract international investment now follow a changing diplomatic map. Sanctions on senior officials complicate direct engagement with the United States and some European partners.
Government teams, the stock exchange and the financial regulator have responded by strengthening connections with the Middle East and economies along the Belt and Road. Saudi Arabia remains a target for major listings and investment flows, while business delegations have repeatedly visited Dubai and Doha to seek investors and companies considering share sales.
Investors in these markets value Hong Kong's access to mainland assets and Chinese technology supply chains. The outreach broadens the city's search for capital as engagement with parts of the West becomes more difficult.
Diplomatic activity inside Hong Kong also reflects security sensitivities. After the new US Consul General met local civil society figures, China's representative in the city publicly warned against contact with forces described as hostile. Such episodes show the narrower space for traditional diplomatic engagement.
Global banks and multinational companies are watching these signals as they assess what cooperation is permitted and how legitimate advocacy and research are treated. Their decisions involve both the commercial appeal of Hong Kong and the predictability of its operating environment.
What international businesses are weighing
Investors face two principal channels of geopolitical risk. Tighter US measures could limit Chinese companies' ability to raise money in Hong Kong or restrict the work global banks can perform on their transactions.
Perceptions present another risk. Some institutions may reduce their presence if they conclude that Hong Kong should be treated like a mainland city for compliance purposes. Such decisions would affect staffing, regional responsibilities and the amount of international business conducted locally.
Hong Kong retains features that continue to attract global asset managers and family offices, which manage the wealth of families. Its legal system remains grounded in English common law, its currency is freely convertible, and Connect programmes provide distinctive access to mainland capital and investments.
Security legislation introduced since 2020 has become part of daily operations. International businesses want rules that are clear, predictable and fairly applied, particularly where their activities involve data, research or speech. Many institutions have revised internal controls, reviewed how data moves between jurisdictions and changed internal policies.
The commercial effect depends on implementation. Targeted and transparent enforcement would allow companies to assess the costs and risks of staying. Unclear boundaries, or greater difficulty managing research and data across borders, could prompt renewed relocations. Predictability is central to whether companies can make commitments that last beyond the next transaction.
Where Hong Kong is seeking its next advantage
Singapore, Tokyo and Seoul compete with Hong Kong through their own combinations of legal predictability, financial incentives and lifestyle. Hong Kong is concentrating on activities where its market structure and mainland connections give it particular advantages.
Fixed income and currency trading are priorities. Fixed income covers investments such as bonds, while currency markets let businesses exchange money and manage changes in exchange rates. A roadmap aims to deepen liquidity, meaning the ability to trade without large price changes, and strengthen Hong Kong's role in hedging and settlement. Hedging helps manage financial risks; settlement completes transactions by transferring money or assets.
Green finance is another area of growth. The government has issued green bonds in multiple currencies and set targets encouraging environmental disclosure and planning for the transition to cleaner economic activity. These measures connect fundraising with information about environmental performance and future changes.
Digital finance is expanding through a licensing system that has enabled virtual banks and blockchain trials while maintaining tight controls on risks to ordinary investors. Blockchain is a way of keeping shared digital transaction records. Hong Kong is seeking financial innovation while limiting the exposure of retail customers to potential losses.
Other opportunities build on existing legal and financial strengths: resolving disputes and protecting intellectual property in transactions across borders; expanding Connect access to funds, swaps and exchange traded products; and attracting family offices through trust law, philanthropy arrangements and schools of high quality. Swaps are contracts used to exchange financial payments or exposures, while exchange traded products are investments bought and sold on an exchange.
A more international role within a closer Chinese economy
Integration with the Greater Bay Area is expected to continue accelerating. Hong Kong's strategic task is to remain the most international part of that larger regional economy while strengthening the financial connections that make it useful to the mainland.
An open internet, an active cultural scene and universities of international standing are part of that task. They help attract scientists and entrepreneurs who have choices about where to work. The same applies to transparency, free movement of capital and an outlook that welcomes people and businesses from abroad.
Hong Kong's 2025 revival shows the strength of its connection to Chinese companies, investors, professionals and travellers. Its ability to serve them through a distinct legal and financial system remains central to its international appeal. The precise shape of its next phase is unsettled: the markets have recovered faster than some neighbourhood businesses, and the return of talent has not restored the same mix of people who left.
The city can pursue a role as both China's international springboard and Asia's world city. Sustaining both depends on preserving the qualities that bring global businesses and individuals to Hong Kong while giving them practical reasons to stay.
The Bottom Line
- Hong Kong raised HK$107.1 billion in initial share sales in the first half of 2025, seven times the amount a year earlier.
- A major financial centres index ranks the city third worldwide, behind New York and London and ahead of Singapore.
- Mainland companies represent roughly 60 percent of listed businesses and more than 80 percent of market value.
- Hong Kong reached fourth place in a global talent ranking. Talent programmes since 2022 have approved more than 330,000 applications and supported more than 230,000 arrivals.
- Mainland travellers make up close to four in five recent visitor arrivals. Luxury retail is benefiting, while many small shops and restaurants remain under pressure.
- Sanctions and geopolitical tensions are encouraging stronger investment outreach to the Middle East and Belt and Road economies.
- Clear security rules, predictable enforcement and workable arrangements for data and research remain central concerns for international businesses.
- Growth priorities include bonds and currency trading, green and digital finance, dispute resolution, intellectual property protection and family offices.