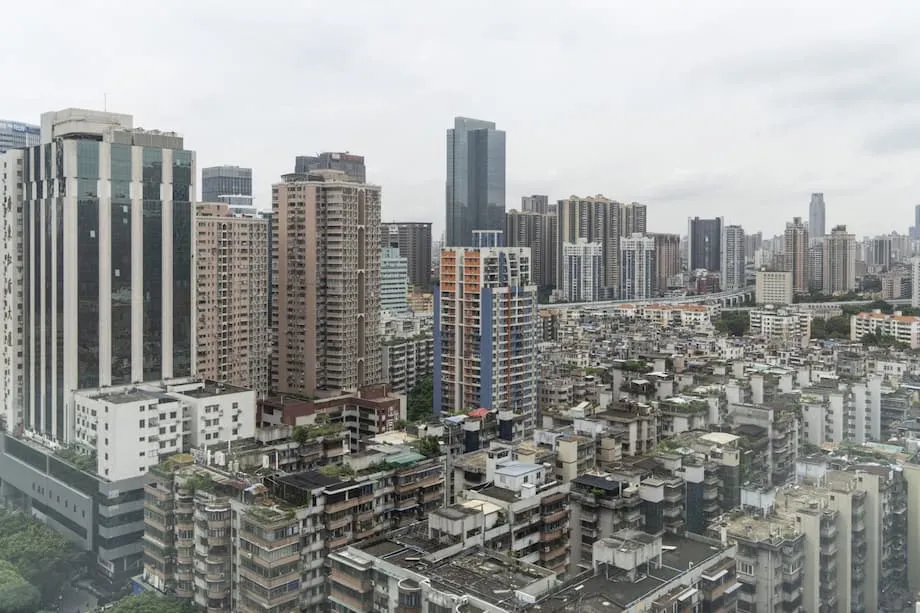
August sales extend a six month retreat
New home sales at China's 100 largest developers fell 17.6 percent from a year earlier to 207 billion yuan in August 2025, according to preliminary figures from China Real Estate Information Corp. The sixth consecutive monthly decline showed that cheaper mortgages, lower prices and relaxed buying restrictions had yet to bring a broad recovery in demand.
Contents
- August sales extend a six month retreat
- How far has the market fallen?
- Falling prices keep buyers waiting
- Delivery fears meet economic and demographic pressures
- What authorities have changed
- Shanghai shows a response, but confidence remains uneven
- Early signs of stabilization face a difficult test
- Evergrande's exit reflects a transformed industry
- Why the housing slump reaches beyond construction
- What a broader repair would involve
- The Essentials
The August fall followed a 24 percent annual decline in July. Sales were still shrinking despite efforts by China's biggest cities to make buying easier, leaving households, developers and local governments exposed to a property downturn that continues to weigh on the wider economy.
National Bureau of Statistics data showed new home prices fell 0.3 percent in July from June, matching June's monthly decline. Prices also continued their long run of annual falls. Weak sales, falling property values and cautious household spending have renewed concern about deflation, a sustained decline in prices, and the strength of China's recovery since the pandemic.
Beijing and Shanghai announced further steps in August to loosen purchase restrictions and reduce buying costs. Those changes have supported activity in some larger cities, but the national figures show how far the market remains from a sustained recovery.
Shanghai offered a glimpse of the response policymakers want: new home transactions rose more than 35 percent in the week after its easing measures late in August. The challenge is to turn such local bursts into lasting demand across a country where many buyers still worry about falling values and whether unfinished homes will be delivered.
How far has the market fallen?
July sales at the 100 largest developers totaled 211.2 billion yuan, nearly a quarter below a year earlier and 38 percent below June. August's 207 billion yuan total left sales below even that sharply reduced July level.
The longer comparison is more severe. Academic analysis puts monthly nationwide housing sales at less than half their level at the market peak in mid 2021. Real estate development has fallen by about a third, while housing starts, the beginning of construction on new homes, have shrunk by roughly two thirds. These declines are comparable with the most severe international housing corrections of recent decades.
ING estimates that national new home prices have fallen around 10.7 percent from their peak, compared with about 18.8 percent for used homes. Existing properties have therefore experienced a much larger loss in value, adding pressure on owners who need to sell before buying another home.
The downturn has continued through 2025 despite the already weak sales base of recent years. Smaller cities face especially difficult conditions because surplus housing and population pressures limit demand. State backed builders and properties in top tier locations have been more resilient, while many private developers struggle to obtain funding.
The main stages of the adjustment show how the crisis has moved from a market peak to prolonged financial and household uncertainty:
- Mid 2021: The market reached the peak used in comparisons showing subsequent nationwide monthly sales falling by more than half.
- Since late 2023: Officials have introduced repeated measures to lower buying costs, relax restrictions and support project completion.
- Early 2024: China Evergrande received a liquidation order.
- July 2025: Developer sales fell sharply and new home prices dropped another 0.3 percent from the previous month.
- August 2025: Beijing and Shanghai announced further easing, Evergrande was delisted in Hong Kong, and sales at the largest developers recorded a sixth monthly annual decline.
Falling prices keep buyers waiting
New home prices fell from the previous month in 60 of the 70 cities tracked in July, based on calculations using official statistics. Only a handful recorded monthly improvements. Annual prices fell 2.8 percent, a smaller decline than June's 3.2 percent, but the easing in the annual rate came alongside continued monthly losses.
First tier cities saw the pace of price declines ease slightly, and Shanghai recorded a small monthly gain. Many second and third tier cities continued to face broader price pressure. The national picture therefore combines pockets of resilience with widespread weakness.
Resale prices also fell on both monthly and annual measures in July. Declines narrowed in some smaller cities but widened in parts of the top tier. These prices matter to the market for new homes because households moving to a larger or better property often depend on selling their existing home first.
Annual price declines have lasted more than two years, changing how families view housing as a place to store wealth. A buyer expecting further falls may postpone a purchase, reducing sales and discouraging construction. Owners who feel poorer may also cut other spending.
Many buyers now prefer homes ready for occupation from developers regarded as financially sound, even when those properties cost more than homes sold before construction is complete. Demand has consequently shifted toward completed projects and state owned builders, widening the divide between stronger and weaker companies.
Delivery fears meet economic and demographic pressures
The International Monetary Fund has identified doubts about developer financing as a reason buyers hesitate. Presales, in which a household pays for a home before it is finished, historically accounted for a large share of transactions. When developers run short of money, buyers face the risk of paying for a property they cannot move into on time.
High profile developer defaults in recent years left some presold projects delayed. Those experiences made households more cautious about committing money in advance. Expectations of further price declines create a second reason to wait, even when mortgage terms become more attractive.
Youth unemployment, a soft labor market in some sectors and the desire to rebuild savings after the pandemic also weigh on confidence. Property represents a large share of household wealth in China. Falling values can encourage families to save more and spend less, weakening growth and reinforcing their caution.
Goldman Sachs estimates that annual demand for new urban homes could remain at roughly one quarter of the 2017 peak of about 20 million units in the coming years. That points to a smaller market even if immediate concerns about prices and delivery ease.
China's population has begun to shrink and age, urbanization is slowing, and fertility has fallen despite incentives. Reduced enrollment pressures in many school districts have also weakened a reason families previously paid premiums for homes near schools. These demographic forces add to the difficulty of clearing excess housing, especially in smaller cities.
What authorities have changed
Officials have taken numerous steps since late 2023 to stabilize housing. Mortgage rates and down payment requirements have fallen, while many cities have relaxed restrictions on who can purchase a home. These changes reduce the money needed at the start of a purchase and the cost of borrowing afterward.
Banks have been encouraged to support approved projects on a white list intended to help ensure delivery. The approach directs financing toward identified developments so construction can continue, addressing the risk that buyers pay for homes that remain unfinished.
Local governments have also been allowed to use special purpose bonds to help absorb excess inventory, including converting properties into public or subsidized housing. Such bonds allow local authorities to raise money for designated purposes. Officials have encouraged faster urban renovation, which can generate demand for replacement homes and upgrades.
Beijing and Shanghai added fresh measures in August. Analysts viewed the changes as supportive, while describing the broader policy response as incremental. Benefits have been most visible in larger cities, with no broad, sustained national rebound yet apparent.
The central problem is that cheaper financing addresses only part of a buyer's decision. Households also want confidence that a home will be completed and that its value will stabilize. Developers need enough cash to finish construction, while local authorities need funding to deal with unsold properties.
Shanghai shows a response, but confidence remains uneven
Shanghai's new home transactions rose more than 35 percent in the week after its easing late in August, while inquiries about both new and existing homes increased, according to industry trackers. Local analysts said the package lowered barriers to buying and improved credit conditions.
Lu Wenxi, an analyst at Centaline Shanghai, said potential buyers who had been waiting began making decisions as financing became cheaper and restrictions eased. Sales momentum was strongest in the middle and higher price segments, lifting the average transaction price during the following week.
That local response has kept attention on measures that could reduce unsold stock and give the market a firmer base. Yuhan Zhang, Principal Economist at The Conference Board's China Center, said urban renewal and public housing purchases could help if implementation worked:
Urban renewal initiatives and large scale public housing procurement could help establish a stable baseline for the sector, provided these policies are executed effectively.
ING analysts linked a sustained recovery in spending to households becoming more confident about property values:
Establishing a trough on prices is one of the most important factors to restoring confidence and generating a sustained consumption recovery.
Calls for a broader national package focus on the connected problems of legacy developer debt, delivery of presold homes and large stocks of unsold units. Local easing can bring buyers back in particular areas, but those financial and construction problems continue to affect confidence across the country.
Early signs of stabilization face a difficult test
Fitch Ratings revised its forecast for the decline in 2025 sales to a smaller contraction than previously expected, citing a better first half and continued policy support. Its assessment nevertheless described a polarized market, with stronger state backed companies and top tier locations holding up better than private builders and smaller cities.
HSBC analysts identified five early signs of progress: improving access to credit for stronger developers, faster consolidation, gradual clearance of inventory, firmer land auction results in selected areas and pricing more responsive to market conditions in top cities.
Market share has continued moving toward state owned builders, a shift many investors regard as supportive of project delivery and stability. Consolidation means a larger portion of sales and construction is concentrated among fewer companies, particularly those seen as better able to finish homes.
Official data also showed that the decline in new residential sales had slowed substantially compared with early 2024. Rising incomes and lower home prices improved affordability, while cheaper mortgages and relaxed eligibility rules expanded the pool of potential buyers. Existing home transactions in a sample of large cities increased from a year earlier as lower prices attracted bargain seekers.
Housing starts remain far below previous years, however, and developers continue to face tight cash flow. Inventory is still high in many places. Improvements in a handful of large cities have yet to spread widely to smaller markets, where population decline and weak job growth create sharper pressure.
Evergrande's exit reflects a transformed industry
China Evergrande's delisting from the Hong Kong stock exchange in late August followed its liquidation order in early 2024. The company, once China's leading developer by sales, had more than $300 billion in liabilities at its peak and became a symbol of a business model built on rapid expansion and heavy borrowing.
Most large private developers have defaulted or are restructuring debt. Restructuring involves changing repayment terms and dealing with obligations that companies cannot meet as originally agreed. The process has coincided with buyers moving toward state backed companies they consider safer.
Delayed projects have affected households across the country, extending the damage beyond any single company. Authorities have pushed local governments and state firms to help complete presold homes and acquire some unsold inventory where feasible. State linked builders are expected to take a larger role in completing developments and stabilizing construction as consolidation continues.
Local government budgets face their own strain. During the boom, land sales and property related taxes supplied major shares of local revenue. Weaker developer finances slowed land auctions and reduced proceeds, squeezing budgets and limiting public investment.
Those funding pressures also restrict the response to the housing slump. Analysts argue that many localities will struggle to buy large quantities of unsold homes or support extensive redevelopment without stronger central support or new revenue sources. Inventory purchases require money from authorities whose finances have already been weakened by the downturn.
Why the housing slump reaches beyond construction
Real estate's direct activity and its links to construction materials, appliances, furnishings and services have historically accounted for a substantial share of China's gross domestic product. Lower home sales therefore affect factories, shops and service businesses as well as developers.
Households may reduce discretionary purchases when falling property values make them feel less financially secure. Developers cut building and investment, while suppliers face excess capacity, meaning they can produce more than customers currently want to buy.
The housing adjustment has coincided with very low consumer inflation, negative producer prices and a falling GDP deflator over several quarters. Producer prices measure what businesses receive for their goods, while the GDP deflator is a broad measure of prices across the economy. Together, these trends point to weak domestic demand.
Private investment has weakened, foreign direct investment has slowed, and portfolio investors have been cautious about Chinese investments exposed to domestic demand. The property downturn affects both spending today and decisions about committing money for the future.
Outside China, weaker demand for commodities can affect prices and the economies that supply them. Excess capacity in construction materials and related manufactured goods can also spill into export markets, potentially increasing trade friction.
Chinese banks have so far avoided a severe hit to their capital partly because of regulatory forbearance, which gives lenders more flexibility in handling troubled loans. A longer adjustment increases pressure to recognize losses and resolve loans that borrowers are failing to repay.
What a broader repair would involve
The IMF has argued for faster restructuring of insolvent developers, stronger protection for buyers and the removal of rules that delay recognition of bad loans. International experience points to clearing troubled assets, ensuring delivery and allowing prices to adjust more freely as steps associated with turning points in housing downturns.
An IMF staff note called for banking rules that reflect financial conditions, a steady flow of funding for projects that can be delivered and better protection for buyers' presale money. On bank lending, it stated:
Rules allowing banks to avoid recognition of bad loans to developers should be phased out.
The same IMF staff note proposed protection against the risk that developers fail to finish purchased homes:
Insuring homebuyers against the risk that developers fail to complete purchased homes could help restore confidence and ease sales pressures for developers.
Clear procedures for completing presold homes could help buyers return. Support directed toward viable developers could preserve the ability to build and finish projects while allowing weaker firms to be resolved.
Longer term proposals include a nationwide property tax, deeper capital markets that give households more investment choices and stronger pensions. These changes could gradually reduce reliance on housing as a savings vehicle. Fiscal reforms could also lessen local governments' dependence on land sales and shift incentives away from expansion driven by construction volume.
Urban renovation and public housing purchases depend on adequate funding and targeting places with genuine need. Pilot programs that sell finished homes rather than presales address buyers' fear of noncompletion. Consistent policy communication could help households form expectations around a realistic floor for prices. As of September 2, the central challenge remained turning these measures into a sustained recovery extending beyond the strongest cities.
The Essentials
- August sales at China's 100 largest developers fell 17.6 percent from a year earlier to 207 billion yuan, extending a six month decline.
- July new home prices fell 0.3 percent from June and 2.8 percent from a year earlier; monthly declines affected 60 of 70 tracked cities.
- ING estimates prices have fallen about 10.7 percent from the peak for new homes and 18.8 percent for used homes.
- Shanghai's easing late in August was followed by a weekly increase of more than 35 percent in new home transactions.
- Delivery fears, expectations of further price falls, economic uncertainty and demographic change continue to restrain buying.
- Policy support includes cheaper mortgages, lower down payments, relaxed restrictions, project financing and purchases of excess housing.
- Stronger developers and large cities show tentative progress, while many smaller markets remain under pressure.
- The IMF's proposals focus on developer restructuring, recognition of troubled loans and stronger protection for homebuyers.