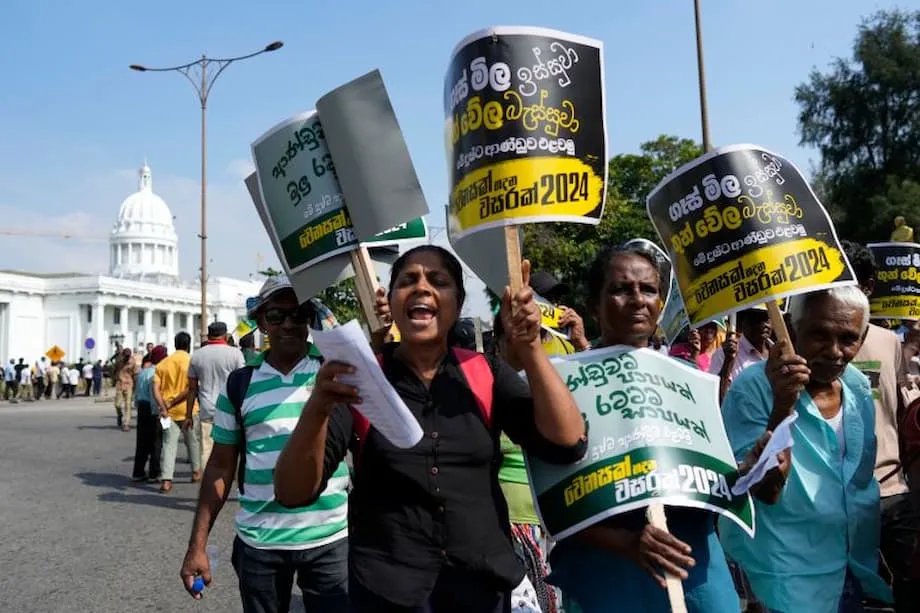
A debt agreement with a heavy public cost
Sri Lanka's $14.7 billion foreign debt restructuring promises relief from the crisis that brought the country to a standstill in 2022. Yet interest payments are expected to absorb 41 percent of government spending in 2025, leaving President Anura Kumara Dissanayake's administration facing a difficult choice between meeting creditor commitments and rebuilding public services.
Contents
- A debt agreement with a heavy public cost
- How the crisis overturned Sri Lankan politics
- What creditors agreed to change
- What the IMF program requires
- How the squeeze reaches households
- Why debt has become a question of rights
- The wider debt emergency in developing countries
- How borrowing became a recurring trap
- What alternatives are being proposed
- Kandy becomes a meeting point for alternatives
- Recovery requires more than financial stability
- Key Points
The agreement covers $12.5 billion in international sovereign bonds and $2.2 billion owed to the China Development Bank. Negotiated by the previous administration and subsequently endorsed by Dissanayake's government, it is central to the country's recovery program with the International Monetary Fund (IMF). Its terms also allow payments to creditors to rise if economic growth exceeds IMF projections.
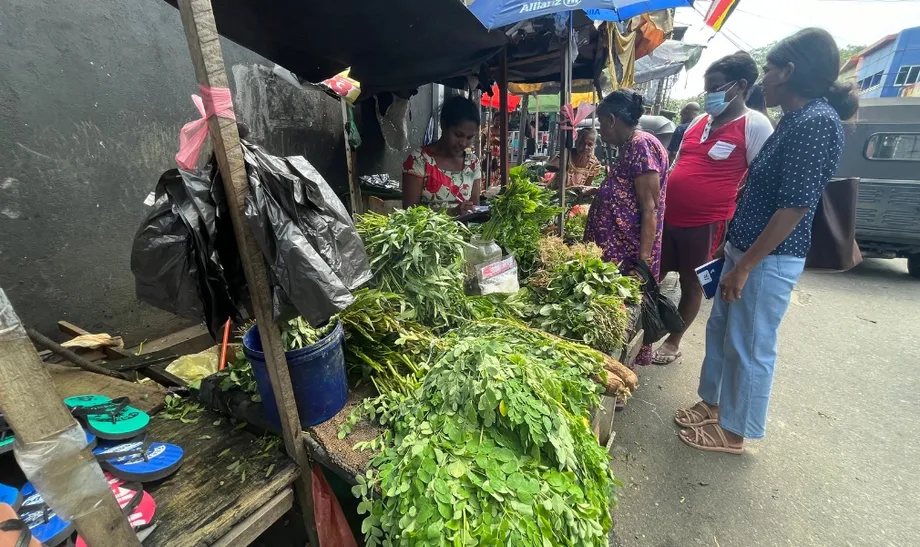
For households struggling with food prices, taxes and reduced support, the central issue is how much room the deal leaves for a better life. Civil society groups estimate that 6.3 million people are skipping meals and at least 65,600 face severe food shortages. Public health spending in 2025 is just 1.5 percent of gross domestic product (GDP), the value of goods and services produced by the economy.
Sri Lanka's experience has become part of a larger argument across the Global South, the broad grouping of developing countries, about who bears the cost of debt crises. Governments need money for food security, hospitals and development, while creditors expect repayment. The debate concerns how those competing demands are settled, and how much control elected governments retain over the choices.
How the crisis overturned Sri Lankan politics
Sri Lanka defaulted on its foreign debt for the first time in 2022 after running short of foreign exchange, the currencies needed to pay overseas suppliers. Food and fuel imports became difficult to finance. Years of unsustainable borrowing and poor fiscal management had left the economy vulnerable when several shocks arrived.
The 2019 Easter bombings damaged tourism. The COVID-19 pandemic and the global fallout from the Russia-Ukraine war then battered tourism and export revenues further. For an economy already struggling to meet its obligations, those losses helped turn financial pressure into a national emergency.
The Aragalaya citizens' protest movement demanded accountability and an end to political corruption, eventually forcing President Gotabaya Rajapaksa to resign. His successor, Ranil Wickremesinghe, delayed new elections and negotiated a $3 billion IMF bailout, Sri Lanka's 17th program with the institution.
Dissanayake's left leaning National People's Power (NPP) coalition achieved a sweeping electoral breakthrough in September 2024 on promises of economic justice and a break from past governance. Once in office, the administration faced commitments negotiated before its arrival and the financial conditions attached to continued international support.
- 2019: The Easter bombings dealt a blow to tourism.
- 2022: Sri Lanka defaulted on foreign debt, shortages intensified and protests forced Gotabaya Rajapaksa's resignation.
- September 19, 2024: The debt agreement at the centre of the subsequent endorsement was reached through negotiations under the previous administration.
- September 2024: Dissanayake's political victory brought a new government to power.
- November 14, 2024: A snap parliamentary election was called after the assembly was dissolved, with the new legislature scheduled to convene a week later.
- February 2025: Dissanayake's first budget speech acknowledged the limits on economic independence under IMF monitoring.
- September 2025: More than 500 delegates are expected in Kandy for the third Nyeleni Global Forum for food sovereignty.
What creditors agreed to change
The restructuring reduces part of Sri Lanka's obligations and changes the terms on which the remaining debt must be paid. Private creditors agreed to a 27 percent reduction in the loans covered by the arrangement and an additional 11 percent reduction in interest owed. A reduction in the amount a creditor is entitled to receive is commonly called a haircut.
The $12.5 billion bond component accounts for about 85 percent of the $14.7 billion total, with the China Development Bank component making up the remaining 15 percent. Sovereign bonds are loans raised by a government from investors, rather than directly from another government or an international institution.
Macro-Linked Bonds add another element: payments increase if Sri Lanka's economy grows faster than IMF projections. Creditors would therefore receive more when the economy performs better. Critics describe this arrangement as penalizing recovery because part of the benefit of stronger growth would flow into additional debt payments.
Dissanayake initially sought better terms but decided to honor the agreement after discussions with an IMF delegation in Colombo. The finance ministry confirmed the endorsement. Parliamentary ratification was also identified as a requirement, although a final ratification date was not given.
Public debt is projected to remain around 95 percent of GDP in 2032 even after restructuring. That means the debt stock would still be almost as large as a full year's economic output. The deal changes the repayment burden, while leaving Sri Lanka with substantial obligations for years.
What the IMF program requires
The IMF's Extended Fund Facility (EFF) program requires a primary budget surplus of 2.3 percent by 2025. A primary surplus means government revenue exceeds spending before interest payments are counted. Reaching it requires the state to collect more money, reduce spending, or combine the two.
Sri Lanka's reform program includes higher taxes, spending restraint and privatization of state enterprises. Its stated purpose is to restore economic stability and reassure creditors that the government can meet its commitments.
- Privatizing state enterprises and utilities.
- Freezing recruitment into the public sector.
- Delaying or canceling rural infrastructure projects.
- Reducing subsidies for fuel, agriculture and fishing.
- Increasing energy prices and removing price controls.
- Separating the Central Bank from direct state control.
Those changes affect both household budgets and the state's ability to invest. Higher taxes reduce the money people retain from their earnings. Lower subsidies shift more of the cost of fuel and production onto consumers, farmers and fishing communities. Restrictions on hiring and investment limit the expansion of public services.
Public investment has contracted sharply, while health and education budgets have stagnated. Working people's retirement savings, particularly the Employees Provident Fund (EPF), have also carried a heavy burden, and pension reforms have weakened retirement security for millions.
Dissanayake acknowledged in his February 2025 budget speech that Sri Lanka lacked economic independence and remained under IMF monitoring. His government pledged to raise public investment from 13 percent to 18 percent of expenditure, an increase of five percentage points. Economists warn that investment could be the first area cut if meeting IMF revenue targets takes priority.
How the squeeze reaches households
Families face the combined pressure of inflation, higher taxes and reduced public support. Real incomes, meaning what earnings can actually buy, have fallen as prices and deductions have absorbed more of household budgets. The estimates of 6.3 million people skipping meals and 65,600 facing severe shortages show the scale of food insecurity described by civil society groups.
Fishermen report that expensive fuel continues to eat into their earnings. Farmers face rising input prices, climate shocks and reduced state assistance. The government has restored some subsidies for agriculture and fishing, but many producers say that support is insufficient to cover the extra costs associated with austerity.
Public health spending of 1.5 percent of GDP in 2025 is about one fifth of the amount allocated to servicing public debt. Debt service includes payments due on borrowing, while the separate estimate that interest will absorb 41 percent of government expenditure measures interest against the government's spending budget.
Transport and irrigation projects have been delayed or canceled, alongside rural infrastructure work. Those decisions affect more than construction activity: transport supports access to jobs and markets, while irrigation helps farmers maintain production. Health and education budgets have meanwhile struggled to keep pace with rising costs.
Women and marginalized communities face a disproportionate burden. Job losses have affected sectors employing large numbers of women, while reduced services have increased unpaid care work and economic insecurity. Critics argue that IMF policies have deepened poverty and inequality, weakening the social stability that a recovery is supposed to support.
Why debt has become a question of rights
Ahilan Kadirgamar, a Sri Lankan political economist, argues that the program's budget requirements place repayment ahead of public needs. He describes the connection between fiscal targets and everyday hardship:
The IMF's program for Sri Lanka demands a high primary budget surplus, leading to increased taxes and austerity, and prioritizes debt repayment over social spending. This has resulted in severe economic contraction, with high food costs, reduced access to essentials, and cuts to public services.
The political dispute reaches beyond individual tax rates or subsidy decisions. Critics argue that international financial institutions and private creditors exercise substantial influence over national policy, narrowing the choices open to elected governments and undermining sovereignty and democracy.
A recent United Nations Human Rights Council roundtable described the debt crisis as fundamentally a human rights crisis. It called for changes to the international financial architecture, the institutions and rules governing finance across borders, to protect access to food, health and education.
Sri Lanka's change of government illustrates the tension. Voters backed promises of economic justice, but the new administration accepted a restructuring negotiated by its predecessor. Its ability to deliver public investment and social protection now depends partly on how much space remains after fiscal targets and creditor commitments are met.
The wider debt emergency in developing countries
The United Nations Conference on Trade and Development (UNCTAD) estimates that about 3.3 billion people, described as roughly half the world's population, live in countries spending more on interest than on health or education. Developing countries paid $921 billion in interest in 2024, with African nations among the hardest hit.
Debt payments exceed government revenues in many cases. Across the wider crisis, 118 nations face debt distress and 31 have either defaulted or lost access to external financing. Losing access means a government can no longer obtain the foreign borrowing it previously relied on to cover spending or repay older loans.
The World Bank says interest payments for countries with low incomes have quadrupled over the past decade. Private creditors, including banks, investment funds and pension funds, now hold almost half of developing countries' external public debt. Their willingness to accept losses can determine how quickly a restructuring proceeds.
Existing relief arrangements are widely criticized as fragmented, improvised and favorable to lenders. The G20's Common Framework for Debt Treatments has stalled, while critics argue that IMF programs often protect creditor interests ahead of borrowing countries' needs.
Zambia illustrates the delays: its 2020 default took four years to resolve, with private creditors negotiating better terms for themselves than public lenders. During a prolonged restructuring, governments remain under pressure to manage essential spending while negotiating who will accept reduced repayments.
How borrowing became a recurring trap
Many developing countries turned to the World Bank and IMF for financing after decolonization. From the 1980s, structural adjustment programs tied loans to cuts in social spending, privatization of public assets and greater openness to global markets. Critics argue that policies intended to reduce debt instead entrenched dependency, austerity and underdevelopment.
Developing countries' external debt has doubled roughly every ten years since 1980, multiplying by 19 between 1980 and 2023. Governments and private borrowers in the Global South, excluding China, paid more than $971 billion to foreign creditors in 2023 alone. In many countries, servicing debt now costs more than education or health.
The $971 billion figure covers payments to foreign creditors by both governments and private borrowers. UNCTAD's $921 billion figure concerns interest paid by developing countries in 2024. The two figures describe different measures and years within the same wider financial pressure.
Recent shocks have added to the strain. Rising interest rates in the United States and European Union increased financing pressure, while the pandemic and the Ukraine war weakened already vulnerable economies. Private financing dried up, prompting institutions such as the IMF and World Bank to provide emergency loans.
Those loans came with conditions involving austerity, privatization and economic liberalization. Private creditors' growing role, combined with their reluctance to accept substantial reductions, has made meaningful relief slower and more painful. Borrowers can end up taking new official loans while still struggling with obligations to private lenders.
What alternatives are being proposed
Campaigners and economists seeking a different approach want a permanent, transparent debt resolution mechanism that places development, justice and national sovereignty at its centre. Such a mechanism would provide a standing process for resolving unsustainable government debt, rather than assembling a new negotiation for each crisis.
- Unconditional debt cancellation for countries in distress.
- Reparations for historical injustices and climate damage.
- A United Nations Framework Convention on Sovereign Debt and wider changes to global financial rules.
- Responsible lending principles and automatic pauses in debt payments during shocks.
- New Special Drawing Rights (SDRs), alongside the transfer of unused SDRs through multilateral development banks.
- Debt-for-climate swaps that connect debt relief with green investment, as seen in Barbados.
SDRs are an international reserve asset created by the IMF that can help countries obtain usable currencies. Rechanneling unused SDRs would allow countries with less immediate need for them to support financing elsewhere. Debt-for-climate swaps seek to redirect some resources otherwise committed to debt into climate action.
The IMF's Resilience and Sustainability Trust (RST), launched in 2022, provides financing on concessional terms over long periods to address structural challenges such as climate change. Early experiences in Barbados and Jamaica suggest that connecting climate action with financial support can create room in public budgets for sustainable development. Critics say the sums remain too small and broader reforms are needed.
Borrowing countries are also coordinating through groups such as the Common Leveraging Union of Borrowers to strengthen their negotiating positions. Feminist approaches to debt policy are gaining visibility by examining how austerity affects women's employment, unpaid work and economic security.
Kandy becomes a meeting point for alternatives
More than 500 delegates from around the world are expected in Kandy in September 2025 for the third Nyeleni Global Forum for food sovereignty. Small producers, Indigenous peoples, trade unions and researchers will discuss alternatives to an economic model shaped by debt obligations.
The forum's themes include debt cancellation, climate reparations and democratizing debt governance. Food sovereignty concerns people's ability to shape how food is produced and distributed. In Sri Lanka, that debate connects directly with farmers' production costs, fishing communities' fuel bills and households' ability to afford meals.
The wider campaign for reform also surrounds the Fourth International Conference on Financing for Development (FfD4) in Spain. Advocates want changes that give governments more room to invest in sustainable and equitable growth, while placing people's dignity ahead of creditor profit.
Recovery requires more than financial stability
Sri Lanka is showing signs of stabilization through positive economic growth, low inflation, a tourism boom and a strong stock market. Those improvements give the government a firmer starting point than during the collapse, while hardship and debt commitments continue to constrain the recovery.
More than 300,000 people migrated in 2024 alone. The departure of skilled professionals threatens development over the longer term by reducing the expertise available to businesses and public services.
The administration's economic task includes expanding manufacturing, information and communications technology (ICT), and sustainable tourism, while strengthening ties with regional partners. Fiscal sustainability remains essential, and restructuring or privatizing loss making state enterprises may be part of that effort.
Weak state capacity and an inexperienced parliament complicate implementation. Building expertise in government and improving public service delivery will be necessary to translate spending commitments into results. International financial and technical support will also matter.
Sri Lanka's experience offers lessons for other countries with middle incomes confronting debt distress after the pandemic. Its immediate test is whether financial stabilization can support investment, secure livelihoods and public services while keeping debt manageable. The wider dispute concerns how international rules can give borrowing countries enough room to achieve those goals.
Key Points
- Sri Lanka endorsed restructuring covering $14.7 billion, including $12.5 billion in sovereign bonds and $2.2 billion owed to the China Development Bank.
- Private creditors accepted a 27 percent reduction in loans and an additional 11 percent cut in interest owed. Macro-Linked Bonds can raise payments when growth exceeds IMF projections.
- Interest is expected to absorb 41 percent of government spending in 2025, while public debt is projected at about 95 percent of GDP in 2032.
- The IMF program requires a primary budget surplus of 2.3 percent by 2025, alongside tax increases, spending restraint and other reforms.
- Civil society groups estimate that 6.3 million people are skipping meals and at least 65,600 face severe food shortages.
- Developing countries paid $921 billion in interest in 2024, while about 3.3 billion people live in countries spending more on interest than on health or education.
- Campaigners seek debt cancellation, climate reparations and permanent debt resolution rules. More than 500 delegates are expected at the Nyeleni forum in Kandy in September 2025.