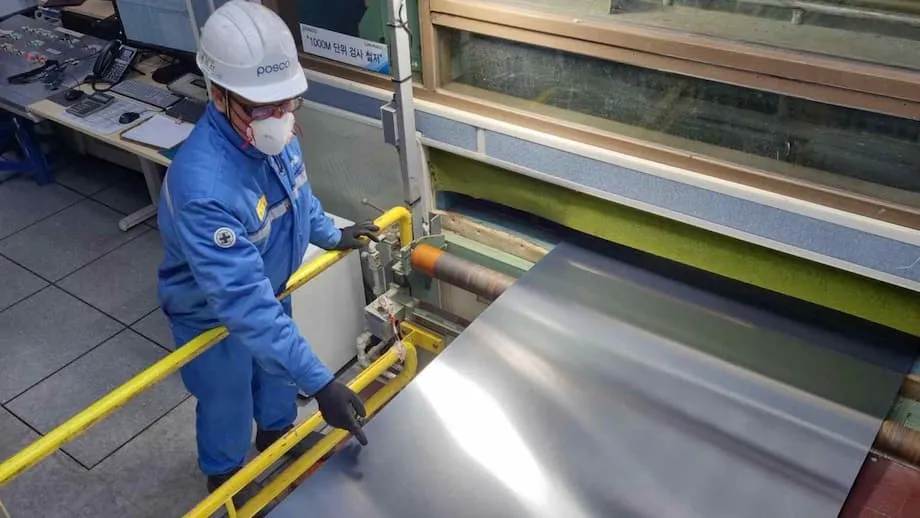
A major steel producer faces pressure on three fronts
South Korea, the world's sixth largest steel producer, is confronting US tariffs of 50% on steel and aluminum while its mills also struggle with weak domestic demand and growing competition from cheaper Chinese steel. As of August 31, 2025, those pressures are squeezing an industry long known for strong exports and advanced manufacturing technology.
Contents
- A major steel producer faces pressure on three fronts
- How US steel tariffs reached 50%
- China's export surge reaches far beyond America
- The dispute over dumping and cheaper imports
- Export figures show both a rush and a slowdown
- A Louisiana factory offers a longer term response
- Negotiations offer relief without removing every barrier
- Trade barriers spread costs through manufacturing
- What companies can change while tariffs remain
- Key Points
POSCO and Hyundai Steel face a difficult combination: construction and manufacturing customers at home are buying less, Chinese exports are pushing down prices, and American trade barriers are making Korean steel more expensive in a major overseas market. Excess production capacity and shrinking profit margins leave companies with less room to absorb another increase in costs.
South Korea is the fourth largest steel exporter to the United States, behind Canada, Mexico and Brazil, according to the account of US steel trade. That exposure helps explain why changes in Washington have shaken Korean producers and their investors.
The industry's response already includes a $5.8 billion Hyundai Steel factory in Louisiana, scheduled to open in 2029, with POSCO joining as an equity partner. Producing inside the United States would allow the companies to serve American customers without importing the steel across the border. The planned factory, however, leaves several years before that strategy can deliver its intended benefits.
Other export destinations offer no simple escape. South Korean producers are seeking customers in Southeast Asia, the Middle East and Europe, but trade restrictions are spreading there too. The challenge is to keep selling steel profitably while both competition and the rules governing access to markets are changing.
How US steel tariffs reached 50%
President Donald Trump's first major steel tariff measure came in 2018. His administration imposed a 25% duty on imported steel and a 10% duty on imported aluminum, citing national security under Section 232 of the Trade Expansion Act. That provision was the legal basis used to introduce the restrictions.
South Korea was among the countries that initially negotiated exemptions or quotas. A quota limits the amount of a product that can enter a market under an agreed arrangement. Those deals gave some exporters a different route into the United States, but the arrangements have since unraveled.
The Trump administration expanded the measures in early 2025, removing most country exemptions and raising the aluminum tariff to 25%. By June, it had announced 50% tariffs on steel and aluminum imports, with the restrictions also covering hundreds of derivative products, meaning goods made using those metals.
The main stages of the tariff changes and the industry's response were:
- 2018: The United States introduced tariffs of 25% on steel and 10% on aluminum under Section 232, while some countries negotiated exemptions or quotas.
- Early 2025: Washington announced the removal of most country exemptions and an increase in the aluminum tariff to 25%, with new measures taking effect from March.
- April 2025: South Korean steel shipments to the United States rose 12% compared with April 2024 as exporters rushed shipments ahead of further tariff increases.
- June 2025: The United States raised steel and aluminum tariffs to 50%. Lee Jae-myung also took office as South Korea's president that month.
- 2029: Hyundai Steel's planned Louisiana factory is scheduled to open.
A tariff is a tax on an imported product. For American buyers, it increases the cost of bringing Korean steel into the country. Korean suppliers then face pressure to lower their prices, accept smaller margins or risk losing orders. The measures taking effect in March and June therefore threaten both market share and profits.
China's export surge reaches far beyond America
China produces more steel than the rest of the world combined. Its property slump and slower construction have weakened demand at home, prompting mills to increase exports to Asia, Europe and other markets. For South Korean producers, that creates competition both inside their own country and wherever they seek customers abroad.
Chinese steel exports to the United States are already limited by tariffs and other trade restrictions. China's effect on Korean mills nevertheless extends beyond direct competition in America. When large volumes of steel reach other markets, buyers have more competing supply to choose from, putting pressure on prices.
China's excess capacity means its industry can produce more steel than domestic customers need. Years of aggressive investment, followed by a slowing economy, have helped create that surplus. The resulting flow of exports has depressed global steel prices and made it harder for competitors such as South Korea to maintain profitability.
Chinese steel is also becoming better in quality. Technological improvements, efficient supply chains and the scale of production strengthen its price competitiveness. Korean mills therefore face competition involving both cost and the capabilities of the products being sold.
South Korean shipbuilders, carmakers and electronics manufacturers face their own choices. Domestic steel can cost more, while cheaper imports can reduce production expenses. Reliance on imported steel also exposes those businesses to future trade barriers that could change its price or availability.
Weak construction and manufacturing demand within South Korea adds to the pressure. Mills have fewer domestic orders to help absorb their output at the same time that overseas markets are becoming harder to enter. That combination explains why finding new buyers alone may offer limited relief when global supply remains abundant.
The dispute over dumping and cheaper imports
South Korea's Ministry of Economy and Finance has announced an anti-dumping team to investigate unfair trade practices, particularly those involving China. The policy responds to concerns that imported products may be sold at unfairly low prices, placing domestic producers at a disadvantage.
Dumping is described here as selling below cost. Anti-dumping duties are additional import charges intended to address such pricing. The dispute concerns whether Chinese steel prices reflect unfair selling practices or the advantages of producing large quantities through an efficient industrial network.
The argument presented in the account of Chinese steel pricing is that there is little evidence of dumping in the South Korean market. It attributes competitive prices instead to China's advanced industrial chain and economies of scale. Economies of scale mean that making products in large quantities can reduce the cost of each unit.
The ministry's investigation and that argument point to different policy priorities. An investigation examines whether trade rules have been broken. The efficiency argument directs attention toward how Korean producers can reduce costs, improve products and compete with a much larger manufacturing base.
Additional duties could give Korean mills some relief from cheaper imports, while raising costs for Korean businesses that use steel. Shipbuilding and automotive manufacturing are especially relevant because affordable steel is an important production input. Higher material costs can put pressure on those companies and, eventually, their customers.
The policy discussion therefore includes investment, innovation, efficiency and new markets alongside trade protection. The industry needs profitable steel production, while the manufacturers buying that steel need reliable supplies at competitive prices. Decisions that help one part of that chain can create costs for another.
Export figures show both a rush and a slowdown
South Korean steel shipments to the United States rose 12% in April 2025 compared with a year earlier. Exporters rushed to move products before further tariff increases, a practice known as frontloading. It brings shipments forward so goods can enter a market before the rules become more expensive.
That rush is unlikely to be sustained. Industry executives have warned of growing burdens if US steel prices fail to rise enough to offset the higher costs. Once tariffs apply, suppliers and buyers must decide how much of the added expense each side can absorb.
South Korea's wider trade figures also show strain. The account of August export growth describes total exports rising 3% in August 2025, the weakest gain in months, while shipments bound for the United States fell 2.7% from a year earlier. Higher US tariffs were weighing on trade even as total exports continued to grow.
Shares in major steelmakers, including POSCO and Hyundai Steel, have fallen after tariff announcements, with declines of 3% and more reported. Investors face uncertainty about future earnings because changes in tariff rates can quickly alter the price at which companies can sell abroad.
Planning is difficult when both the tariff rate and the range of products covered can change. A producer may negotiate a contract or prepare a shipment under one set of expectations, then face different costs before the sale is completed. That uncertainty also affects decisions about investment and supply chains.
A Louisiana factory offers a longer term response
Hyundai Steel's proposed $5.8 billion Louisiana factory is a concrete response to the barriers facing imported steel. POSCO's decision to participate as an equity partner brings another major Korean producer into the project. An equity partner owns a share of the venture rather than simply supplying it or buying its output.
The plant is scheduled to open in 2029. Its purpose is to produce steel locally for the American market, avoiding the import tariffs that Korean mills face when shipping steel from abroad. It also reflects a broader shift toward placing production closer to customers in important markets.
The timing matters for the companies' current operations. Korean mills must deal with the present combination of weak demand, low prices and US duties before the Louisiana plant begins operating. Overseas investment can change where future steel is made, while existing factories still need orders and adequate margins.
South Korean producers are also looking toward Southeast Asia, the Middle East and Europe to reduce dependence on established markets. Diversification means spreading sales across more destinations so that a restriction in one country affects a smaller share of business.
The United Kingdom illustrates the limits of that approach. It has recently imposed stricter quotas on steel imports from South Korea, Vietnam and Algeria, with volumes above the limits facing a 25% duty. Selling more steel into another market can therefore bring an exporter up against a different restriction.
More countries are trying to shield their mills from global oversupply. For South Korean companies, choosing a new destination increasingly requires attention to both customer demand and the amount of steel that can enter under local trade rules.
Negotiations offer relief without removing every barrier
President Lee Jae-myung, who took office in June 2025, has sought agreements with the United States based on mutual benefits and industrial cooperation. South Korea has pursued exemptions and trade deals, but negotiations have moved slowly and have been complicated by political transitions.
Lee described a recent agreement as connecting US efforts to rebuild manufacturing with Korean companies' ambitions in the American market:
This agreement is the outcome of aligning the US interests in revitalizing its manufacturing industry with our determination to expand the competitiveness of our companies in the US market. Through this, we anticipate that industrial cooperation between Korea and the US will be further strengthened, and the Korea-US alliance will become even more solid.
Kathleen Oh, chief Korea economist at Morgan Stanley, assessed the recent US-South Korea trade deal in terms of the harsher outcome it prevented:
the worst avoided
Oh's assessment was that the agreement prevented more severe tariffs while doing little to resolve the underlying pressures on the industry. Many existing tariffs remain in place, and further relief is uncertain.
South Korea's reliance on exports makes access to the American market valuable. Its need to balance relations with both the United States and China also complicates negotiations. China is central to the competitive pressures facing Korean steel, while Washington controls the tariffs on an important destination for Korean exports.
Trade barriers spread costs through manufacturing
The United States has used tariffs under both the Trump and Biden administrations to protect domestic industries and address perceived unfair practices by China and other countries. China, the European Union and Canada have imposed retaliatory tariffs on US goods, adding further barriers to international trade.
Steel now moves through an increasingly fragmented market. A product can face different prices, duties and quantity limits depending on its destination. Manufacturers must account for those differences when choosing suppliers, arranging deliveries and setting prices for their own products.
American automotive and construction businesses face higher input costs when imported steel becomes more expensive. Those costs can reduce their competitiveness and contribute to inflation. Supply chain disruption and uncertainty add another burden for companies that need dependable deliveries of metal.
South Korean steel users face a related tension. Measures designed to support domestic mills can make steel more expensive for shipbuilders and carmakers, while cheaper Chinese supply puts pressure on the producers supplying those industries. The effects extend across manufacturing rather than stopping at the steel mill.
China's surplus production continues to weigh on prices, with no sign in the August 2025 account that the global glut is easing. More trade barriers create the risk of a prolonged trade war, with negative consequences for economic growth and stability.
Chelsea Ye of McCloskey has identified the volatility of US trade policy as a major source of uncertainty. Frequent changes in rates and product coverage make it harder for companies to plan investments and manage supply chains, even when they have a clear view of customer demand.
What companies can change while tariffs remain
South Korean steelmakers are pursuing several responses to the pressures they face. Advanced manufacturing investment aims to improve processes and produce steel of greater value, giving mills more ways to compete beyond the lowest price.
Overseas factories and joint ventures can bring production inside key markets, as the Louisiana project is intended to do. New export destinations in Southeast Asia, the Middle East and Africa could reduce reliance on the United States and China, although expanding sales remains difficult where governments are tightening import rules.
Cooperation with domestic customers is another part of the response. Stronger supply chains can help secure stable access to raw materials and components while keeping costs manageable for both mills and the industries buying their steel.
The policy argument for innovation, efficiency and supply chain development reflects the lasting competitive challenge posed by China's production scale. Anti-dumping duties may provide temporary relief, but they can also raise costs for downstream manufacturers and consumers. Korean companies face the task of adapting to trade protection, technological change and shifting demand while their major overseas investments take shape.
Key Points
- South Korea's steel industry faces weak domestic demand, cheaper Chinese imports and US tariffs of 50% on steel and aluminum.
- China's large production capacity and weaker domestic construction demand are pushing more steel into overseas markets and depressing prices.
- Korean steel shipments to the United States rose 12% in April 2025 as exporters brought deliveries forward ahead of further tariff increases.
- August trade figures show total South Korean exports rising 3%, while shipments to the United States fell 2.7% from a year earlier.
- Hyundai Steel plans a $5.8 billion Louisiana factory opening in 2029, with POSCO participating as an equity partner.
- The United Kingdom has tightened steel quotas for South Korea, Vietnam and Algeria, applying a 25% duty to excess volumes.
- Trade negotiations have prevented harsher outcomes, but many tariffs remain and Korean producers still face pressure to improve efficiency, products and market access.